
404K SEMI-AI 2026-07-24 AI Supply Chain Weekly — Compute Rationing, Advanced Packaging Expansion, and the Revaluation of Energized Capacity
目录
Executive Summary
Overall View This Week
AI Chips, Advanced Packaging, and Servers
Optical Communications, CPO, PCBs and High-Speed Interconnects
Data-Center Cooling, Power Supplies and Electricity
Robotics, Edge AI and Hardware Applications
Space, Quantum Computing, and AI Software Applications
Divergences, Counterevidence, and What to Monitor Next Week
Models are becoming cheaper and more efficient, yet compute capacity is not sitting idle. This week, demand continued to spill over into rack-scale systems, advanced packaging, networking, PCBs, and power infrastructure. The greatest risk is that capital expenditure precedes cash returns.
Executive Summary
Inference demand is absorbing architectural efficiency gains. Kimi K3 has 2.8 trillion parameters and a 1 million-token context window, and came close to the limit of existing GPU capacity within 48 hours of launch. It demonstrates that improved model efficiency lowers the cost per call, but larger models, longer contexts, and more agentic workloads will once again fully utilize HBM and compute resources. Key indicators to watch are usage after the open-weight release, the timing of subscription restoration, and additional capacity.
Compute competition has shifted from individual chips to complete systems. Chinese vendors are increasingly adopting 64–128-accelerator supernodes as a standard configuration, while Huawei’s Atlas 950 scales further to 1,024 NPUs. Prefill/Decode disaggregation, chip-to-chip interconnects, shared memory, scheduling, and fault tolerance are beginning to determine effective throughput. Single-chip performance remains important, but more revenue will flow to advanced packaging, switching networks, liquid cooling, and server-management chips.
Order evidence for advanced packaging and PCBs continues to strengthen. BE Semiconductor Industries reported approximately €293 million of orders in the second quarter, while the number of hybrid-bonding customers increased from 15 at the end of 2025 to 21. Eoptolink’s 800G and 1.6T optical modules are ramping, Han’s Laser received RMB16 billion of new orders in the first half, and the Kingboard Laminates supply chain expects the shortage of electronic-grade fiberglass cloth to persist until at least the end of 2027. Risks include relaxed HBM stack-height requirements, delayed CPO adoption, and pricing pressure following capacity expansion.
The truly scarce data-center resource is “capacity that can be energized on schedule.” U.S. data centers could face a power shortfall of approximately 38GW by 2028, while grid-connection waits have already exceeded 5 years in some regions. GE Vernova’s second-quarter Electrification orders reached $6.347 billion, up 93% year over year, and its first-half data-center orders exceeded $5 billion. Order visibility for power-supply equipment, onsite generation, transformers, solid-state transformers, and 800V direct-current architectures is higher than for unsigned data-center campus concepts.
Applications are beginning to generate returns, but company performance is diverging significantly. Google Cloud’s second-quarter revenue increased 82% year over year, with backlog reaching $514 billion, demonstrating that some AI capital expenditure has already translated into revenue. ServiceNow raised its full-year subscription revenue guidance, while internal automation at SS&C; has generated approximately $200 million in annualized savings. Workday’s AI revenue remains at the pilot stage, indicating that companies controlling workflow, data, and governance entry points are better positioned to monetize.
Valuation risk stems from cash flow and the pace of execution, not a sudden disappearance of demand. Google’s forecast 2027 capital expenditure was raised to approximately $378 billion, putting pressure on free cash flow; term premiums and supply pressure for AI-related bonds are rising. On the hardware side, risks also include project share, yield, certification, and delivery schedules falling short of expectations. Next week, priority checks should include cloud providers’ capital expenditure, optical-module and PCB shipments, hybrid-bonding orders, data-center power-equipment backlog, and the success rate of continuous robot operation.
Overall View This Week
Incremental growth in the AI supply chain can no longer be assessed solely through GPU shipments. A more explanatory signal has emerged at the model layer: higher performance and lower prices are expanding the range of viable use cases, but frontier models are reinvesting the resources saved into more parameters, longer contexts, and extended inference time. Kimi K3’s rapid approach to its capacity limit after launch provides real-world validation of this transmission mechanism.
As this dynamic moves upstream, it first drives demand for HBM, advanced logic, and advanced packaging. As it reaches the system layer, it drives switching networks, optical modules, PCBs, server power supplies, and management chips. At the infrastructure layer, it ultimately translates into demand for land, grid connections, transformers, onsite generation, and cooling. Investors should distinguish between segments already supported by orders or capacity-utilization evidence and those supported only by long-term market potential.
Inference demand has shifted the valuation anchor from individual chips to complete systems
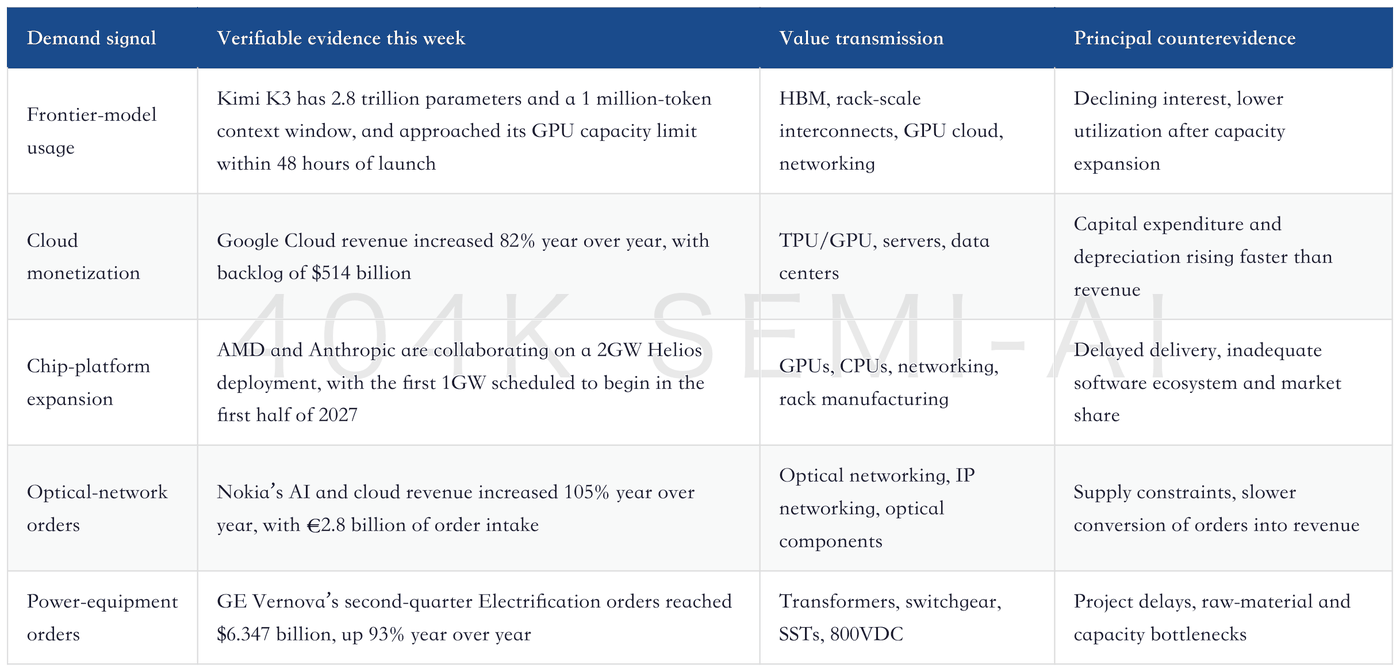
The capital-market debate has shifted accordingly. Whether demand exists can now be answered through model rationing, cloud backlog, and equipment orders. The more difficult questions are who funds the investment upfront, when power becomes available, when revenue is recognized, when depreciation and interest expense reach the income statement, and whether elevated valuations have already priced in many years of growth.
AI Chips, Advanced Packaging, and Servers
China’s domestic AI infrastructure is using systems engineering to offset single-chip constraints. Mainstream solutions at the World Artificial Intelligence Conference have shifted from single-chip benchmarks to 64–128-accelerator supernodes, while the Atlas 950 scales further to 1,024 NPUs. Effective throughput depends on interconnect bandwidth, shared memory, scheduling, fault tolerance, and software optimization. Prefill/Decode disaggregation is also moving from an experimental architecture toward a common cost-reduction approach for inference at scale.
This means that beyond chip revenue, switching chips, optical interconnects, liquid cooling, cabinets, and advanced packaging will capture greater value per system. The risks are equally clear: increasing the accelerator count in a supernode does not automatically improve utilization. Heterogeneous scheduling standards, failure recovery, model workload composition, and customer validation will all determine whether theoretical peak compute can be converted into billable tokens.
This week, AMD extended the competition from chips to racks. The company reached a 2GW Helios collaboration agreement with Anthropic, with deployment of the first 1GW scheduled to begin in the first half of 2027, and also brought Microsoft into its Helios, Venice CPU, networking, and software collaboration. MI450 and Helios shipments are scheduled to begin at the end of the third quarter of 2026 and accelerate in the fourth quarter and the first half of 2027.
The significance of this collaboration is greater for the server supply chain than for the market share of any single GPU. AMD must deliver GPUs, CPUs, networking, racks, and software simultaneously, expanding the supply chain from individual accelerators to complete systems. However, initial shipments are slightly later than some market expectations, while the ROCm ecosystem, mass-production yields, customer data-center construction, and actual procurement volumes still require quarter-by-quarter validation.
Google has also demonstrated that internally developed chips can generate external revenue. Google Cloud grew 82% in the second quarter, with backlog reaching $514 billion, and TPUs have begun to be sold externally. Demand is strong, but near-term capacity shortages have forced the company to procure third-party compute while accelerating its own infrastructure buildout, putting pressure on cloud margins and free cash flow.
Advanced-packaging orders have moved from long-term roadmaps into current operating data. BE Semiconductor Industries reported approximately €293 million of second-quarter orders, up 9% sequentially. Its hybrid-bonding customer count increased from 15 at the end of 2025 to 21, with applications spanning logic, memory, co-packaged optics, and consumer electronics. Third-quarter revenue guidance calls for sequential growth of 10%–15%, above prior market expectations.
Hybrid bonding is materializing first in logic, while HBM still faces a timing gap
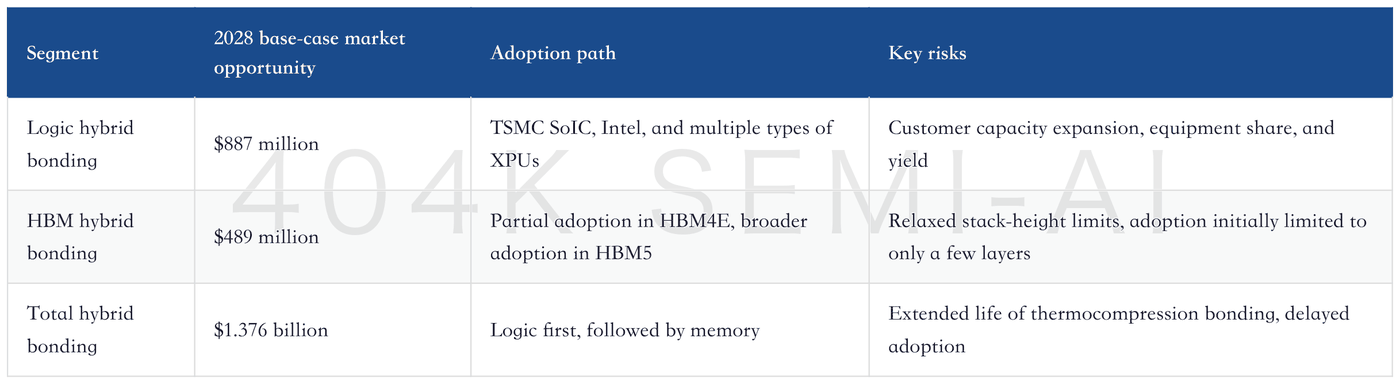
The adoption path for logic hybrid bonding is clearer. TSMC’s SoIC capacity is projected to increase from 10,000 wafers per month in 2025 to 85,000 wafers per month in 2028, driven by demand from AMD, Apple, Google, and Nvidia. HBM is affected by packaging-height limits, thermal management, and the availability of thermocompression bonding. If HBM4E remains predominantly 12-layer, large-scale adoption could be delayed until HBM5.
Long-term demand for wafer-fabrication equipment is substantial, but the model is highly sensitive to its assumptions. Under the base case, each additional 1GW of annual compute capacity requires approximately 46,000 wafers per month of fab capacity and approximately $7.5 billion to $8 billion of wafer-fabrication equipment investment. If 50GW of new annual capacity is established by 2030, cumulative equipment investment during 2027–2029 could exceed $700 billion.
These figures cannot be treated directly as orders. They depend on rack power consumption, die area, yield, CPU and memory configurations, equipment capital intensity, and the rate at which data centers enter operation. A better tracking approach is to monitor equipment-company orders, fab capital expenditure, monthly CoWoS capacity, HBM expansion, and customer prepayments, rather than relying solely on long-term GW plans.
Optical Communications, CPO, PCBs and High-Speed Interconnects
This week, optical communications produced evidence across demand, supply and profitability. Eoptolink guided for first-half net profit of RMB 7 billion to RMB 9 billion, implying second-quarter net profit of RMB 4.2 billion to RMB 6.2 billion. Improving supply and capacity expansion for 800G and 1.6T optical modules and optical chips jointly drove growth. In the second half of 2026, the revenue contribution from 1.6T and silicon-photonics products will also be key.
Nokia’s results provided additional evidence from the networking side. Second-quarter AI and cloud revenue increased 105% year on year, order intake reached EUR 2.8 billion, optical-networking revenue grew 20%, and IP-networking revenue rose 16%. The company expects approximately half of its AI and cloud orders to convert into revenue over the next 12 months. Network demand is no longer confined to equipment vendors’ long-term addressable-market projections.
However, co-packaged optics (CPO) will not replace pluggable optical modules linearly. Glass-bridge experts believe near-packaged optics may achieve commercial scale before CPO. CPO remains constrained by optical loss, coupling consistency, warpage, serviceability and packaging yield. Market reports estimate that CPO adoption may still be in the single digits in 2028, with more visible expansion only beginning in 2029; actual shipments must provide confirmation.
The current high-speed interconnect theme remains the upgrade to 800G, 1.6T and copper interconnects. Retimers and high-performance SerDes can extend the life of copper interconnects, while optical connectivity will initially penetrate the locations where bandwidth and distance constraints are most severe. Corning’s optical-communications capacity is nearly sold out, limiting the scope for second-quarter revenue to beat expectations; additional capacity and pricing in the third quarter will be more important validation points.
Shortages in PCBs and substrates are shifting from “volume” to “specifications.” As AI packages become larger, warpage, flatness and solder-joint reliability are becoming yield bottlenecks. CoWoS-L is planned to advance from a 3.3× reticle size to 5.5× and reach 9.5× in 2029, imposing higher requirements on high-rigidity ABF substrates, glass cores and fine-line circuitry.
Glass cores offer better flatness and dimensional stability over the long term, but through-hole yield, brittleness, customer qualification and mass-production infrastructure remain immature. More realistic profit opportunities lie in continued upgrades to organic substrates, increases in ABF layer counts and area, and persistently tight supply and demand for high-end fiberglass cloth and copper foil.
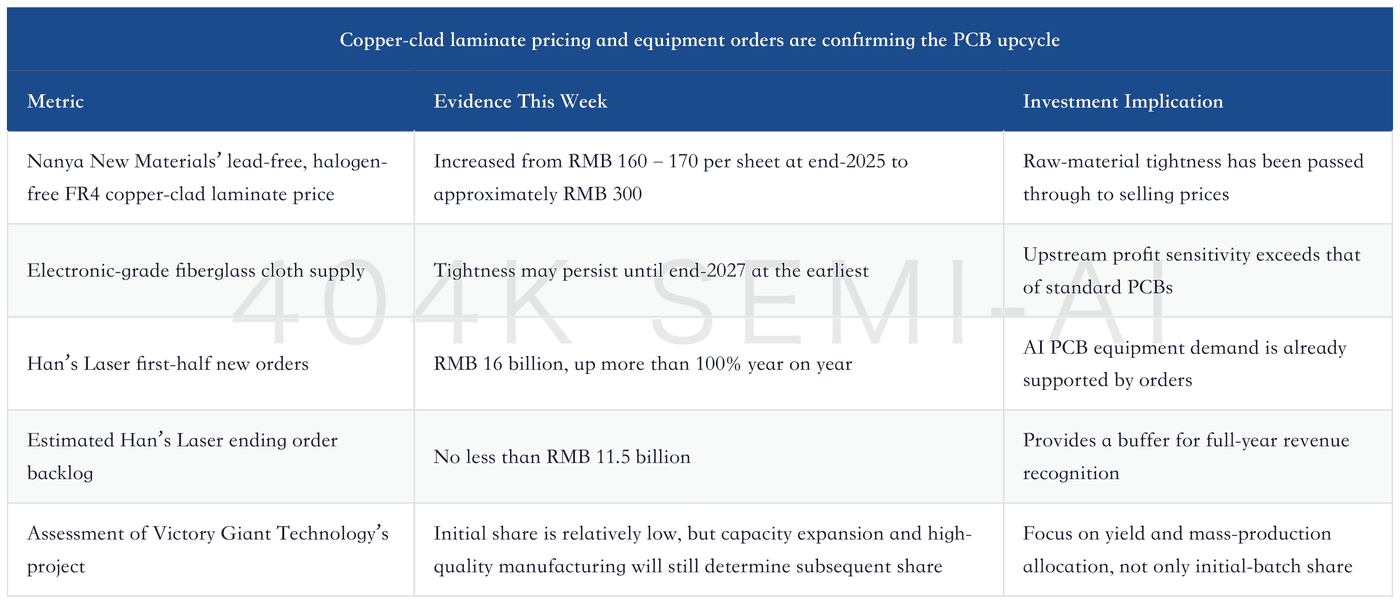
There is also a clear valuation divergence. Han’s Laser has very strong orders, but another report downgraded its rating after the earlier sharp share-price rally, arguing that visibility into PCB equipment orders over the next two years is already largely priced in. Improving fundamentals and overextended valuations can coexist. The focus should now be on order-to-revenue conversion, gross margin and the actual contribution from new AI businesses.
Data-Center Cooling, Power Supplies and Electricity
The most constrained data-center resource has shifted from land to time-to-power. The potential US power shortfall through 2028 is approximately 38GW, while grid-connection wait times exceed 5 years in some regions. Projects that can secure grid-connection rights, transformers, gas turbines, fuel cells or other on-site power sources in advance may be more valuable than campuses that have only land and plans.
Commercialization of powered-shell capacity has already produced long-term leases. Hut 8’s two 15-year leases at Beacon Point cover a combined 704MW, while the campus has total capacity of 1000MW. The transaction demonstrates that customers are willing to pay for power and infrastructure that can enter service more quickly, but valuations must account for construction, financing, tenant-credit and delay risks.
Grid-equipment orders provide more concrete upstream evidence. GE Vernova reported second-quarter Electrification sales of USD 3.637 billion and orders of USD 6.347 billion, with orders approximately 1.7× sales; backlog reached USD 44.6 billion, up 65% year on year. Data-center-related orders exceeded USD 5 billion in the first half, already surpassing full-year 2025.
Orders are expanding from transformers and switchgear into solid-state transformers, medium-voltage uninterruptible power supplies and 800V direct-current power delivery. Shipments of solid-state transformers to hyperscale cloud customers are scheduled to begin in the second half of 2026. The real indicators are not product announcements, but orders, deliveries, selling prices, capacity and after-sales service revenue.
Higher server power is also increasing power-semiconductor content per rack. Supply-chain reports estimate approximately USD 112/kW for B200, approximately USD 128/kW for Rubin and potentially USD 191/kW for Feynman. Power supplies, voltage-regulator modules and intermediate bus converters account for approximately 80% of the relevant value, but these forecasts still require confirmation from bills of materials and supplier revenue.
Power-generation equipment may be harder to scale rapidly than chips. Supply-chain reports indicate that large gas turbines require at least 5 years for delivery, with approximately 88–100GW of new global orders versus approximately 50–60GW of annual capacity at the leading manufacturers. Benefits will continue to extend to heat-recovery steam generators, cooling, installation, spare parts and maintenance, but projects without a confirmed operator, construction start date or power mix cannot be recognized as revenue prematurely.
Cooling did not produce equally strong standalone financial evidence this week, but it will upgrade in tandem with rack power. Supernodes, 800V direct current and higher power density will all increase the importance of liquid cooling, heat exchange and fluid control. Next week, orders for cold plates, coolant distribution units, pumps and valves, and data-hall water and power infrastructure should be reconciled against server shipments in the same table.
Robotics, Edge AI and Hardware Applications
Interest in robotics is already exceptionally high, but commercialization must still be assessed by application. At the World Artificial Intelligence Conference, the number of embodied-intelligence exhibitors reached 242, up 203% year on year; the number of products reached 208, up 247%; and more than 300 humanoid robots were demonstrated on site, up 100%. Growth in unit counts confirms rising investment, but does not establish reliability or returns.
Logistics handling and structured industrial environments are closest to commercialization, retail remains inefficient, and household applications are the furthest away. Combining vision-language-action models with world-action models has become the mainstream direction, allowing robots to predict future states before acting. The tradeoff is slower inference, while non-visual data such as touch and material properties remain clearly insufficient.
Industrial AI has already achieved quantifiable deployments. Deployment of new AI-assisted quality-inspection scenarios can be shortened to less than 1 month, while flexible-manufacturing models can be transferred across different products in as little as 8 hours. Poor equipment connectivity and insufficient interoperability across machines will instead drive the digitization of legacy production lines and upgrades to sensors and control systems.
Dexterous hands offer high value density but are also among the most difficult components to validate. Supply-chain reports estimate that dexterous hands account for more than 30% of total system bill-of-materials cost, while actuators and sensors together represent approximately 80% of hand cost. Tactile-sensor prices have declined, but their lifespan is approximately 1 million touches, still short of the approximately 5 million touches required for mass production.
The two visible paths for edge AI are glasses and industrial vision. A Meta partner disclosed that AI-glasses sales exceeded 7 million pairs in 2025, with prescription-lens penetration above 30%. This demonstrates that glasses have established a consumer entry point, but battery life, weight, always-on cameras, privacy regulation and competition could all reduce long-term sales and hardware gross margins.
Commercialization of industrial vision is more measured. Mitsubishi Electric and Sony Semiconductor Solutions established an AI vision-sensor joint venture with respective ownership stakes of 60% and 40%, with operations scheduled to begin in October 2026. The strategic direction is clear, but specific products, customers, orders and earnings contributions have not yet been disclosed, making this only a future validation point for now.
Apple’s AI server chip is also still in the validation stage. Media reports indicate that M2 Ultra is facing performance issues, but Apple has not confirmed this, and the supply chain has found no cancellation of related packaging capacity. Baltra is expected to enter small-scale mass production in the first half of 2027, while the second-generation AI ASIC is expected to enter mass production in 2028; external cloud-computing costs may still increase in the near term.
Space, Quantum Computing, and AI Software Applications
Asia’s space value chain now spans launch services, satellite manufacturing, space-grade materials and electronics, ground equipment, and downstream data applications. North Asia leads in industry depth and scale, but this week investors should focus on project milestones rather than substitute thematic baskets for analysis of company orders and cash flow.
Direct-to-device satellite connectivity is entering the testing phase. According to market reports, AST SpaceMobile has applied for a 30-day authorization to test direct-to-smartphone satellite broadband using ordinary smartphones in Texas and Maryland. Reports differ on the frequency bands and carrier resources involved, so regulatory filings must be confirmed before assessing coverage and capacity.
Quantum computing generated insufficient evidence of company orders, capacity, or profitability this week. Space-based data centers and quantum AI remain topics of conceptual discussion, but cooling, radiation, communications, launch costs, fault tolerance, and commercial customers still lack validation on a comparable basis. Investors should wait for equipment deliveries, customer contracts, or repeatable performance metrics before allocating capital.
AI software is moving from “can it be used?” to “who can monetize it?” ServiceNow reported second-quarter subscription revenue of $3.877 billion and cRPO of $13.2 billion. The company raised its full-year constant-currency subscription revenue growth guidance and set a target of more than $1.5 billion in AI annual contract value by the end of 2026. Workflow entry points and existing customer relationships are being converted into revenue.
SS&C;’s path is more focused on cost savings. The company has internally deployed more than 3,500 digital workers and 50 AI agents, generating approximately $200 million in annualized cost savings. This demonstrates that AI can improve margins first, before governance, automation, and industry-specific agents are sold to customers, although external platform revenue still depends on product integration and customer adoption.
Workday provides a counterexample. Its AI commercialization remains in the pilot phase, its core business growth is slowing, and compliance and governance requirements are extending deployment cycles. An enterprise software moat does not automatically translate into AI revenue; annual contract value will reflect AI only when agents enter production, generate usage, and drive renewals.
Security software faces a clear time lag. Enterprise AI security budgets have yet to reach a broad inflection point, with more pronounced changes expected no earlier than the fourth quarter of 2026 or the first half of 2027. The base-case estimate projects an AI security market of approximately $20 billion by 2031, but workloads must first move from sandboxes into production.
Divergences, Counterevidence, and What to Monitor Next Week
The first debate is whether model efficiency will reduce hardware demand. Kimi K3’s actual results support the thesis of “lower unit costs and higher aggregate demand,” but this is not a permanent law. If usage declines after the open-weight release, utilization falls following capacity expansion, or smaller models replace large models in mainstream tasks, the assessment of compute shortages will need to be revised downward.
The second debate is whether capital expenditure can translate into free cash flow. Google Cloud’s growth and backlog provide a positive answer, but the company’s 2027 capital expenditure forecast has risen to approximately $378 billion, while third-party compute, depreciation, and debt financing will pressure profits. AI-related corporate bond issuance continues to increase, and the term premium on long-term financing is also rising.
The third debate concerns the pace of technology adoption. The path for hybrid bonding in logic is relatively clear, but HBM hybrid bonding may still be delayed as 12-layer packaging, improved thermal dissipation, and thermocompression bonding extend the existing technology’s life. CPO is constrained by coupling, yield, and maintenance, while glass cores are constrained by through-hole yield, brittleness, and qualification. A technology roadmap can be correct without revenue materializing in the expected year.
The fourth debate is the gap between robotics demonstrations and real-world production. The number of trade-show demonstrations is growing rapidly, but continuous operation, exception recovery, tactile-sensor lifetime, and cross-task generalization remain inadequate. For household robots in particular, sales volumes cannot be inferred from a single demonstration. Investors should prioritize cycle time, failure rates, repeat purchases, and unit economics among logistics and industrial customers.
The fifth risk is the authenticity of order reports. Market rumors this week of a massive SpaceX order for GB300 servers were directly denied, and the reported value and rack count should not be included in forecasts. Orders not confirmed by the company, regulatory filings, or original contracts should be treated only as leads requiring verification, not as equivalent to formal backlog.
Next week’s validation checklist should follow the closed loop of “demand—supply—cash returns.”
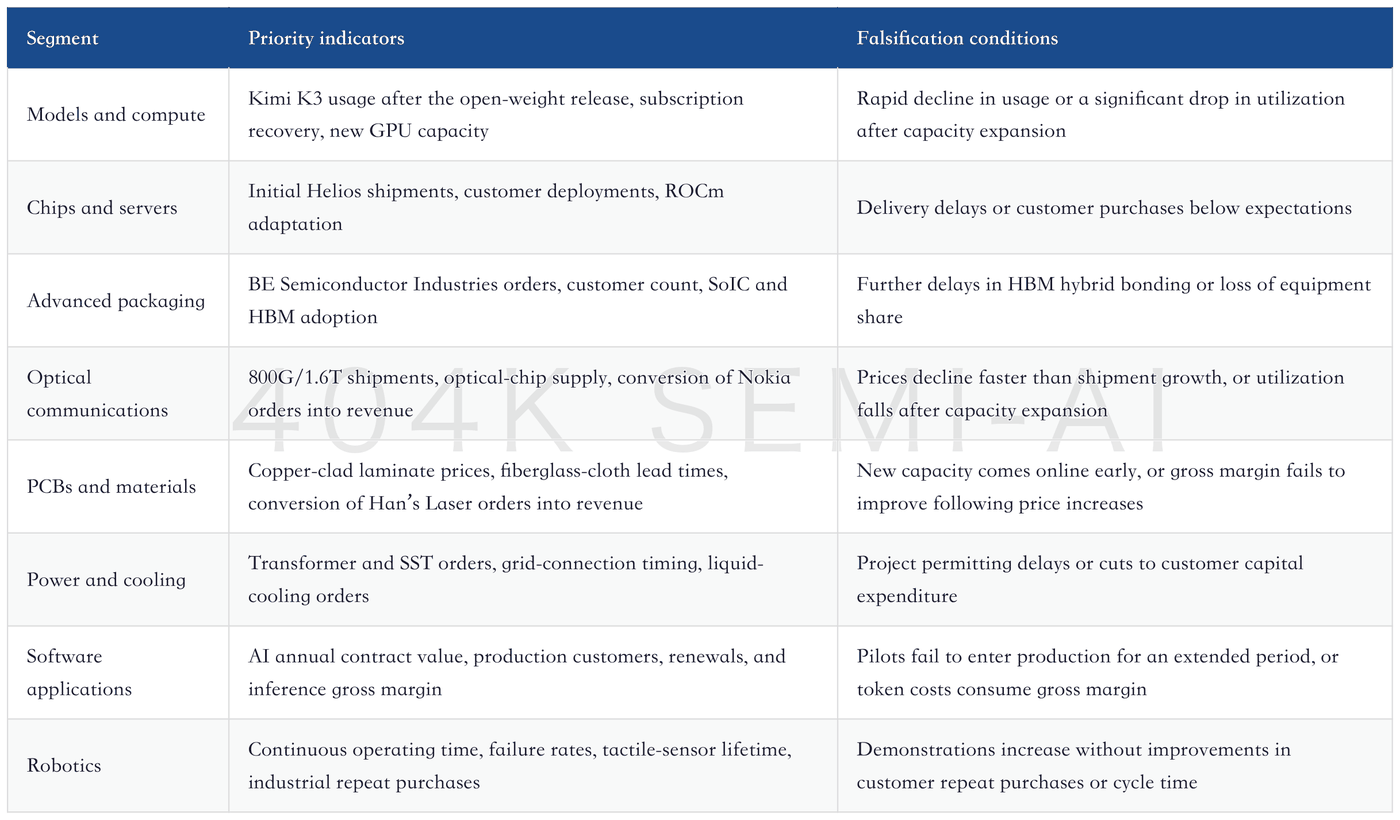
The more investable conclusion this week is that compute demand continues to spill over into systems and infrastructure. The conclusion requiring greater caution is that every long-term addressable market can already be recognized as revenue. Orders, capacity utilization, lead times, gross margin, and free cash flow remain the five most effective validation metrics.