
404K SEMI-AI 2026-07-18 M7 & CSP Weekly — Capex Reaccelerates, Compute Supply Remains Tight, and Application Monetization Enters Hard Validation
目录
TL;DR
Overall View This Week
Cloud Revenue and AI Capex
Data Centers, Compute Procurement, and Custom Silicon
Models, Software, and Application Monetization
Divergence Between the M7 and Neoclouds
Divergences, Disconfirming Evidence, and Next Week’s Watchlist
The most important development this week was that cloud providers continued to increase spending, while the market began assessing each investment against revenue, gross margin, and cash flow. Supply remains tight, and the real risk has shifted from “no demand for compute” to “investment moving too quickly and returns arriving too slowly.”
TL;DR
Microsoft most clearly illustrates this week’s central tension: Azure and Copilot demand remain strong, and Citi expects Azure constant-currency revenue growth of 42.2% in FY2027, but capex including leases is set to rise to $261.6 billion. Growth can absorb the investment, but gross margin and free cash flow will come under near-term pressure. The key question is whether Azure growth can continue to outpace capex growth.
There is still no clear evidence that AI is materially eroding Google’s search gateway. Its global search share rose to 91.3% in June, while Gemini web visits and mobile daily active users increased 341% and 295% YoY, respectively. At the same time, capex is rising rapidly, and free cash flow is expected to fall to $14.435 billion in 2027, indicating that product momentum and cash-flow pressure will intensify in parallel.
Meta continues to address “overbuilding” concerns with the sheer scale of its compute plans. Research reports cite a target of 14GW of compute capacity by 2027 and a planned 1GW data center in Canada; market reports also indicate that several GW-scale campuses are advancing concurrently. The key validation point for Meta is not how many data centers it builds, but whether the incremental capacity can translate into greater advertising efficiency, model API revenue, or high-priced external contracts that can be reclaimed when needed.
Server supply remains tight. Industry models project 70,000–80,000 GB200/GB300-equivalent racks in 2026, while component issues have delayed the VR200 by one to two months, with ramp-up now expected in 4Q26. Cloud providers may be able to purchase more compute, but they may not be able to deploy it on schedule or preserve unit economics.
Custom silicon is evolving from a cost-management tool into a cloud-competition tool. Google TPU, Amazon Trainium, Microsoft Maia, and Meta MTIA continue to scale, with advanced packaging, memory, and power emerging as common constraints. General-purpose GPUs still lead in software, utilization, and deployment speed; the cost advantages of custom silicon become easier to realize only when workloads are stable and sufficiently large.
Opportunities remain for neocloud providers, but total contract value alone is insufficient. CoreWeave, Nebius, and others are supplying capacity that hyperscalers cannot build quickly enough in-house. The metrics that matter are energized megawatts, customer commitment periods, GPU depreciation, financing costs, and renewals. High revenue density does not automatically translate into high shareholder returns.
Overall View This Week
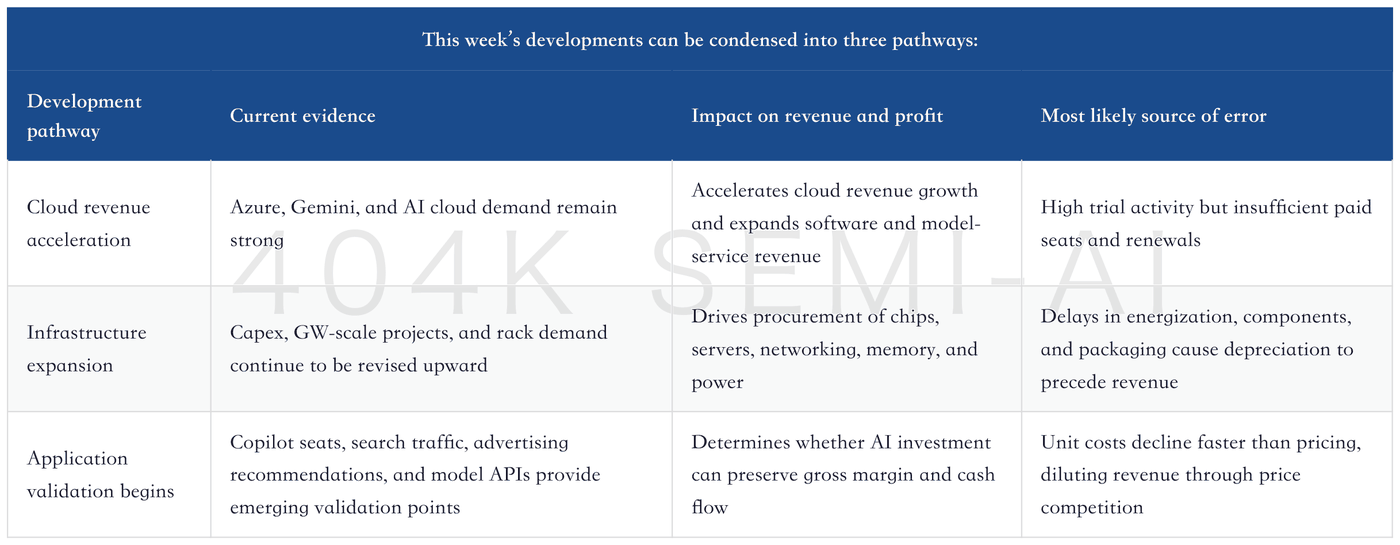
Cloud providers have not hit the brakes, but the investment thesis has shifted from “more capex is always better” to “how much revenue and cash flow does each $1 invested generate?” The common signal this week is that Microsoft, Google, and Meta are still increasing investment in compute, data centers, and power. This continues to support demand for upstream servers, advanced packaging, and networking. Unlike previous cycles, however, investors are no longer rewarding scale alone. They are asking three questions: Can cloud revenue accelerate in parallel? Can AI applications generate repeatable paid demand? When will free cash flow bottom?
Microsoft is closest to establishing a measurable “investment–revenue–profit” loop. Azure growth expectations are rising, Copilot seats are expanding, and data-center capacity is increasing. The cost is a sharp increase in FY2027 capex and a gross-margin outlook below consensus. Google’s gateway traffic and search share remain stable, and Gemini is growing rapidly, but higher capex will push free cash flow lower. Meta has the most aggressive compute plan and the most diverse commercialization pathways: advertising recommendations, frontier models, model APIs, and external compute sales could all absorb incremental supply. Any one of these falling short would amplify depreciation and fixed-cost pressure.
The supply constraint is shifting from “are GPUs available?” to “can the entire system be powered up and operated on schedule?” VR200 delays, rising memory costs, advanced-packaging expansion, grid connections, and cross-campus network latency could all create a timing gap between reported capex and billable compute capacity. For cloud providers, signing procurement contracts does not mean revenue is generated immediately. For the supply chain, abundant orders do not guarantee higher margins, as delays, expediting costs, and product mix can all alter profit allocation.
The strongest positive evidence this week is that demand remains intact; the most important counterpoint is that unit economics have not yet been fully validated. Microsoft channel checks indicate that Copilot renewals and adoption are improving, but enterprise-wide deployment remains unrealistic. Google has not materially lost search share, but AI investment is widening the gap between capex and free cash flow. Meta has advertising cash flow to fund investment, but it still needs to prove that 14GW-scale compute capacity will not become an underutilized asset. In the next phase, revenue growth, gross margin, billable utilization, and energized capacity will matter more than project announcements.
Cloud Revenue and AI Capex
Microsoft’s growth outlook is strong enough to explain why investment must continue, but not enough to eliminate margin concerns. Citi expects Microsoft’s Azure constant-currency revenue to grow 39.7% in 4Q FY2026, with Microsoft 365 Copilot reaching 28 million seats.
By FY2027, Azure constant-currency growth is expected to rise to 42.2%, while Copilot seats reach 65 million. The model also projects Microsoft’s total revenue to grow 18.2% to $389.577 billion.
The capex trajectory is steeper. Citi raised its FY2027 forecast for Microsoft’s capex including leases to $261.6 billion, 12.8% above consensus.
Microsoft’s gross margin is forecast at 64.3%, below the 67.6% consensus, while its operating margin is forecast at 45.4%, also below the 47.2% consensus. The money will first become data centers, servers, and depreciation; revenue and profit will follow later. Investors should look beyond whether Azure exceeds guidance and assess whether Azure’s growth premium to the market widens after each capex increase.
The “investment–return” pressures facing major cloud providers have already begun to diverge.
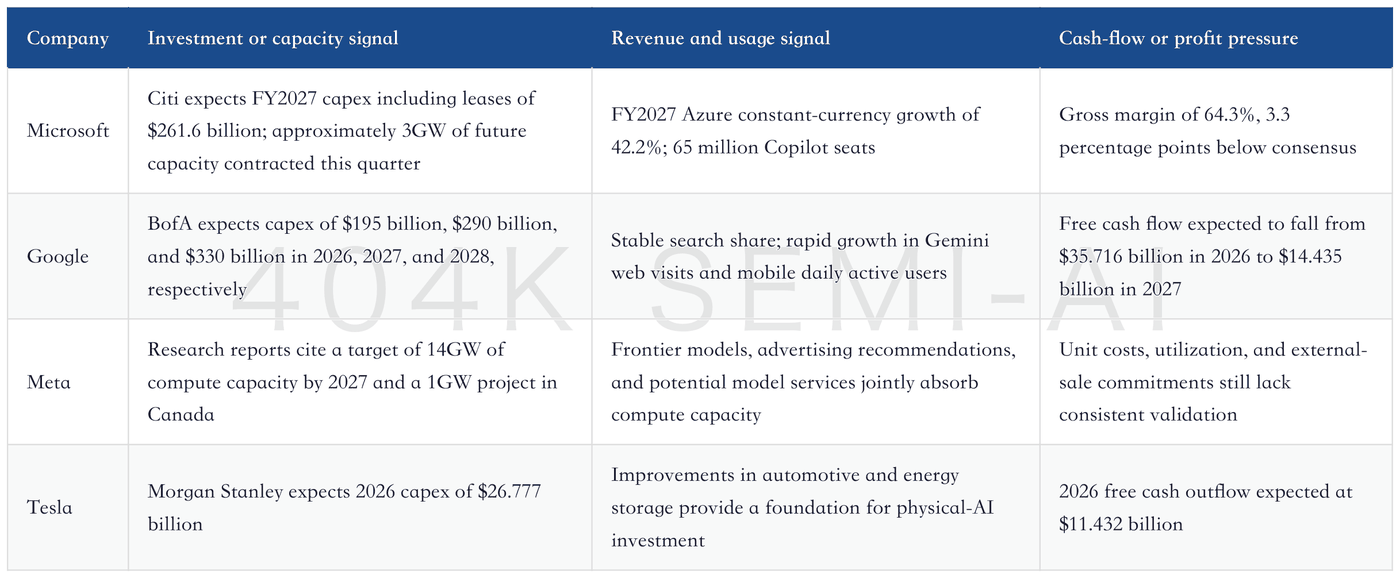
The good news for Google is that its gateway has not materially weakened; the bad news is that maintaining its lead requires more cash investment. In June, Google’s average global daily web visits increased 4% YoY to 2.8 billion, while global mobile daily active users rose 12% YoY to 2.2 billion.
Gemini web visits increased 341% YoY, while mobile daily active users rose 295% YoY to 118 million. Product growth is rapid, but paid conversion and advertising monetization still require further validation.
Google’s global search share increased 79 basis points MoM and 171 basis points YoY to 91.3%, while its US search share rose 86 basis points MoM to 86.7%. These figures indicate that generative-AI growth has not yet translated into a collapse in Google search traffic.
Stable traffic, however, does not mean returns on capital have been confirmed. BofA’s model expects Google’s 2027 revenue to grow 23.1%, but capex to rise to $290 billion and free cash flow to fall to $14.435 billion. The key variable to monitor is the combination of Cloud revenue, search advertising load, and capex. If capacity constraints limit Cloud revenue while search requires higher inference costs to defend market share, Google could simultaneously face “excellent demand” and “very weak cash flow.” The return pathway will become genuinely clearer only when new capacity comes online, Cloud revenue accelerates, and cost per query declines at the same time.
The debate over Meta’s capex remains in its earliest stage. A JPMorgan research report states that Meta plans to increase compute capacity to 14GW by 2027 and build a 1GW data center in Canada. This scale directly challenges the simplistic narrative that “Meta has already overbuilt and is preparing to cut procurement.” Market reports also suggest that Meta is advancing several GW-scale campuses concurrently, but these projects use inconsistent cost definitions, commissioning schedules, and compute-allocation assumptions, so they cannot be translated directly into revenue.
Meta has one more internal monetization pathway than traditional cloud providers: its advertising recommendation systems can absorb substantial training and inference capacity, with returns captured through impressions, conversion rates, and advertising prices. It may also sell model APIs or temporarily idle compute capacity to external customers. The problem is that these businesses have different revenue quality. Advertising returns depend on user engagement and ad load; model APIs depend on developer adoption; and external compute sales depend on whether contracts allow capacity to be reclaimed when internal demand recovers. In next week’s updates and subsequent earnings reports, the most important issue will be how management allocates capacity among internal use, external sales, and frontier-model training—not merely the headline GW target.
Data Centers, Compute Procurement, and Custom Silicon
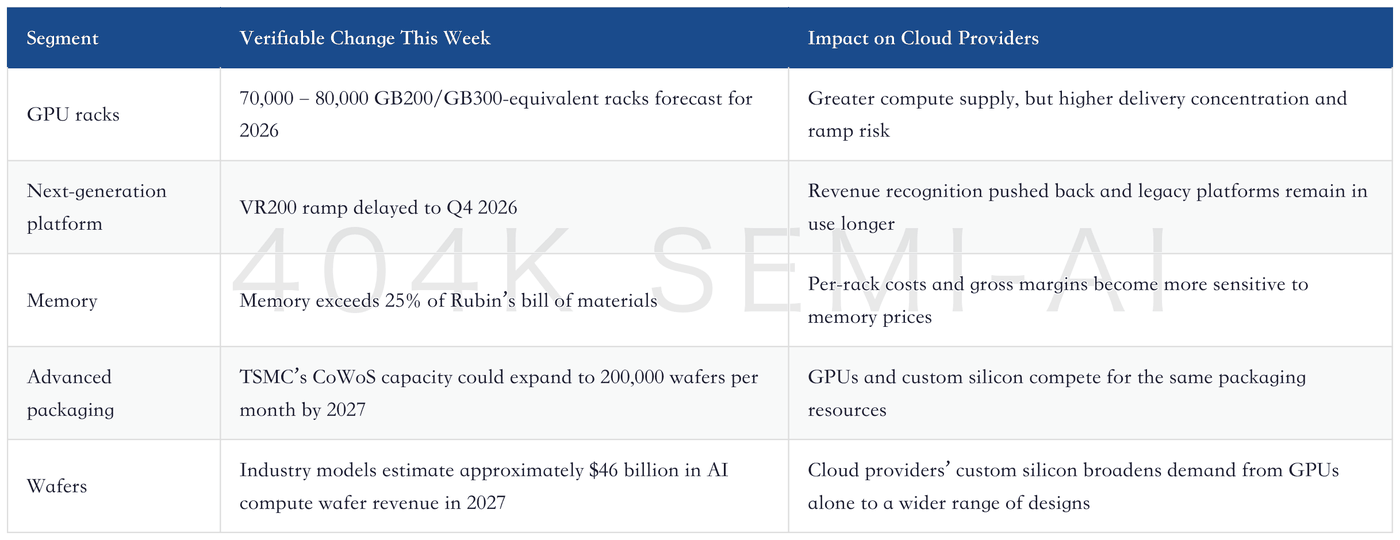
System delivery remains a binding constraint on cloud provider expansion. Industry models forecast 70,000–80,000 GB200/GB300-equivalent racks in 2026, up from approximately 29,000 in 2025.
VR200 has been delayed by one to two months due to issues with components including the midplane, pushing the ramp to Q4 2026. A single VR200 NVL72 rack will cost hyperscalers approximately $7.8 million, with memory accounting for more than 25% of Rubin’s bill of materials. Larger procurement budgets cannot eliminate component delays or rising costs.
Next-generation racks expand capital expenditure from “buying GPUs” to upgrading the entire system.
The rack demand mix shows that purchasing power remains concentrated among a small number of cloud providers. Industry models provide buyer-share estimates for 2026 demand for Nvidia GB200/GB300 servers.
A small number of buyers continue to determine the allocation of most rack supply.
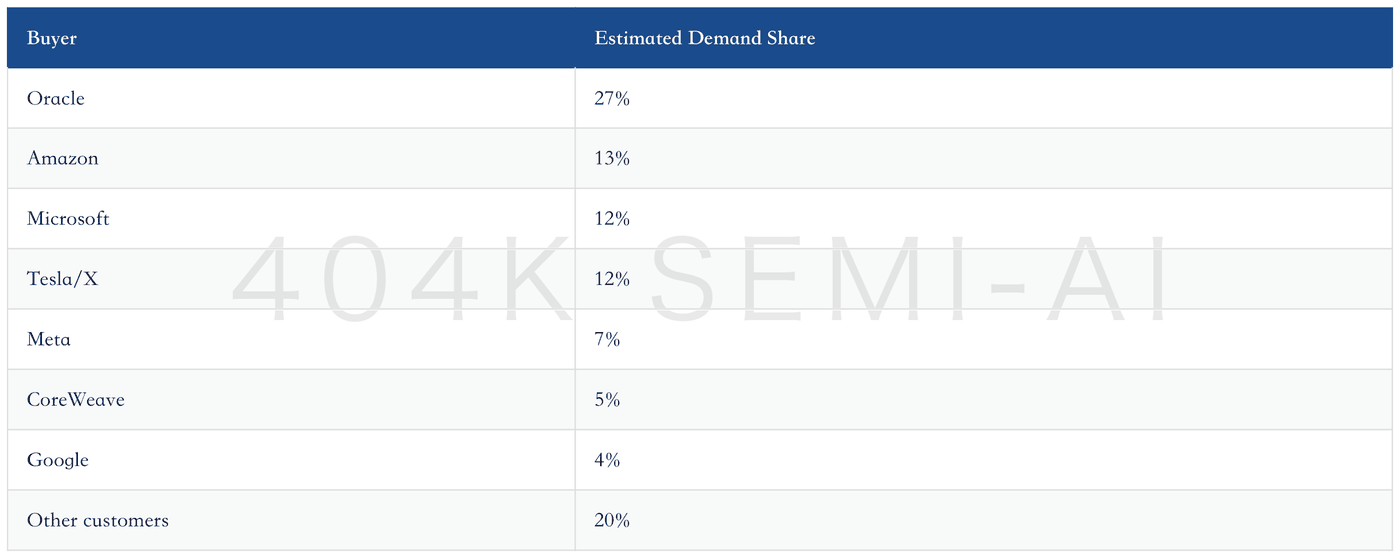
These figures are not disclosed orders, but they illustrate two points: traditional hyperscalers still determine the allocation of most supply, while non-M7 buyers such as Oracle and CoreWeave now command enough share to influence delivery and pricing.
The value of custom silicon lies not only in lowering procurement costs, but also in more tightly integrating cloud services, models, and hardware. The 2027 wafer-demand model includes Google TPU, Amazon Trainium, Microsoft Maia, and Meta MTIA. Custom silicon can optimize performance per watt for stable workloads and reduce reliance on a single GPU roadmap. The trade-off is that the cloud provider must assume responsibility for design, software, packaging, networking, and customer migration. If utilization is insufficient, cheaper chips can still become expensive idle assets.
The contest between general-purpose GPUs and custom silicon will ultimately be determined by effective throughput rather than peak specifications. Nvidia retains advantages in mature software, system availability, and deployment speed, making its GPUs better suited to rapidly changing workloads with many customers and frequent model iteration. Google TPU and Amazon Trainium are better suited to sufficiently large internal workloads with relatively stable tasks. Industry estimates suggest that custom silicon can amortize infrastructure costs more effectively when workloads are predictable; when models and software change rapidly, GPUs can more readily offset higher procurement costs through better utilization.
Emerging cloud providers are filling a gap in deployment speed, not operating in a permanently insulated standalone market. CoreWeave, Nebius, and others can rapidly deliver energized capacity, GPUs, and software stacks to customers, allowing them to secure large contracts when hyperscaler supply is constrained. Their risks are concentrated in the same area: customer commitments may be shorter than data-center leases, while GPU depreciation periods may extend beyond premium-priced rental cycles. Assessing order quality requires breaking total contract value into energized megawatts, billable utilization, customer contract duration, financing costs, and renewal pricing.
Nvidia’s proposal to provide credit support to emerging cloud providers and share in cloud-service revenue further blurs the boundary between chip supplier and cloud platform. One research report argues that this could generate high-margin recurring revenue beyond hardware sales, while explicitly warning that the costs and risks of credit support will not be fully reflected in the current-period income statement. For Nvidia, the best-case outcome is to use financing and ecosystem lock-in to secure incremental GPU demand and then share in service revenue; the worst case is insufficient downstream utilization that pushes credit risk back upstream.
Power is becoming a slower delivery constraint than chips. Google’s power strategy disclosed this week spans solar, energy storage, demand response, natural gas, nuclear, and geothermal. The first two phases of the latest Steel River project include 1.6 GW of solar capacity and 1.9 GWh of storage, with the full project planned to reach 2.5 GW of solar and 2.9 GWh of storage by 2029.
The Meitner project in Texas will co-locate more than 1 GW of wind, solar, and storage capacity with data centers. Steel River is a virtual power purchase agreement, so the electricity will not be delivered directly to Google’s data centers; Meitner will also require on-site natural gas to ensure reliable supply. Both arrangements show that incremental compute capacity must be planned alongside generation, storage, grid interconnection, and backup power.
Models, Software, and Application Monetization
Microsoft offers the most comprehensive evidence of application monetization this week, but Copilot is still progressing from departmental deployment toward enterprise-wide renewal. Channel checks indicate continued expansion in Copilot seats, improving renewal rates, and declining discounts. At the same time, company-wide deployment remains unrealistic, with large customers more commonly rolling it out by department. Citi forecasts eight million net new Copilot seats in Q4 FY2026, up from five million in the previous quarter, and has raised its quarter-end seat forecast to 28 million.
The business implications for Microsoft are straightforward. Azure sells compute; Microsoft 365 Copilot sells per-user software; and Fabric, Power BI, and security products broaden customer usage. If customers move from trials to renewals, Microsoft can benefit from both higher cloud consumption and higher software revenue per customer. If customers purchase only a limited number of seats while capital expenditure is committed in advance for full-stack demand, gross-margin pressure will emerge first. Key metrics to watch are paid Copilot seats, renewal rates, the deployment ratio per customer, and committed Azure consumption—not merely the number of product launches.
