
404K SEMI-AI 2026-07-17 M7 and CSP Weekly — Capex Reaccelerates as Return Validation Reaches an Inflection Point
目录
TL;DR
Overall Assessment This Week
Cloud Revenue and AI Capex
Data Centers, Compute Procurement, and Custom Silicon
Models, Software, and Application Monetization
Divergence Between the M7 and New Cloud Providers
Divergences, Disconfirming Evidence, and What to Track Next Week
The key question this week is not whether AI investment will continue, but whether compute capacity, revenue, and cash flow can materialize at the same pace.
TL;DR
Hyperscalers are still accelerating expansion, with no capex inflection point yet in sight. Citi estimates Microsoft’s FY2027 capex including leases at approximately $261.6 billion, well above the market consensus of roughly $232.0 billion, while forecasting Azure constant-currency growth of 42.2%, versus the market’s approximately 40% estimate. Meta is reportedly planning to raise its 2027 compute capacity to 14GW and add a new 1GW project in Canada. The demand question has shifted from “will they keep buying?” to “can power, data centers, and packaging be delivered on schedule?”
AI infrastructure constraints are broadening from GPU shortages to power, memory, networking, advanced packaging, and system-level integration. Microsoft signed approximately 3GW of future capacity in Q2 2026, including roughly 2.7GW in West Texas. Meanwhile, a 90MW UK project with Microsoft as the anchor tenant is seeking alternative power due to grid-connection delays. Supply-chain checks also suggest that next-generation racks could be delayed by one to two months because of midplane PCB issues, underscoring that having chips does not necessarily mean having deployable compute capacity.
GPUs and in-house chips will coexist over the long term; the real objective of custom silicon is to lower unit inference costs, not immediately replace Nvidia. Nvidia channel feedback continues to point to strong demand, memory shortages lasting several years, and an emerging procurement model in which neoclouds raise financing to acquire compute capacity. Meanwhile, Meta is advancing custom accelerators and CPUs, while Google and Amazon continue expanding their specialized silicon portfolios. Procurement will evolve from GPU-only reliance toward joint optimization across GPUs, specialized chips, networking, and software.
Monetization is beginning to diverge: Microsoft’s enterprise distribution is closest to closing the revenue loop, while Google’s search and advertising foundation remains solid, but neither has fully demonstrated returns. Microsoft’s quarterly channel survey indicates improving Copilot adoption and Azure consumption, although organization-wide deployments remain rare. Google’s global search share rose year over year to 91.3% in June, while Gemini’s web traffic and mobile active users grew rapidly; however, its US mobile search share still declined 123 basis points year over year. User growth is now evident. The next critical question is whether it can convert into high-margin revenue.
Divergence within the M7 will be determined by financing capacity and existing cash flows, not absolute capex levels. Microsoft and Google have deeper cloud and advertising cash-flow buffers, while Meta is using advertising cash flow to acquire compute scale. Tesla, by contrast, faces pressure to demonstrate Robotaxi and Optimus progress quickly after doubling capex and turning free cash flow negative. Neoclouds may also rely on vendor financing and revenue-sharing arrangements. The same AI demand has entirely different balance-sheet implications across companies.
The most important task next week is not finding another larger capex figure, but checking six delivery indicators. In order: Azure growth and guidance, Copilot net additions and renewals, Google search ad load, data-center energization timelines, next-generation rack delivery cadence, and custom-silicon production ramp. If capex estimates continue rising without corresponding improvement in these indicators, the market will shift from rewarding investment scale to scrutinizing free cash flow and return on investment.
Overall Assessment This Week
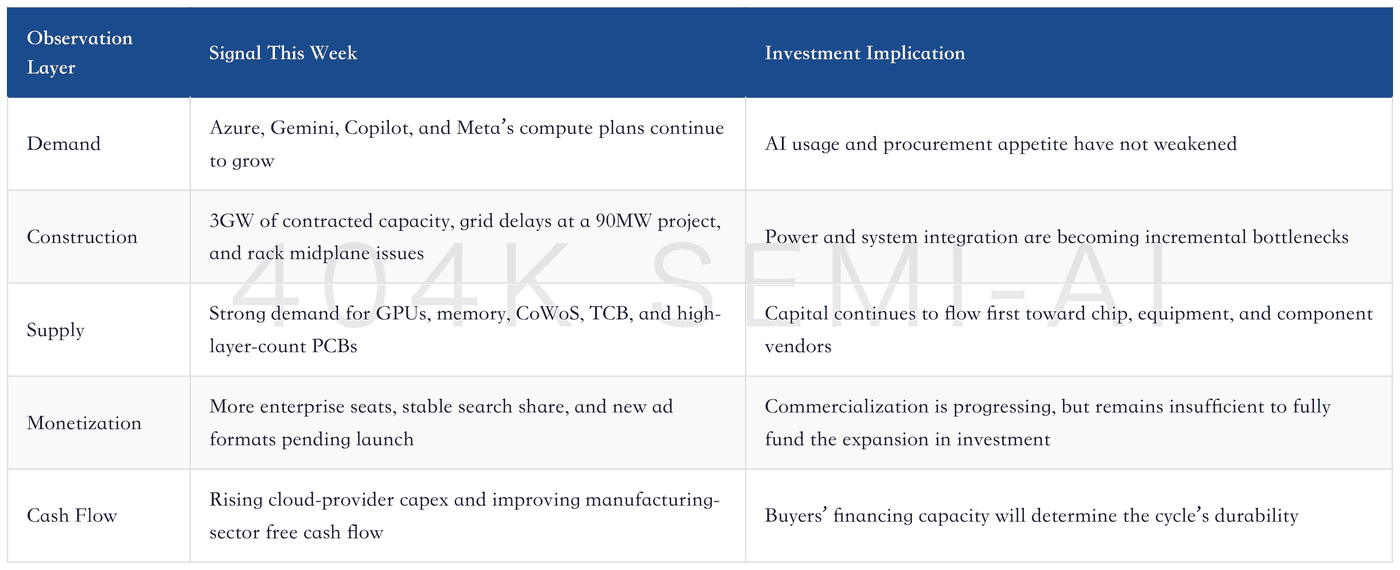
The clearest conclusion this week is that AI infrastructure remains in an expansion phase, but the valuation framework has shifted from “the more investment, the better” to “can the investment generate measurable returns?” Supply-chain signals remain strong. Feedback from Nvidia-related roadshows indicates that the company could still achieve 95% year-over-year growth in the quarter immediately preceding a new product cycle, while memory shortages may persist for several years. Goldman Sachs also raised its 2026–2028 capex assumptions for US cloud providers by 8%, 27%, and 25%, respectively. These data do not support a near-term demand peak.
The real change is in the evaluation criteria. Previously, the market only needed confirmation that cloud providers were willing to buy GPUs. It must now verify four additional factors: whether data centers can be energized, whether complete systems can be delivered on schedule, whether models can generate revenue, and whether operating cash flow can fund incremental investment. If any link breaks, capex can shift from a growth signal to a source of margin and cash-flow pressure. Microsoft is expected to maintain approximately 42% Azure growth in FY2027, but its gross margin is forecast to decline from 67.7% in FY2026 to 64.3%, while its free-cash-flow yield is projected to fall to 0.8%. This illustrates how accelerating revenue and cash-flow pressure can occur simultaneously.
The M7 and cloud providers should be assessed using three “clocks.” The first is the demand clock, driven by cloud revenue, model usage, enterprise seats, and advertising monetization. The second is the construction clock, determined by power, land, GPUs, memory, networking, packaging, and racks. The third is the return clock, determined by gross margins, free cash flow, and financing costs. This week’s readings are: demand continues to rise, construction is lagging slightly, and returns are beginning to diverge.
Conclusion: The AI investment cycle remains on an upward trajectory, but delivery speeds across different parts of the value chain are diverging.
Tesla provides a highly instructive boundary case. Bank of America estimates its 2026 capex at approximately $26.8 billion. With capex doubling and free cash flow turning negative, the market is no longer focused solely on factory and GPU counts; it is demanding evidence of commercialization from Robotaxi operations and the Optimus procurement ramp. Cumulative FSD mileage has surpassed 10 billion miles, while Optimus suppliers have reportedly been asked to increase weekly capacity to approximately 1,000 units by September and 2,000–2,500 units by year-end. However, these operating signals must still translate into revenue and profit. The same applies to every M7 company: capex demonstrates management confidence, but cannot by itself prove shareholder returns.
Cloud Revenue and AI Capex
Microsoft is this week’s most complete example of “high investment, high growth, and limited free-cash-flow elasticity.” Citi forecasts FY2027 revenue of $389.577 billion, EPS of $19.45, and Azure constant-currency growth of 42.2%. Azure guidance for the next quarter could be 40%–41%, while M365 Copilot net additions are expected to reach approximately 8 million seats in the fiscal fourth quarter, up from 5 million in the prior quarter. Against this, FY2027 capex including capital leases is estimated at approximately $261.6 billion, nearly $30 billion above market expectations. The key question is not which figure is larger, but whether Azure and Copilot can continue accelerating as capacity comes online, offsetting pressure on gross margins from depreciation and AI compute costs.
Microsoft’s channel evidence is positive but not noise-free. A sample of 27 resellers indicates that Azure AI Foundry, AI services, and security remain the primary growth drivers. Partners view Azure committed consumption as broadly stable, while Copilot renewal feedback is also improving. However, another group of partners reported that the largest Copilot deployment involved approximately 25,000 seats at a customer with roughly 30,000 employees, and genuinely organization-wide rollouts remain unrealistic. Large Azure migrations and megadeals are not widespread. In other words, enterprise customers have moved from trials into production, but a substantial gap remains between “pilot-to-renewal conversion” and “organization-wide penetration.”
Meta’s variables are more concentrated around scale and cost. Hardware-industry tracking indicates that Meta is reportedly planning to raise its 2027 compute capacity to 14GW and build a 1GW data center in Canada. Market materials this week also cited plans to expand the Hyperion project in Louisiana to 5GW. Capacity of this magnitude implies that Meta is preparing sustained compute resources not only for training frontier models, but also for recommendations, advertising, content generation, and agentic inference. Its advantage is that the advertising business can provide cash flow; the risk is that faster construction places greater demands on power, networking, custom silicon, and depreciation. Over the next two quarters, higher advertising conversion, increased user time spent, or lower unit inference costs must be evaluated alongside capex.
Google’s capex has an important buffer: its search and advertising foundation has not fallen off a cliff. Bank of America data show that Google’s average daily global web visits rose 4% year over year to 2.8 billion in June, while its global search share increased 171 basis points to 91.3%. In the US, its overall search share edged up year over year to 86.7%. This means Google can fund investment in Gemini, cloud computing, and custom silicon through existing cash flows rather than relying entirely on external financing. However, the risk is equally specific: its US mobile search share declined 123 basis points year over year to 92.8%, indicating competitive pressure at its most important traffic gateway. If AI search increases usage frequency and ad load, capex could convert into incremental revenue. If users migrate faster than new ad formats are launched, margins will come under pressure first.
The industry implications of capex have also broadened from GPUs to advanced packaging and back-end equipment. In its ASMPT report, Goldman Sachs raised its 2026–2028 capex forecasts for US cloud providers by 8%, 27%, and 25%, respectively, and for Chinese cloud providers by 37%, 44%, and 55%. It also raised its implied AI-server chip shipment forecasts by 14%, 22%, and 14%, respectively. ASMPT received a repeat order from a global integrated device manufacturer for eight chip-to-wafer thermocompression bonding systems, demonstrating that cloud-provider budgets are flowing downstream through GPUs, packaging, assembly, and testing. Whether capex is being realized should not be assessed solely through cloud-provider financial statements; it can also be cross-checked against equipment orders and capacity utilization.
Data Centers, Compute Procurement, and Custom Silicon
The primary data-center constraint is shifting from chips to complete systems that can be powered, connected, and operated. Microsoft contracted approximately 3 GW of future capacity in Q2 2026, including a roughly 2.7 GW project with Chevron in West Texas estimated to cost $8–10 billion; its Fairwater data center in Wisconsin was completed ahead of schedule and is now operational. This positive example shows that securing power and construction partners early can convert capital expenditure into Azure revenue more quickly. By contrast, a planned 90 MW, £2 billion data center in Essex, UK, where Microsoft is the anchor tenant, is considering on-site generation because the grid cannot provide its scheduled connection by 2027. Viewed together, planned GW capacity is not usable compute; the energization date marks the beginning of revenue generation.
The second constraint is rack-level coordination. Server-industry materials estimate that approximately 70,000–80,000 GB200 and GB300 racks will ship in 2026. However, next-generation VR200 racks could be delayed by one to two months from the original schedule due to issues with components such as midplane printed circuit boards, pushing the production ramp into Q4 2026. A delay in a single component affects system manufacturers, cloud deployment timelines, and GPU revenue recognition simultaneously. AI compute wafer consumption is estimated to reach as much as $46 billion in 2027, indicating that demand remains strong, but supply-chain execution will increasingly depend on the synchronized maturity of printed circuit boards, connectors, optical modules, memory, power systems, and liquid cooling.
The third constraint is memory and networking. Feedback from Nvidia roadshows suggests that memory shortages could persist for several years, with customers using lower-memory configurations to keep systems operational. Compute procurement therefore cannot be assessed solely by GPU count; high-bandwidth memory, network bandwidth, and rack power must also be considered. If GPUs arrive before memory or networking infrastructure, cloud providers incur depreciation without being able to deliver a complete service. If system configurations must be downgraded, sellable tokens per GPU will also fall below design capacity. This is the most frequently overlooked timing gap between capital-expenditure scale and actual cloud revenue.
The value of custom silicon lies in improving the long-term cost curve, not in signaling the end of the GPU cycle. Server-industry materials indicate that cloud service providers are planning additional proprietary-chip programs. Market tracking on Meta this week noted that the company is expanding its custom accelerator and CPU partnerships, with TSMC handling manufacturing, Arm providing the CPU architecture, and partners including Broadcom participating in high-speed silicon. Google and Amazon already use proprietary chips for internal training and inference workloads. Custom silicon is suited to stable, scalable, and predictable workloads, while GPUs will continue to handle frontier training, rapid iteration, and general-purpose compute. The most rational procurement mix is not a binary choice: GPUs provide flexibility, custom silicon lowers unit costs, and networking and software integrate both into marketable services.
New cloud providers are also incorporating financing structures into procurement decisions. Nvidia channel feedback suggests that some new cloud providers may receive vendor financing and exchange a share of future revenue for compute capacity. If compute remains scarce, this model can rapidly expand the ecosystem and potentially generate high-margin recurring revenue for upstream suppliers. However, it also embeds credit risk and customer profitability into the supply chain. Traditional M7 procurement is primarily supported by internal cash flow and balance sheets; for new cloud providers, order quality must also be assessed based on contract duration, end customers, financing costs, and secured power. Identical GPU orders can therefore carry very different risk implications.
Models, Software, and Application Monetization
Microsoft is developing the closest approximation to a closed-loop enterprise revenue model, with cloud resources, developer platforms, productivity seats, and security products reinforcing one another. Channel surveys indicate that Copilot Studio is typically deployed alongside Microsoft 365 Copilot, while Fabric and Power BI also drive Azure usage. Some partners have observed higher renewal rates and lower discounts following trials, suggesting that customers are no longer paying solely for the “AI narrative” but are retaining budgets for production use cases. Citi expects approximately 8 million net new Copilot seats in the fiscal fourth quarter and believes Azure can sustain roughly 42% growth in FY2027, creating a positive cycle in which applications drive cloud consumption and cloud capacity supports application expansion.
However, this closed loop is not yet fully established. Some surveyed customers still believe E5 has not delivered its full value, while E7 transactions require substantial discounts to accelerate adoption. Enterprise-wide Copilot deployments remain rare, with many projects limited to individual departments. For Microsoft, the key issue is not how many agents it has announced, but three operating metrics: whether paid seats continue to increase on a net basis, whether renewal discounts continue to decline, and whether Azure consumption generated by Copilot exceeds inference costs. If all three improve together, revenue growth will absorb the decline in AI gross margins. If seat growth depends on promotions while cloud costs continue to rise, the income statement will expose the problem first.
Google’s models are growing faster, but monetization primarily depends on search, advertising, and cloud. In June, Gemini’s global web traffic increased 341% year over year, while mobile daily active users rose 295% to 118 million. Claude’s web traffic increased 736% year over year, with mobile daily active users rising 1,206% to 18 million. These high growth rates show that users are migrating toward multiple model interfaces, but their absolute scale remains far below Google Search. Google has approximately 2.2 billion global mobile daily active users and retains more than 91% of the global search market. Gemini’s strategic value therefore extends beyond subscription revenue: it helps defend the search gateway, increase query frequency, expand agentic tasks, and create new advertising formats.
An easily overlooked divergence remains: more AI-generated answers do not necessarily mean weaker search advertising, nor do they necessarily mean higher advertising revenue. If AI Overviews and agents make users more efficient at completing tasks, search usage and commercial intent could expand. If answer pages reduce clicks, ad load, and merchant bidding, monetization could instead lag. BofA believes Google’s description of search entering an “expansionary moment” could produce higher usage, stronger understanding of commercial intent, and new advertising formats, but the year-over-year decline in US mobile-search share remains counterevidence. The next stage should be assessed through query growth, ad load, cost per query, and traffic-acquisition costs—not model rankings alone.
Meta’s model returns are reflected more in advertising systems and content efficiency than in standalone model sales. Its large-scale compute buildout and custom-silicon initiatives are primarily intended to reduce the unit costs of recommendations, ad generation, creator tools, and agents. If its models improve advertising conversion and user engagement, compute investment can scale rapidly through the existing advertising network. If user growth does not translate into higher ad pricing or conversion rates, 5 GW-scale projects will accelerate depreciation more quickly. Meta differs from Microsoft in that the former monetizes indirectly through advertising cash flow, while the latter charges directly through seats and cloud consumption. Their evaluation metrics should not be conflated.
Tesla represents the more challenging path of investing simultaneously in software and physical assets. Cumulative FSD mileage has exceeded 10 billion miles, and both Robotaxi and Optimus could create enormous potential markets, but vehicles, factories, robots, and training clusters all require concurrent investment. Suppliers being asked to increase weekly Optimus capacity is a signal of industrialization, but not revenue recognition. Capital expenditure will only shift from a long-dated option to estimable cash flow once Tesla begins regularly disclosing paid Robotaxi miles, utilization per vehicle, accident rates, productive robot hours, and unit costs.
Divergence Between the M7 and New Cloud Providers
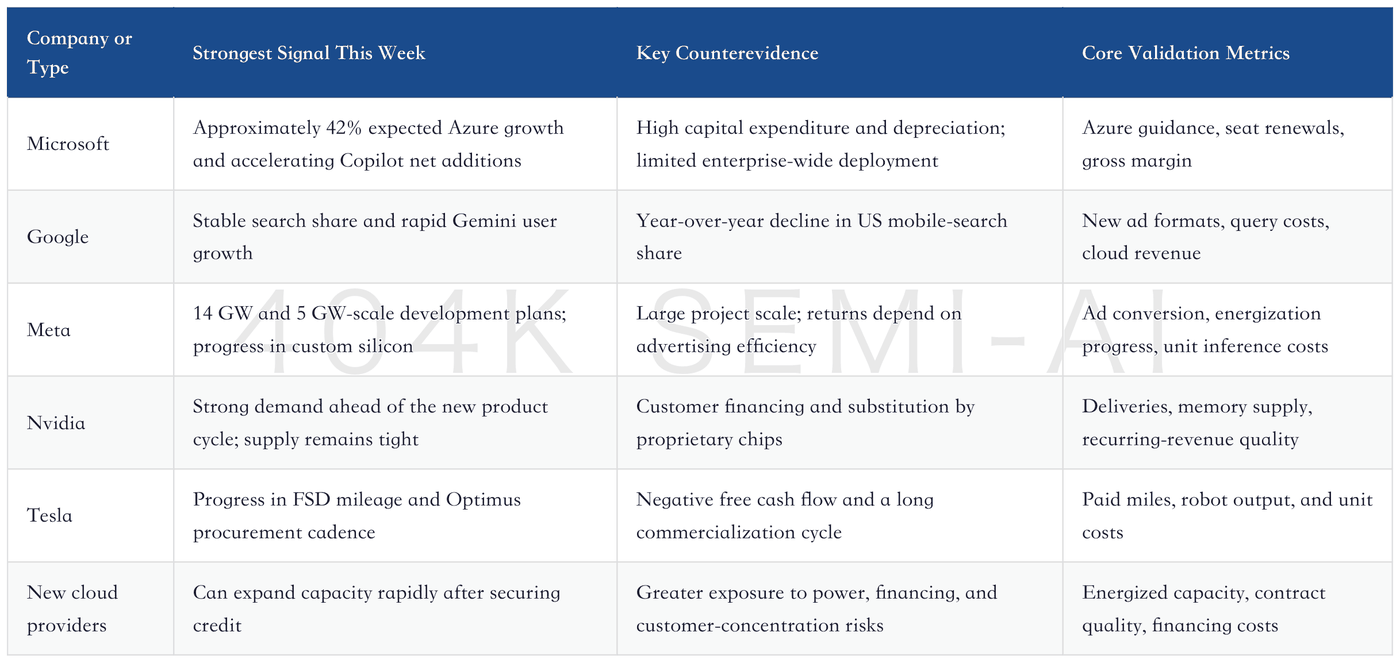
The M7 can no longer be valued under a uniform “AI beneficiary” label. Microsoft’s advantage is its ability to charge directly through enterprise distribution, Azure, and productivity software. Google’s strength lies in the coordination of search and advertising cash flow, proprietary chips, and its cloud platform. Meta benefits from massive internal workloads across recommendation and advertising systems, allowing mature custom silicon to rapidly amortize costs. Nvidia benefits from scarce supply and a full-stack ecosystem, with cash flow realized ahead of cloud providers. Tesla has long-dated optionality in physical AI, but also faces the most direct pressure on capital expenditure and free cash flow. Amazon remains an important player in cloud infrastructure and proprietary silicon, but this week provided insufficient new operating data on a comparable basis to support broader conclusions. Apple likewise should not be evaluated for returns on cloud capital expenditure solely through the theme of on-device AI.
The first dimension of divergence is the length of the revenue loop. Microsoft has the shortest path from Copilot seats to Azure consumption. Google and Meta have a somewhat longer path from model capabilities to advertising revenue, while Tesla has the longest path from training to autonomous-driving or robotics revenue. The longer the chain, the more the market requires intermediate metrics as evidence. The shorter the chain, the more readily revenue growth can offset depreciation. Consequently, the same $10 billion increase in capital expenditure may represent incremental cloud supply for Microsoft but still-unproven future capacity for Tesla.
The second dimension of divergence is the source of capital. This week’s market tracking suggests that Microsoft continues to retain strong free cash flow and financing flexibility during the current AI buildout, while Google may also remain relatively resilient due to advertising cash flow. Some other cloud providers require greater use of debt or project financing. Traditional M7 companies can extend construction timelines, whereas new cloud providers must continuously secure customer prepayments, vendor credit, or external capital. If power connections are delayed, rack deliveries slip, or end customers postpone deployments, interest expense and fixed costs will erode the equity value of new cloud providers more quickly.
The third dimension of divergence is the procurement mix. Nvidia remains the core supplier for frontier training and general-purpose inference, but cloud providers are migrating stable workloads to proprietary chips and using software to orchestrate different architectures. Over the long term, Nvidia’s risk is not the disappearance of AI demand, but the number of general-purpose GPUs required for each unit of AI revenue. The risk for cloud providers is likewise not an inability to purchase chips, but whether custom-chip yields, software ecosystems, and application demand can genuinely reduce unit compute costs. Both sides may continue to grow, with value redistributed among GPUs, custom silicon, networking, and software.
Conclusion: M7 companies and new cloud providers should be prioritized based on “cash-flow quality × commercialization speed × construction certainty.”
Divergences, Disconfirming Evidence, and What to Track Next Week
The first disconfirming signal would be “capex revisions higher without corresponding cloud revenue upgrades.” Microsoft provides the clearest window: if FY2027 capex continues moving toward $261.6 billion while Azure guidance falls below 40% and Copilot net additions miss expectations, the market will interpret the heavy investment as excess supply or delayed returns. Conversely, if Azure sustains growth above 40% and Copilot renewals improve, revenue is more likely to absorb the depreciation burden. Capex and revenue must be assessed together; viewing either in isolation will be misleading.
The second disconfirming signal would be “rapid model-user growth alongside a continued decline in core gateway share.” Google’s global search share remains stable and Gemini is growing rapidly—a positive combination. However, the year-on-year decline in U.S. mobile search share indicates that competition has reached the primary gateway. Next week, investors should continue tracking AI Overviews coverage, new ad formats, conversion rates for commercial queries, and mobile search share. If Gemini’s growth merely offsets losses in traditional search, incremental profits will trail user growth. Only if AI search generates more high-intent queries will Google have truly disrupted itself.
The third disconfirming signal would be “numerous project announcements but persistent delays in energization and rack delivery.” Microsoft’s 3 GW of contracted capacity and Meta’s gigawatt-scale plans must ultimately translate into substations, fiber, servers, and cooling systems. Grid delays at the 90 MW UK project and a one-to-two-month postponement of next-generation racks due to midplane issues suggest the construction clock may be running slower than the demand clock. The most important items to track next week are actual data-center commissioning dates, grid-connection schedules, rack yields, and the next-generation platform’s volume-production ramp—not additional announced capacity.
The fourth disconfirming signal would be “more in-house chip projects without improved unit economics.” Custom chips must demonstrate, under stable workloads, lower cost per token, lower power consumption, and higher utilization than general-purpose GPUs, while maintaining adequate software compatibility. If volume production is delayed, yields disappoint, or software migration costs prove excessive, cloud providers will still have to revert to GPUs. If custom chips ramp successfully, GPU demand can continue growing, but the allocation of hardware value within each dollar of AI revenue will change. The next items to watch are Meta’s custom-chip production ramp, external adoption of Google’s custom chips, customer usage of Amazon’s in-house chips, and related networking and packaging orders.
The fifth disconfirming signal would be “strong supply-chain orders alongside deteriorating cloud-provider cash flow and financing conditions.” Market materials this week estimate that combined AI-related capex by the five major cloud and internet companies could reach approximately $1.8 trillion in 2026–2027, while Nvidia, Micron, Broadcom, and Applied Materials could generate approximately $430 billion in aggregate free cash flow over the next 12 months. These estimates still require quarterly validation against company results, but the direction is clear: capital flows first to chip and equipment suppliers, while buyers bear the payback period. If bond spreads widen, project-financing costs rise, or customer prepayments decline, order visibility will weaken first among emerging cloud providers.
The sixth disconfirming signal would be “high growth already fully reflected in valuations.” Driven by demand for AI servers, thermocompression bonding, and printed circuit board placement equipment, Goldman Sachs raised its 2027 and 2028 net profit forecasts for ASMPT by 16% and 22%, respectively, yet maintained a Neutral rating because the share price already largely reflects the growth. Microsoft’s price target was also cut from $620 to $570 despite higher earnings forecasts, due to multiple compression in software. Improving fundamentals and share-price declines can occur simultaneously; subsequent analysis must compare the magnitude of earnings upgrades with the pace of valuation normalization.
Next week’s tracking sequence should remain fixed: start with cloud revenue and paid application adoption; then assess energized capacity and rack deliveries; next examine in-house chips and packaging orders; and finally verify free cash flow and financing. As long as the revenue clock does not fall behind the construction clock, the AI capex cycle can continue. If construction keeps accelerating while revenue and cash flow decelerate for two consecutive quarters, the investment thesis will shift from “insufficient supply” to “insufficient returns.” That shift has not yet occurred, but the market is already demanding more rigorous evidence.
Related Reading
404K SEMI-AI Semiconductor Equipment Weekly — July 12, 2026 — WFE Upgrades, High-NA Adoption Divergence, and Testing and Cleaning Expansion404K SEMI-AI 2026-07-17 M7 and CSP Weekly — Capex Reaccelerates as Return Validation Reaches an Inflection Point
目录
TL;DR
Overall Assessment This Week
Cloud Revenue and AI Capex
Data Centers, Compute Procurement, and Custom Silicon
Models, Software, and Application Monetization
Divergence Between the M7 and New Cloud Providers
Divergences, Disconfirming Evidence, and What to Track Next Week
The key question this week is not whether AI investment will continue, but whether compute capacity, revenue, and cash flow can materialize at the same pace.
TL;DR
Hyperscalers are still accelerating expansion, with no capex inflection point yet in sight. Citi estimates Microsoft’s FY2027 capex including leases at approximately $261.6 billion, well above the market consensus of roughly $232.0 billion, while forecasting Azure constant-currency growth of 42.2%, versus the market’s approximately 40% estimate. Meta is reportedly planning to raise its 2027 compute capacity to 14GW and add a new 1GW project in Canada. The demand question has shifted from “will they keep buying?” to “can power, data centers, and packaging be delivered on schedule?”
AI infrastructure constraints are broadening from GPU shortages to power, memory, networking, advanced packaging, and system-level integration. Microsoft signed approximately 3GW of future capacity in Q2 2026, including roughly 2.7GW in West Texas. Meanwhile, a 90MW UK project with Microsoft as the anchor tenant is seeking alternative power due to grid-connection delays. Supply-chain checks also suggest that next-generation racks could be delayed by one to two months because of midplane PCB issues, underscoring that having chips does not necessarily mean having deployable compute capacity.
GPUs and in-house chips will coexist over the long term; the real objective of custom silicon is to lower unit inference costs, not immediately replace Nvidia. Nvidia channel feedback continues to point to strong demand, memory shortages lasting several years, and an emerging procurement model in which neoclouds raise financing to acquire compute capacity. Meanwhile, Meta is advancing custom accelerators and CPUs, while Google and Amazon continue expanding their specialized silicon portfolios. Procurement will evolve from GPU-only reliance toward joint optimization across GPUs, specialized chips, networking, and software.
Monetization is beginning to diverge: Microsoft’s enterprise distribution is closest to closing the revenue loop, while Google’s search and advertising foundation remains solid, but neither has fully demonstrated returns. Microsoft’s quarterly channel survey indicates improving Copilot adoption and Azure consumption, although organization-wide deployments remain rare. Google’s global search share rose year over year to 91.3% in June, while Gemini’s web traffic and mobile active users grew rapidly; however, its US mobile search share still declined 123 basis points year over year. User growth is now evident. The next critical question is whether it can convert into high-margin revenue.
Divergence within the M7 will be determined by financing capacity and existing cash flows, not absolute capex levels. Microsoft and Google have deeper cloud and advertising cash-flow buffers, while Meta is using advertising cash flow to acquire compute scale. Tesla, by contrast, faces pressure to demonstrate Robotaxi and Optimus progress quickly after doubling capex and turning free cash flow negative. Neoclouds may also rely on vendor financing and revenue-sharing arrangements. The same AI demand has entirely different balance-sheet implications across companies.
The most important task next week is not finding another larger capex figure, but checking six delivery indicators. In order: Azure growth and guidance, Copilot net additions and renewals, Google search ad load, data-center energization timelines, next-generation rack delivery cadence, and custom-silicon production ramp. If capex estimates continue rising without corresponding improvement in these indicators, the market will shift from rewarding investment scale to scrutinizing free cash flow and return on investment.
Overall Assessment This Week
The clearest conclusion this week is that AI infrastructure remains in an expansion phase, but the valuation framework has shifted from “the more investment, the better” to “can the investment generate measurable returns?” Supply-chain signals remain strong. Feedback from Nvidia-related roadshows indicates that the company could still achieve 95% year-over-year growth in the quarter immediately preceding a new product cycle, while memory shortages may persist for several years. Goldman Sachs also raised its 2026–2028 capex assumptions for US cloud providers by 8%, 27%, and 25%, respectively. These data do not support a near-term demand peak.
The real change is in the evaluation criteria. Previously, the market only needed confirmation that cloud providers were willing to buy GPUs. It must now verify four additional factors: whether data centers can be energized, whether complete systems can be delivered on schedule, whether models can generate revenue, and whether operating cash flow can fund incremental investment. If any link breaks, capex can shift from a growth signal to a source of margin and cash-flow pressure. Microsoft is expected to maintain approximately 42% Azure growth in FY2027, but its gross margin is forecast to decline from 67.7% in FY2026 to 64.3%, while its free-cash-flow yield is projected to fall to 0.8%. This illustrates how accelerating revenue and cash-flow pressure can occur simultaneously.
The M7 and cloud providers should be assessed using three “clocks.” The first is the demand clock, driven by cloud revenue, model usage, enterprise seats, and advertising monetization. The second is the construction clock, determined by power, land, GPUs, memory, networking, packaging, and racks. The third is the return clock, determined by gross margins, free cash flow, and financing costs. This week’s readings are: demand continues to rise, construction is lagging slightly, and returns are beginning to diverge.
Conclusion: The AI investment cycle remains on an upward trajectory, but delivery speeds across different parts of the value chain are diverging.
Tesla provides a highly instructive boundary case. Bank of America estimates its 2026 capex at approximately $26.8 billion. With capex doubling and free cash flow turning negative, the market is no longer focused solely on factory and GPU counts; it is demanding evidence of commercialization from Robotaxi operations and the Optimus procurement ramp. Cumulative FSD mileage has surpassed 10 billion miles, while Optimus suppliers have reportedly been asked to increase weekly capacity to approximately 1,000 units by September and 2,000–2,500 units by year-end. However, these operating signals must still translate into revenue and profit. The same applies to every M7 company: capex demonstrates management confidence, but cannot by itself prove shareholder returns.
Cloud Revenue and AI Capex
Microsoft is this week’s most complete example of “high investment, high growth, and limited free-cash-flow elasticity.” Citi forecasts FY2027 revenue of $389.577 billion, EPS of $19.45, and Azure constant-currency growth of 42.2%. Azure guidance for the next quarter could be 40%–41%, while M365 Copilot net additions are expected to reach approximately 8 million seats in the fiscal fourth quarter, up from 5 million in the prior quarter. Against this, FY2027 capex including capital leases is estimated at approximately $261.6 billion, nearly $30 billion above market expectations. The key question is not which figure is larger, but whether Azure and Copilot can continue accelerating as capacity comes online, offsetting pressure on gross margins from depreciation and AI compute costs.
Microsoft’s channel evidence is positive but not noise-free. A sample of 27 resellers indicates that Azure AI Foundry, AI services, and security remain the primary growth drivers. Partners view Azure committed consumption as broadly stable, while Copilot renewal feedback is also improving. However, another group of partners reported that the largest Copilot deployment involved approximately 25,000 seats at a customer with roughly 30,000 employees, and genuinely organization-wide rollouts remain unrealistic. Large Azure migrations and megadeals are not widespread. In other words, enterprise customers have moved from trials into production, but a substantial gap remains between “pilot-to-renewal conversion” and “organization-wide penetration.”
Meta’s variables are more concentrated around scale and cost. Hardware-industry tracking indicates that Meta is reportedly planning to raise its 2027 compute capacity to 14GW and build a 1GW data center in Canada. Market materials this week also cited plans to expand the Hyperion project in Louisiana to 5GW. Capacity of this magnitude implies that Meta is preparing sustained compute resources not only for training frontier models, but also for recommendations, advertising, content generation, and agentic inference. Its advantage is that the advertising business can provide cash flow; the risk is that faster construction places greater demands on power, networking, custom silicon, and depreciation. Over the next two quarters, higher advertising conversion, increased user time spent, or lower unit inference costs must be evaluated alongside capex.
Google’s capex has an important buffer: its search and advertising foundation has not fallen off a cliff. Bank of America data show that Google’s average daily global web visits rose 4% year over year to 2.8 billion in June, while its global search share increased 171 basis points to 91.3%. In the US, its overall search share edged up year over year to 86.7%. This means Google can fund investment in Gemini, cloud computing, and custom silicon through existing cash flows rather than relying entirely on external financing. However, the risk is equally specific: its US mobile search share declined 123 basis points year over year to 92.8%, indicating competitive pressure at its most important traffic gateway. If AI search increases usage frequency and ad load, capex could convert into incremental revenue. If users migrate faster than new ad formats are launched, margins will come under pressure first.
The industry implications of capex have also broadened from GPUs to advanced packaging and back-end equipment. In its ASMPT report, Goldman Sachs raised its 2026–2028 capex forecasts for US cloud providers by 8%, 27%, and 25%, respectively, and for Chinese cloud providers by 37%, 44%, and 55%. It also raised its implied AI-server chip shipment forecasts by 14%, 22%, and 14%, respectively. ASMPT received a repeat order from a global integrated device manufacturer for eight chip-to-wafer thermocompression bonding systems, demonstrating that cloud-provider budgets are flowing downstream through GPUs, packaging, assembly, and testing. Whether capex is being realized should not be assessed solely through cloud-provider financial statements; it can also be cross-checked against equipment orders and capacity utilization.
Data Centers, Compute Procurement, and Custom Silicon
The primary data-center constraint is shifting from chips to complete systems that can be powered, connected, and operated. Microsoft contracted approximately 3 GW of future capacity in Q2 2026, including a roughly 2.7 GW project with Chevron in West Texas estimated to cost $8–10 billion; its Fairwater data center in Wisconsin was completed ahead of schedule and is now operational. This positive example shows that securing power and construction partners early can convert capital expenditure into Azure revenue more quickly. By contrast, a planned 90 MW, £2 billion data center in Essex, UK, where Microsoft is the anchor tenant, is considering on-site generation because the grid cannot provide its scheduled connection by 2027. Viewed together, planned GW capacity is not usable compute; the energization date marks the beginning of revenue generation.
The second constraint is rack-level coordination. Server-industry materials estimate that approximately 70,000–80,000 GB200 and GB300 racks will ship in 2026. However, next-generation VR200 racks could be delayed by one to two months from the original schedule due to issues with components such as midplane printed circuit boards, pushing the production ramp into Q4 2026. A delay in a single component affects system manufacturers, cloud deployment timelines, and GPU revenue recognition simultaneously. AI compute wafer consumption is estimated to reach as much as $46 billion in 2027, indicating that demand remains strong, but supply-chain execution will increasingly depend on the synchronized maturity of printed circuit boards, connectors, optical modules, memory, power systems, and liquid cooling.
The third constraint is memory and networking. Feedback from Nvidia roadshows suggests that memory shortages could persist for several years, with customers using lower-memory configurations to keep systems operational. Compute procurement therefore cannot be assessed solely by GPU count; high-bandwidth memory, network bandwidth, and rack power must also be considered. If GPUs arrive before memory or networking infrastructure, cloud providers incur depreciation without being able to deliver a complete service. If system configurations must be downgraded, sellable tokens per GPU will also fall below design capacity. This is the most frequently overlooked timing gap between capital-expenditure scale and actual cloud revenue.
The value of custom silicon lies in improving the long-term cost curve, not in signaling the end of the GPU cycle. Server-industry materials indicate that cloud service providers are planning additional proprietary-chip programs. Market tracking on Meta this week noted that the company is expanding its custom accelerator and CPU partnerships, with TSMC handling manufacturing, Arm providing the CPU architecture, and partners including Broadcom participating in high-speed silicon. Google and Amazon already use proprietary chips for internal training and inference workloads. Custom silicon is suited to stable, scalable, and predictable workloads, while GPUs will continue to handle frontier training, rapid iteration, and general-purpose compute. The most rational procurement mix is not a binary choice: GPUs provide flexibility, custom silicon lowers unit costs, and networking and software integrate both into marketable services.
New cloud providers are also incorporating financing structures into procurement decisions. Nvidia channel feedback suggests that some new cloud providers may receive vendor financing and exchange a share of future revenue for compute capacity. If compute remains scarce, this model can rapidly expand the ecosystem and potentially generate high-margin recurring revenue for upstream suppliers. However, it also embeds credit risk and customer profitability into the supply chain. Traditional M7 procurement is primarily supported by internal cash flow and balance sheets; for new cloud providers, order quality must also be assessed based on contract duration, end customers, financing costs, and secured power. Identical GPU orders can therefore carry very different risk implications.
Models, Software, and Application Monetization
Microsoft is developing the closest approximation to a closed-loop enterprise revenue model, with cloud resources, developer platforms, productivity seats, and security products reinforcing one another. Channel surveys indicate that Copilot Studio is typically deployed alongside Microsoft 365 Copilot, while Fabric and Power BI also drive Azure usage. Some partners have observed higher renewal rates and lower discounts following trials, suggesting that customers are no longer paying solely for the “AI narrative” but are retaining budgets for production use cases. Citi expects approximately 8 million net new Copilot seats in the fiscal fourth quarter and believes Azure can sustain roughly 42% growth in FY2027, creating a positive cycle in which applications drive cloud consumption and cloud capacity supports application expansion.
However, this closed loop is not yet fully established. Some surveyed customers still believe E5 has not delivered its full value, while E7 transactions require substantial discounts to accelerate adoption. Enterprise-wide Copilot deployments remain rare, with many projects limited to individual departments. For Microsoft, the key issue is not how many agents it has announced, but three operating metrics: whether paid seats continue to increase on a net basis, whether renewal discounts continue to decline, and whether Azure consumption generated by Copilot exceeds inference costs. If all three improve together, revenue growth will absorb the decline in AI gross margins. If seat growth depends on promotions while cloud costs continue to rise, the income statement will expose the problem first.
Google’s models are growing faster, but monetization primarily depends on search, advertising, and cloud. In June, Gemini’s global web traffic increased 341% year over year, while mobile daily active users rose 295% to 118 million. Claude’s web traffic increased 736% year over year, with mobile daily active users rising 1,206% to 18 million. These high growth rates show that users are migrating toward multiple model interfaces, but their absolute scale remains far below Google Search. Google has approximately 2.2 billion global mobile daily active users and retains more than 91% of the global search market. Gemini’s strategic value therefore extends beyond subscription revenue: it helps defend the search gateway, increase query frequency, expand agentic tasks, and create new advertising formats.
An easily overlooked divergence remains: more AI-generated answers do not necessarily mean weaker search advertising, nor do they necessarily mean higher advertising revenue. If AI Overviews and agents make users more efficient at completing tasks, search usage and commercial intent could expand. If answer pages reduce clicks, ad load, and merchant bidding, monetization could instead lag. BofA believes Google’s description of search entering an “expansionary moment” could produce higher usage, stronger understanding of commercial intent, and new advertising formats, but the year-over-year decline in US mobile-search share remains counterevidence. The next stage should be assessed through query growth, ad load, cost per query, and traffic-acquisition costs—not model rankings alone.
Meta’s model returns are reflected more in advertising systems and content efficiency than in standalone model sales. Its large-scale compute buildout and custom-silicon initiatives are primarily intended to reduce the unit costs of recommendations, ad generation, creator tools, and agents. If its models improve advertising conversion and user engagement, compute investment can scale rapidly through the existing advertising network. If user growth does not translate into higher ad pricing or conversion rates, 5 GW-scale projects will accelerate depreciation more quickly. Meta differs from Microsoft in that the former monetizes indirectly through advertising cash flow, while the latter charges directly through seats and cloud consumption. Their evaluation metrics should not be conflated.
Tesla represents the more challenging path of investing simultaneously in software and physical assets. Cumulative FSD mileage has exceeded 10 billion miles, and both Robotaxi and Optimus could create enormous potential markets, but vehicles, factories, robots, and training clusters all require concurrent investment. Suppliers being asked to increase weekly Optimus capacity is a signal of industrialization, but not revenue recognition. Capital expenditure will only shift from a long-dated option to estimable cash flow once Tesla begins regularly disclosing paid Robotaxi miles, utilization per vehicle, accident rates, productive robot hours, and unit costs.
Divergence Between the M7 and New Cloud Providers
The M7 can no longer be valued under a uniform “AI beneficiary” label. Microsoft’s advantage is its ability to charge directly through enterprise distribution, Azure, and productivity software. Google’s strength lies in the coordination of search and advertising cash flow, proprietary chips, and its cloud platform. Meta benefits from massive internal workloads across recommendation and advertising systems, allowing mature custom silicon to rapidly amortize costs. Nvidia benefits from scarce supply and a full-stack ecosystem, with cash flow realized ahead of cloud providers. Tesla has long-dated optionality in physical AI, but also faces the most direct pressure on capital expenditure and free cash flow. Amazon remains an important player in cloud infrastructure and proprietary silicon, but this week provided insufficient new operating data on a comparable basis to support broader conclusions. Apple likewise should not be evaluated for returns on cloud capital expenditure solely through the theme of on-device AI.
The first dimension of divergence is the length of the revenue loop. Microsoft has the shortest path from Copilot seats to Azure consumption. Google and Meta have a somewhat longer path from model capabilities to advertising revenue, while Tesla has the longest path from training to autonomous-driving or robotics revenue. The longer the chain, the more the market requires intermediate metrics as evidence. The shorter the chain, the more readily revenue growth can offset depreciation. Consequently, the same $10 billion increase in capital expenditure may represent incremental cloud supply for Microsoft but still-unproven future capacity for Tesla.
The second dimension of divergence is the source of capital. This week’s market tracking suggests that Microsoft continues to retain strong free cash flow and financing flexibility during the current AI buildout, while Google may also remain relatively resilient due to advertising cash flow. Some other cloud providers require greater use of debt or project financing. Traditional M7 companies can extend construction timelines, whereas new cloud providers must continuously secure customer prepayments, vendor credit, or external capital. If power connections are delayed, rack deliveries slip, or end customers postpone deployments, interest expense and fixed costs will erode the equity value of new cloud providers more quickly.
The third dimension of divergence is the procurement mix. Nvidia remains the core supplier for frontier training and general-purpose inference, but cloud providers are migrating stable workloads to proprietary chips and using software to orchestrate different architectures. Over the long term, Nvidia’s risk is not the disappearance of AI demand, but the number of general-purpose GPUs required for each unit of AI revenue. The risk for cloud providers is likewise not an inability to purchase chips, but whether custom-chip yields, software ecosystems, and application demand can genuinely reduce unit compute costs. Both sides may continue to grow, with value redistributed among GPUs, custom silicon, networking, and software.
Conclusion: M7 companies and new cloud providers should be prioritized based on “cash-flow quality × commercialization speed × construction certainty.”
Divergences, Disconfirming Evidence, and What to Track Next Week
The first disconfirming signal would be “capex revisions higher without corresponding cloud revenue upgrades.” Microsoft provides the clearest window: if FY2027 capex continues moving toward $261.6 billion while Azure guidance falls below 40% and Copilot net additions miss expectations, the market will interpret the heavy investment as excess supply or delayed returns. Conversely, if Azure sustains growth above 40% and Copilot renewals improve, revenue is more likely to absorb the depreciation burden. Capex and revenue must be assessed together; viewing either in isolation will be misleading.
The second disconfirming signal would be “rapid model-user growth alongside a continued decline in core gateway share.” Google’s global search share remains stable and Gemini is growing rapidly—a positive combination. However, the year-on-year decline in U.S. mobile search share indicates that competition has reached the primary gateway. Next week, investors should continue tracking AI Overviews coverage, new ad formats, conversion rates for commercial queries, and mobile search share. If Gemini’s growth merely offsets losses in traditional search, incremental profits will trail user growth. Only if AI search generates more high-intent queries will Google have truly disrupted itself.
The third disconfirming signal would be “numerous project announcements but persistent delays in energization and rack delivery.” Microsoft’s 3 GW of contracted capacity and Meta’s gigawatt-scale plans must ultimately translate into substations, fiber, servers, and cooling systems. Grid delays at the 90 MW UK project and a one-to-two-month postponement of next-generation racks due to midplane issues suggest the construction clock may be running slower than the demand clock. The most important items to track next week are actual data-center commissioning dates, grid-connection schedules, rack yields, and the next-generation platform’s volume-production ramp—not additional announced capacity.
The fourth disconfirming signal would be “more in-house chip projects without improved unit economics.” Custom chips must demonstrate, under stable workloads, lower cost per token, lower power consumption, and higher utilization than general-purpose GPUs, while maintaining adequate software compatibility. If volume production is delayed, yields disappoint, or software migration costs prove excessive, cloud providers will still have to revert to GPUs. If custom chips ramp successfully, GPU demand can continue growing, but the allocation of hardware value within each dollar of AI revenue will change. The next items to watch are Meta’s custom-chip production ramp, external adoption of Google’s custom chips, customer usage of Amazon’s in-house chips, and related networking and packaging orders.
The fifth disconfirming signal would be “strong supply-chain orders alongside deteriorating cloud-provider cash flow and financing conditions.” Market materials this week estimate that combined AI-related capex by the five major cloud and internet companies could reach approximately $1.8 trillion in 2026–2027, while Nvidia, Micron, Broadcom, and Applied Materials could generate approximately $430 billion in aggregate free cash flow over the next 12 months. These estimates still require quarterly validation against company results, but the direction is clear: capital flows first to chip and equipment suppliers, while buyers bear the payback period. If bond spreads widen, project-financing costs rise, or customer prepayments decline, order visibility will weaken first among emerging cloud providers.
The sixth disconfirming signal would be “high growth already fully reflected in valuations.” Driven by demand for AI servers, thermocompression bonding, and printed circuit board placement equipment, Goldman Sachs raised its 2027 and 2028 net profit forecasts for ASMPT by 16% and 22%, respectively, yet maintained a Neutral rating because the share price already largely reflects the growth. Microsoft’s price target was also cut from $620 to $570 despite higher earnings forecasts, due to multiple compression in software. Improving fundamentals and share-price declines can occur simultaneously; subsequent analysis must compare the magnitude of earnings upgrades with the pace of valuation normalization.
Next week’s tracking sequence should remain fixed: start with cloud revenue and paid application adoption; then assess energized capacity and rack deliveries; next examine in-house chips and packaging orders; and finally verify free cash flow and financing. As long as the revenue clock does not fall behind the construction clock, the AI capex cycle can continue. If construction keeps accelerating while revenue and cash flow decelerate for two consecutive quarters, the investment thesis will shift from “insufficient supply” to “insufficient returns.” That shift has not yet occurred, but the market is already demanding more rigorous evidence.