
404K SEMI-AI 2026-07-12 M7 & CSP Weekly — Capex Estimates Rise Again, Compute Supply Remains Tight, and Custom Silicon Enters the Monetization Phase
目录
Overall Assessment This Week
Cloud Revenue and AI Capex
Data Centers, Compute Procurement, and Custom Silicon
Models, Software, and Application Monetization
Divergence Across the M7 and Emerging Cloud Providers
Points of Debate, Disconfirming Evidence, and Next Week’s Watchlist
Overview
The clearest development this week is that cloud demand remains strong, while capex estimates are rising even faster. Amazon and Microsoft are paying ahead for capacity over the next two years. Near-term revenue is constrained by supply, while cash flow is coming under greater pressure. Compute bottlenecks have spread from GPUs to power, memory, advanced packaging, and networking. Progress on Google’s TPU, Amazon’s Trainium, and Microsoft’s Maia is beginning to directly affect cloud revenue and margins. Alibaba Cloud offers an alternative path featuring simultaneous improvements in revenue and margins, although GPU availability, memory supply, and domestic competition remain constraints.
404K SEMI-AI | 2026-07-12
Overall Assessment This Week
Cloud providers are turning a demand question into a supply question. Amazon still has a substantial backlog that can be monetized quickly as new capacity comes online; Azure’s quarterly growth also remains capacity-constrained. Meta is reportedly considering offering cloud compute capacity externally. Industry checks suggest GPUs remain scarce and that renting out compute may be more profitable than using it internally. These three data points lead to the same conclusion: customer demand has not cooled materially, and whoever secures power, servers, memory, and networking first will recognize revenue sooner.
Capex comes before revenue, so cash-flow pressure will emerge first. Goldman Sachs raised its estimate for AWS’s 2027 capex to approximately $229.4 billion, while its FY28 capex forecast for Microsoft increased to $319 billion. Whether revenue materializes depends on the pace at which new capacity comes online; whether valuations hold depends additionally on financing costs, depreciation, and revenue per GW.
Custom silicon is entering the execution phase for revenue, gross margin, and supply security. Amazon’s Trainium is intended to reduce inference costs and improve AWS’s long-term margins; Microsoft needs Maia and AMD chips to reduce its dependence on Nvidia; and Google’s TPU is extending the project cycles of Broadcom, MediaTek, and Global Unichip. Custom silicon is no longer merely a technology-roadmap decision. It determines how much compute cloud providers can procure, the cost of each inference, and whether profits accrue to the cloud platform or upstream GPU vendors.
Power and memory determine the ceiling for expansion. Google’s electricity consumption exceeded 43 TWh, up 37% year over year, while its 24/7 carbon-free energy score remained at 65%.
Amazon does not directly disclose data-center electricity consumption. Barclays estimates it at approximately 90 TWh based on water withdrawals and water-use efficiency. Both companies are improving cooling efficiency, but transmission, grid interconnection, firm power supply, and memory availability remain the real constraints delaying projects.
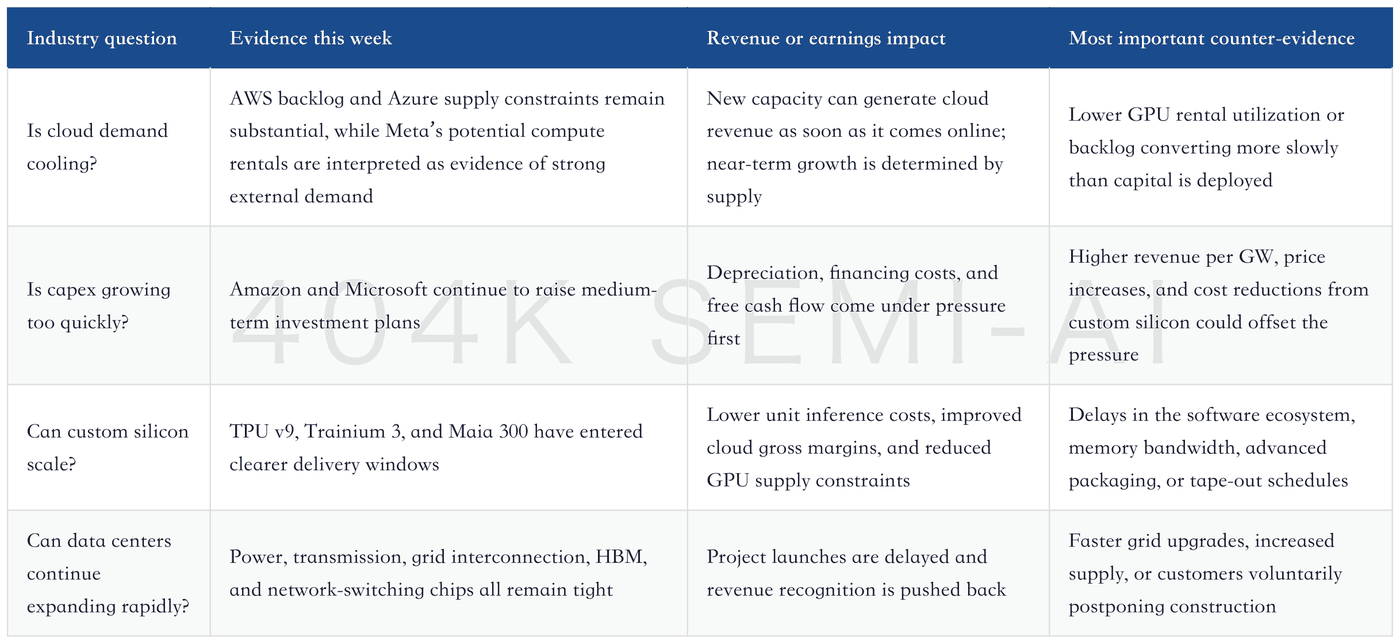
This week’s key developments fall into four areas.
Cloud demand remains strong; supply and capital efficiency determine the pace of monetization
Cloud Revenue and AI Capex
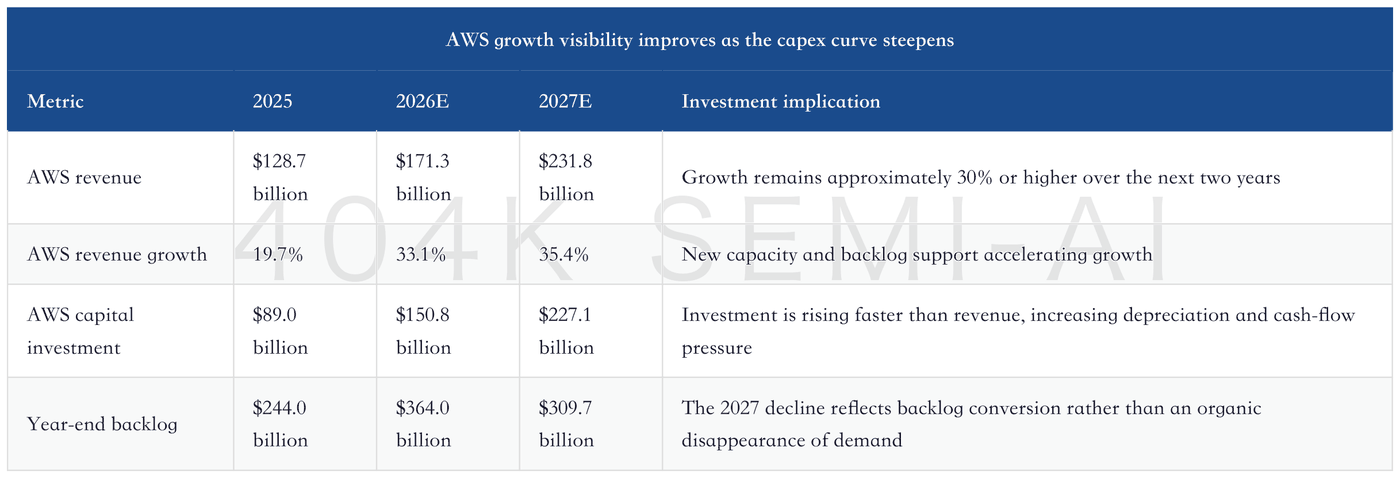
Amazon offers this week’s clearest example of both the highest capital intensity and the strongest revenue visibility. Goldman Sachs expects AWS revenue growth to remain above 30% over the next two years, with capital investment growing even faster. Investors need to track both backlog conversion and cash flow.
Amazon’s cloud revenue and capital investment continue to rise together.
Amazon’s construction targets push the funding burden into 2027. Third-party data estimates that Amazon had approximately 6.85 GW of data-center capacity in 2025, with around 260 data centers yet to come online.
The company plans to double its existing capacity again by 2027.
Goldman Sachs’ hardware team estimates that each additional 1 GW of data-center capacity requires $50–60 billion, most of which is spent on servers and storage. The lag between cash investment and customer payments is approximately 0.5–2 years.
Backlog can support higher revenue, but the upside scenario should not be treated as the base case. Goldman Sachs’ conversion model assumes that cloud capital investment generates returns over six years and that year-end backlog is recognized over five years, with half converted within the first 24 months. The model indicates approximately 10%–20% upside to AWS revenue, but the report explicitly defines this as an illustrative scenario. If capex estimates continue to rise without a corresponding increase in backlog, returns on investment will deteriorate first.
Free cash flow is the first risk likely to surface at Amazon. Goldman Sachs expects Amazon’s free cash flow to equity to turn negative by $41 billion in 2027, followed by a cumulative shortfall of approximately $70 billion over the subsequent two years. The company’s debt-to-adjusted EBITDA ratio has remained below 1x over the long term, leaving financing capacity available.
Its average cost of debt has already risen from 3.17% to 4.45%. Continued cloud revenue growth can support long-term returns, but near-term valuation will become more sensitive to financing costs and depreciation.
Microsoft’s revenue bottleneck is also on the supply side, but internal compute allocation makes Azure’s growth more difficult to assess. Goldman Sachs expects Azure’s constant-currency growth to reach 40%–41% in the fiscal fourth quarter, slightly above company guidance. New capacity at the Fairwater data center is coming online unevenly. Microsoft must also allocate GPUs among external Azure customers, Copilot, and internal model development, meaning additional compute capacity may not immediately translate into Azure revenue.
Microsoft’s capex upgrades have already exceeded its revenue upgrades.
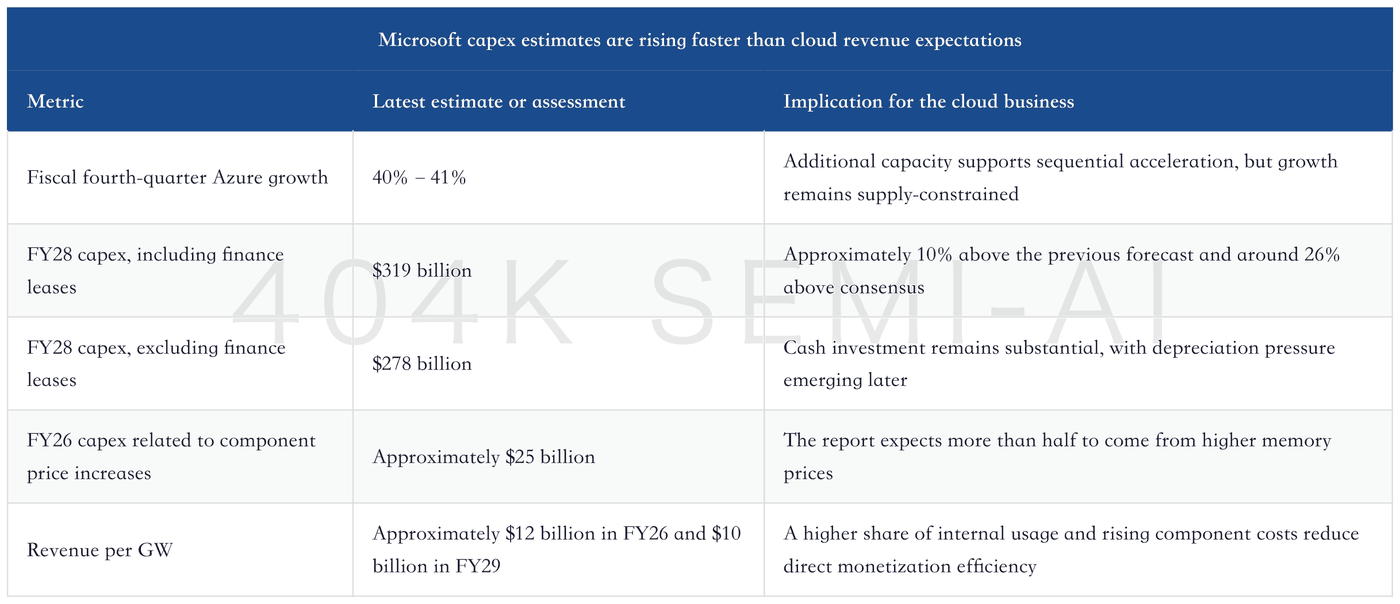
Revenue per GW is the most important efficiency metric to monitor for Microsoft. Goldman Sachs estimates that it will decline from approximately $12 billion in FY26 to around $10 billion in FY29. The reasons include more compute capacity being retained for internal applications, higher component prices, and new capacity that has yet to reach full utilization. Better Copilot paid conversion, a higher inference mix, and improved chip efficiency could reverse this trend. If capex estimates continue to rise while revenue per GW keeps falling, Azure growth alone will not adequately explain investment returns.
Alibaba Cloud provides a contrasting case in which revenue and margins improve simultaneously. Citi expects Alibaba’s FY1Q27 cloud revenue to reach RMB48.4 billion, up 45% year over year and above its previous 40% forecast.
Cloud EBITA is expected to reach approximately RMB5.6 billion, representing an 11.5% margin. As domestic e-commerce revenue comes under pressure, cloud is becoming an important pillar of earnings growth. The key questions are whether cloud revenue can continue accelerating, whether low-teens margins can be sustained, and whether GPU and memory availability will delay delivery.
Data Centers, Compute Procurement, and Custom Silicon
Data center development has entered a phase of “orders secured, resources constrained.” Google consumed more than 43 TWh of electricity in 2025, with data centers accounting for over 97% of total consumption.
Compute performance per unit of energy increased more than threefold over five years, while electricity consumption rose 37%. Based on this, Barclays estimates that Google’s delivered compute capacity may have grown by approximately 55%–60% annually in recent years.
Google and Amazon face different resource constraints.
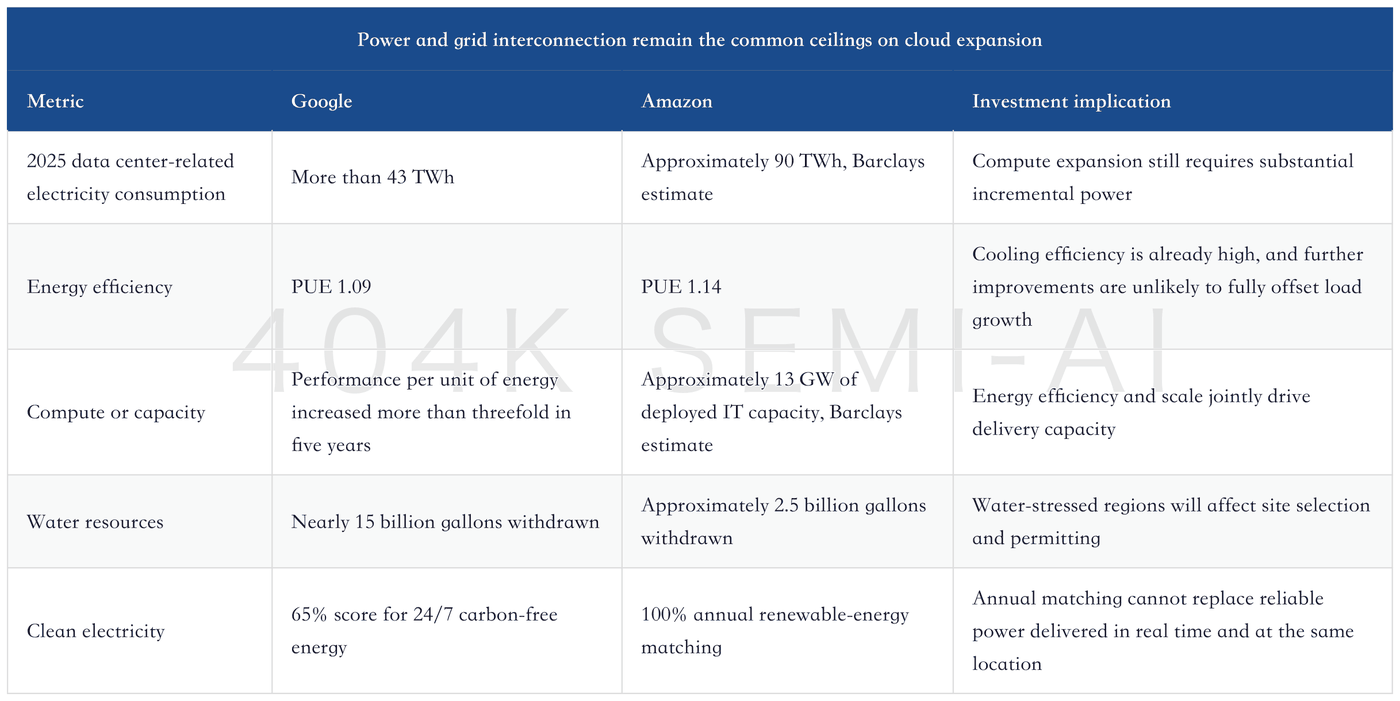
The grid is more likely than generation projects to delay commissioning. Google disclosed that transmission, interconnection queues, and administrative approvals can create delays of four to five years between signing a clean-energy contract and actually delivering the electricity to the grid. Advanced geothermal and small modular nuclear reactors could provide reliable carbon-free power, but large-scale commercialization may not occur until the 2030s. Cloud providers can sign power purchase agreements, but cannot independently compress every stage of the interconnection timeline.
Cooling technology can save power and water, but cannot solve the shortage of firm electricity supply. Amazon disclosed that direct liquid cooling can reduce mechanical cooling energy consumption by up to 50% during peak cooling periods. In-rack heat-exchange systems are expected to use approximately 9% less water than conventional evaporative air-cooling designs. These technological improvements can increase compute density within the same campus, but project commissioning still depends on grid access and continuous power supply.
Google’s TPU supply chain is evolving from a single-chip project into a long-duration platform order. Broadcom management confirmed that the TPU v9 roadmap remains on schedule, with volume ramp expected in 2028; under its five-year agreement with Google, Broadcom expects to retain the majority of shipment share. TPUs drive demand not only for compute chips, but also for high-speed SerDes, advanced packaging, and Ethernet switching silicon. Tomahawk 6 is already supply-constrained, indicating that the bottleneck in compute procurement is spreading from accelerator cards to networking.
Custom-silicon projects offer significant revenue elasticity, but supply allocation determines the pace of realization.
Custom silicon enters the delivery phase, with capacity allocation determining revenue elasticity
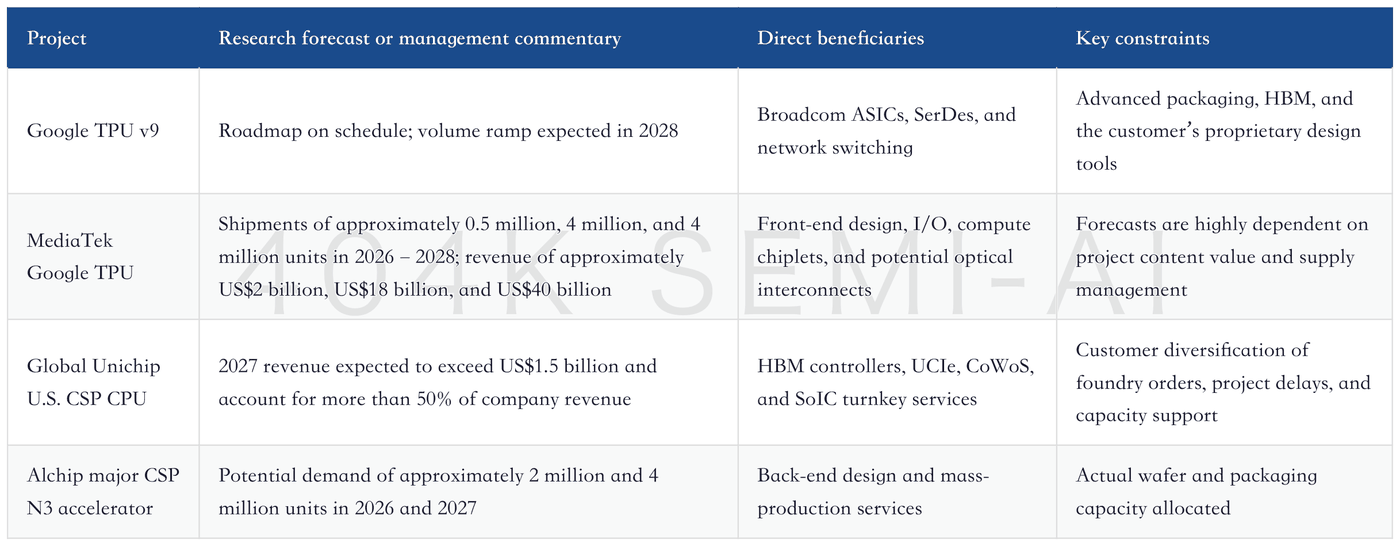
The value of Amazon Trainium lies in cloud gross margin; it does not need to displace Nvidia to succeed. Goldman Sachs cited Amazon’s shareholder letter as saying that Trainium 2 is essentially sold out, Trainium 3 is nearly fully reserved, and the related chip business has approximately US$20 billion in annualized revenue. Trainium 3 offers approximately 40% better price-performance than the prior generation, making it suitable for more cost-sensitive inference workloads. As long as it absorbs incremental internal AWS demand, it can reduce reliance on externally purchased GPUs and improve long-term incremental margins.
Microsoft’s custom silicon still lags peers, and generational improvements around 2027 will determine whether the gap can narrow. Goldman Sachs believes Maia is less mature than other cloud providers’ solutions, leaving Microsoft more dependent on Nvidia. Maia 200 uses HBM3, while Nvidia Vera Rubin uses HBM4; the memory-bandwidth gap will affect system cost and performance. Microsoft is adding AMD as a second source and expects Maia 300 to incorporate lessons from the first two generations. Future assessment should focus on actual volume production, migration of internal workloads, and revenue per GW—not merely the tape-out node.
Nvidia remains the common denominator in cloud-provider expansion. Morgan Stanley’s management survey indicates that traditional hyperscalers account for approximately half of Nvidia’s revenue, with land and power increasingly constraining incremental growth. Demand from AI clouds, industrial customers, and enterprises has also become a significant component of data center revenue. Nvidia believes the compute value supported by 1 GW will rise from approximately US$30 billion–US$40 billion today to US$100 billion, driven by generational improvements in energy efficiency. This figure represents a long-term efficiency target and should not be treated as near-term revenue guidance.
GPUs and ASICs will grow together. Broadcom believes that XPU and GPU shipments among leading model developers could approach an even split next year. Morgan Stanley also sees both Nvidia’s and Broadcom’s AI businesses growing rapidly while remaining supply-constrained. Cloud providers will use ASICs to lower the cost of stable, large-scale inference workloads, while retaining GPUs for general-purpose training, rapid iteration, and external cloud rental demand. The two architectures are competing for incremental budgets and workload mix, rather than simply replacing one another.
Models, Software, and Application Monetization
This week’s core application-monetization theme is converting existing compute into higher revenue, rather than comparing model capabilities. Amazon’s levers are EC2 pricing, custom silicon, and shopping entry points; Microsoft’s lever is compute allocation between Azure and Copilot; Alibaba Cloud’s levers are enterprise AI tools, data center expansion, and service revenue. All address the same question: can elevated capital expenditure generate sustainable cloud revenue and profits?
EC2 pricing is Amazon’s most direct revenue lever, but contract structures will delay realization. In its scenario analysis, Goldman Sachs assumes a 20% price increase for elastic compute services and estimates that this could generate approximately US$2 billion–US$4 billion in incremental net revenue in the second half of 2026. The business is estimated to account for more than half of AWS revenue, making pricing changes significant. Multi-year Savings Plan prices will not reset immediately, and customers will optimize usage, so this estimate is better viewed as a range of potential sensitivity.
Microsoft needs to demonstrate that Copilot can improve returns per unit of compute. Microsoft will prioritize some GPUs for Copilot and internal R&D;, which will reduce current-period Azure revenue but could generate higher application-layer profits. Goldman Sachs cited more than 20 million Copilot seats in the fiscal third quarter. The next variables to monitor are paid conversion, usage intensity, and whether fair-use terms can cover inference costs. If usage increases without corresponding price adjustments, gross margin will come under pressure.
Alibaba Cloud’s enterprise applications are beginning to scale alongside infrastructure expansion. Alibaba Cloud is expanding data centers in Europe, Malaysia, Japan, and Mexico, bringing its footprint to 32 regions and 105 availability zones. It is also advancing enterprise collaboration, development, and SAP cloud services. Whether the application layer can drive higher margins comes down to two financial metrics: cloud revenue growth and cloud EBITA margin. Citi currently forecasts 45% revenue growth and an 11.5% margin, providing a clear benchmark for the next earnings report.
Divergence Across the M7 and Emerging Cloud Providers
Divergence within the M7 stems first from differences in resource endowments. Amazon has a substantial backlog and a more mature Trainium platform, providing high growth visibility at the cost of the greatest pressure on capital expenditure and free cash flow. Microsoft faces strong Azure demand and is bringing new capacity such as Fairwater online, but in-house chips and internal compute allocation make monetization efficiency more complex. Google leads in TPU capabilities and energy efficiency, but grid interconnection and access to reliable 24/7 clean power constrain its expansion. If Meta begins leasing compute externally, it would improve GPU utilization while making it harder for investors to infer internal demand from capital expenditure alone.
Alibaba Cloud’s advantage is simultaneous improvement in revenue and margins; its weaknesses are supply and competition. Citi raised its FY1Q27 cloud revenue growth forecast to 45% and expects the margin to reach 11.5%. This represents a more verifiable path to profitability than pursuing scale alone. The report also identifies GPU and memory supply, domestic competition, and capital expenditure as key topics for the earnings call, indicating that sustained high growth still depends on supply availability and pricing.
Emerging cloud providers broaden Nvidia’s customer base but introduce new credit risks. Nvidia management highlighted new partnership models with emerging cloud customers involving co-investment, credit support, and revenue sharing. These arrangements can accelerate GPU-cloud expansion and allow Nvidia to capture more upside; however, if end-user utilization is insufficient, the chip supplier will bear greater financing and collection risks. GPU shipments should therefore be assessed alongside emerging-cloud revenue, utilization, and financing terms.
On-premises enterprise deployments will absorb some inference workloads, while the cloud will retain orchestration and elasticity demand. A former Microsoft AI transformation executive observed that enterprises will deploy individual agents on-premises or at the edge for reasons including cost, latency, governance, and data sovereignty, while using the cloud for multi-agent orchestration. Improved energy efficiency and labor savings from new servers can provide budget capacity for hardware purchases. For CSPs, this means inference workloads will become more distributed, and cloud revenue will increasingly depend on hybrid architectures, software governance, and peak compute demand.
Points of Debate, Disconfirming Evidence, and Next Week’s Watchlist
The central debate is how long capital expenditure can continue to run ahead of revenue. The bullish case assumes that backlogs are sufficiently large for new capacity to be monetized as soon as it comes online, while in-house chips and pricing can improve margins. The cautious case assumes that grid and memory constraints will delay deployment, while depreciation and interest expenses hit the income statement before revenue is recognized, weighing on free cash flow and valuation.
The next phase requires verifiable data to determine which path is materializing.
Returns on capital, in-house chips, and power constraints form the core validation framework.
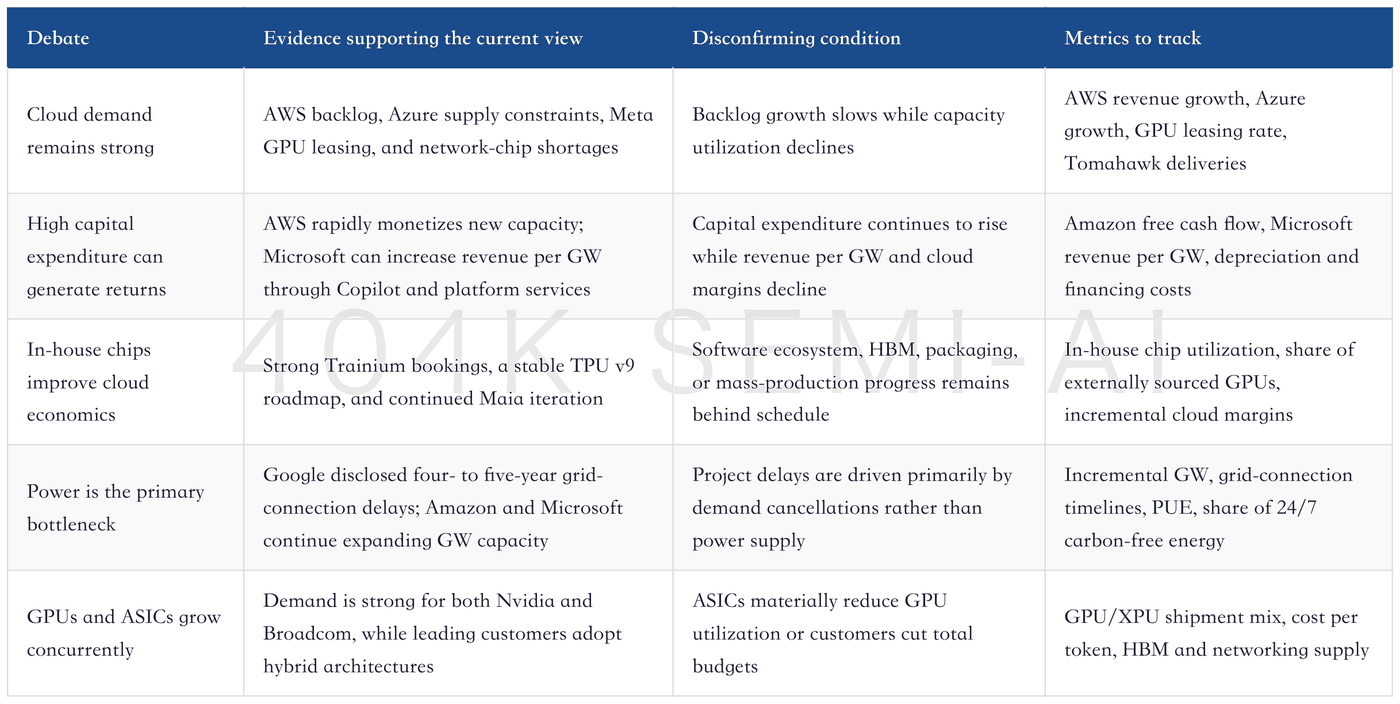
For Amazon, the key question is whether revenue realization can catch up with capital investment. The next financial update should be assessed against AWS growth, backlog, incremental capacity, capital expenditure, and free cash flow. Goldman Sachs’ 10%–20% revenue upside scenario depends on relatively rapid backlog conversion; weakness in any of these metrics would reduce the model’s credibility.
For Microsoft, the focus is Azure guidance and internal compute allocation. The key metrics for the July 29 earnings release are whether Azure constant-currency growth reaches 40%–41%, whether new capacity continues to come online, and whether revenue forecasts keep pace with upward revisions to capital expenditure. Progress in Maia, AMD, and memory procurement will shape the cost curve over the next two years.
For Google and Meta, the focus is how compute capacity is utilized. Google’s key metrics are TPU share, data-center power consumption, grid interconnection, and progress toward 24/7 carbon-free energy. For Meta, the key question is whether external compute services materialize and whether they reflect robust external demand or insufficient internal utilization. The two interpretations carry entirely different implications for GPU procurement and capital expenditure.
For Alibaba Cloud, the focus is growth quality. Citi’s base case calls for 45% cloud revenue growth and an 11.5% cloud EBITA margin in FY1Q27. Revenue above expectations accompanied by margin deterioration would indicate that supply or pricing pressure remains significant; only simultaneous delivery on revenue and margins would demonstrate that enterprise AI and infrastructure investment are beginning to generate sustainable returns.
Related Reading
404K Technology Weekly 2026-07-04 — Memory Pricing Power, Compute Assetization, Hardware Bottlenecks Spreading404K SEMI-AI 2026-07-12 M7 & CSP Weekly — Capex Estimates Rise Again, Compute Supply Remains Tight, and Custom Silicon Enters the Monetization Phase
目录
Overall Assessment This Week
Cloud Revenue and AI Capex
Data Centers, Compute Procurement, and Custom Silicon
Models, Software, and Application Monetization
Divergence Across the M7 and Emerging Cloud Providers
Points of Debate, Disconfirming Evidence, and Next Week’s Watchlist
Overview
The clearest development this week is that cloud demand remains strong, while capex estimates are rising even faster. Amazon and Microsoft are paying ahead for capacity over the next two years. Near-term revenue is constrained by supply, while cash flow is coming under greater pressure. Compute bottlenecks have spread from GPUs to power, memory, advanced packaging, and networking. Progress on Google’s TPU, Amazon’s Trainium, and Microsoft’s Maia is beginning to directly affect cloud revenue and margins. Alibaba Cloud offers an alternative path featuring simultaneous improvements in revenue and margins, although GPU availability, memory supply, and domestic competition remain constraints.
404K SEMI-AI | 2026-07-12
Overall Assessment This Week
Cloud providers are turning a demand question into a supply question. Amazon still has a substantial backlog that can be monetized quickly as new capacity comes online; Azure’s quarterly growth also remains capacity-constrained. Meta is reportedly considering offering cloud compute capacity externally. Industry checks suggest GPUs remain scarce and that renting out compute may be more profitable than using it internally. These three data points lead to the same conclusion: customer demand has not cooled materially, and whoever secures power, servers, memory, and networking first will recognize revenue sooner.
Capex comes before revenue, so cash-flow pressure will emerge first. Goldman Sachs raised its estimate for AWS’s 2027 capex to approximately $229.4 billion, while its FY28 capex forecast for Microsoft increased to $319 billion. Whether revenue materializes depends on the pace at which new capacity comes online; whether valuations hold depends additionally on financing costs, depreciation, and revenue per GW.
Custom silicon is entering the execution phase for revenue, gross margin, and supply security. Amazon’s Trainium is intended to reduce inference costs and improve AWS’s long-term margins; Microsoft needs Maia and AMD chips to reduce its dependence on Nvidia; and Google’s TPU is extending the project cycles of Broadcom, MediaTek, and Global Unichip. Custom silicon is no longer merely a technology-roadmap decision. It determines how much compute cloud providers can procure, the cost of each inference, and whether profits accrue to the cloud platform or upstream GPU vendors.
Power and memory determine the ceiling for expansion. Google’s electricity consumption exceeded 43 TWh, up 37% year over year, while its 24/7 carbon-free energy score remained at 65%.
Amazon does not directly disclose data-center electricity consumption. Barclays estimates it at approximately 90 TWh based on water withdrawals and water-use efficiency. Both companies are improving cooling efficiency, but transmission, grid interconnection, firm power supply, and memory availability remain the real constraints delaying projects.
This week’s key developments fall into four areas.
Cloud demand remains strong; supply and capital efficiency determine the pace of monetization
Cloud Revenue and AI Capex
Amazon offers this week’s clearest example of both the highest capital intensity and the strongest revenue visibility. Goldman Sachs expects AWS revenue growth to remain above 30% over the next two years, with capital investment growing even faster. Investors need to track both backlog conversion and cash flow.
Amazon’s cloud revenue and capital investment continue to rise together.
Amazon’s construction targets push the funding burden into 2027. Third-party data estimates that Amazon had approximately 6.85 GW of data-center capacity in 2025, with around 260 data centers yet to come online.
The company plans to double its existing capacity again by 2027.
Goldman Sachs’ hardware team estimates that each additional 1 GW of data-center capacity requires $50–60 billion, most of which is spent on servers and storage. The lag between cash investment and customer payments is approximately 0.5–2 years.
Backlog can support higher revenue, but the upside scenario should not be treated as the base case. Goldman Sachs’ conversion model assumes that cloud capital investment generates returns over six years and that year-end backlog is recognized over five years, with half converted within the first 24 months. The model indicates approximately 10%–20% upside to AWS revenue, but the report explicitly defines this as an illustrative scenario. If capex estimates continue to rise without a corresponding increase in backlog, returns on investment will deteriorate first.
Free cash flow is the first risk likely to surface at Amazon. Goldman Sachs expects Amazon’s free cash flow to equity to turn negative by $41 billion in 2027, followed by a cumulative shortfall of approximately $70 billion over the subsequent two years. The company’s debt-to-adjusted EBITDA ratio has remained below 1x over the long term, leaving financing capacity available.
Its average cost of debt has already risen from 3.17% to 4.45%. Continued cloud revenue growth can support long-term returns, but near-term valuation will become more sensitive to financing costs and depreciation.
Microsoft’s revenue bottleneck is also on the supply side, but internal compute allocation makes Azure’s growth more difficult to assess. Goldman Sachs expects Azure’s constant-currency growth to reach 40%–41% in the fiscal fourth quarter, slightly above company guidance. New capacity at the Fairwater data center is coming online unevenly. Microsoft must also allocate GPUs among external Azure customers, Copilot, and internal model development, meaning additional compute capacity may not immediately translate into Azure revenue.
Microsoft’s capex upgrades have already exceeded its revenue upgrades.
Revenue per GW is the most important efficiency metric to monitor for Microsoft. Goldman Sachs estimates that it will decline from approximately $12 billion in FY26 to around $10 billion in FY29. The reasons include more compute capacity being retained for internal applications, higher component prices, and new capacity that has yet to reach full utilization. Better Copilot paid conversion, a higher inference mix, and improved chip efficiency could reverse this trend. If capex estimates continue to rise while revenue per GW keeps falling, Azure growth alone will not adequately explain investment returns.
Alibaba Cloud provides a contrasting case in which revenue and margins improve simultaneously. Citi expects Alibaba’s FY1Q27 cloud revenue to reach RMB48.4 billion, up 45% year over year and above its previous 40% forecast.
Cloud EBITA is expected to reach approximately RMB5.6 billion, representing an 11.5% margin. As domestic e-commerce revenue comes under pressure, cloud is becoming an important pillar of earnings growth. The key questions are whether cloud revenue can continue accelerating, whether low-teens margins can be sustained, and whether GPU and memory availability will delay delivery.
Data Centers, Compute Procurement, and Custom Silicon
Data center development has entered a phase of “orders secured, resources constrained.” Google consumed more than 43 TWh of electricity in 2025, with data centers accounting for over 97% of total consumption.
Compute performance per unit of energy increased more than threefold over five years, while electricity consumption rose 37%. Based on this, Barclays estimates that Google’s delivered compute capacity may have grown by approximately 55%–60% annually in recent years.
Google and Amazon face different resource constraints.
The grid is more likely than generation projects to delay commissioning. Google disclosed that transmission, interconnection queues, and administrative approvals can create delays of four to five years between signing a clean-energy contract and actually delivering the electricity to the grid. Advanced geothermal and small modular nuclear reactors could provide reliable carbon-free power, but large-scale commercialization may not occur until the 2030s. Cloud providers can sign power purchase agreements, but cannot independently compress every stage of the interconnection timeline.
Cooling technology can save power and water, but cannot solve the shortage of firm electricity supply. Amazon disclosed that direct liquid cooling can reduce mechanical cooling energy consumption by up to 50% during peak cooling periods. In-rack heat-exchange systems are expected to use approximately 9% less water than conventional evaporative air-cooling designs. These technological improvements can increase compute density within the same campus, but project commissioning still depends on grid access and continuous power supply.
Google’s TPU supply chain is evolving from a single-chip project into a long-duration platform order. Broadcom management confirmed that the TPU v9 roadmap remains on schedule, with volume ramp expected in 2028; under its five-year agreement with Google, Broadcom expects to retain the majority of shipment share. TPUs drive demand not only for compute chips, but also for high-speed SerDes, advanced packaging, and Ethernet switching silicon. Tomahawk 6 is already supply-constrained, indicating that the bottleneck in compute procurement is spreading from accelerator cards to networking.
Custom-silicon projects offer significant revenue elasticity, but supply allocation determines the pace of realization.
Custom silicon enters the delivery phase, with capacity allocation determining revenue elasticity
The value of Amazon Trainium lies in cloud gross margin; it does not need to displace Nvidia to succeed. Goldman Sachs cited Amazon’s shareholder letter as saying that Trainium 2 is essentially sold out, Trainium 3 is nearly fully reserved, and the related chip business has approximately US$20 billion in annualized revenue. Trainium 3 offers approximately 40% better price-performance than the prior generation, making it suitable for more cost-sensitive inference workloads. As long as it absorbs incremental internal AWS demand, it can reduce reliance on externally purchased GPUs and improve long-term incremental margins.
Microsoft’s custom silicon still lags peers, and generational improvements around 2027 will determine whether the gap can narrow. Goldman Sachs believes Maia is less mature than other cloud providers’ solutions, leaving Microsoft more dependent on Nvidia. Maia 200 uses HBM3, while Nvidia Vera Rubin uses HBM4; the memory-bandwidth gap will affect system cost and performance. Microsoft is adding AMD as a second source and expects Maia 300 to incorporate lessons from the first two generations. Future assessment should focus on actual volume production, migration of internal workloads, and revenue per GW—not merely the tape-out node.
Nvidia remains the common denominator in cloud-provider expansion. Morgan Stanley’s management survey indicates that traditional hyperscalers account for approximately half of Nvidia’s revenue, with land and power increasingly constraining incremental growth. Demand from AI clouds, industrial customers, and enterprises has also become a significant component of data center revenue. Nvidia believes the compute value supported by 1 GW will rise from approximately US$30 billion–US$40 billion today to US$100 billion, driven by generational improvements in energy efficiency. This figure represents a long-term efficiency target and should not be treated as near-term revenue guidance.
GPUs and ASICs will grow together. Broadcom believes that XPU and GPU shipments among leading model developers could approach an even split next year. Morgan Stanley also sees both Nvidia’s and Broadcom’s AI businesses growing rapidly while remaining supply-constrained. Cloud providers will use ASICs to lower the cost of stable, large-scale inference workloads, while retaining GPUs for general-purpose training, rapid iteration, and external cloud rental demand. The two architectures are competing for incremental budgets and workload mix, rather than simply replacing one another.
Models, Software, and Application Monetization
This week’s core application-monetization theme is converting existing compute into higher revenue, rather than comparing model capabilities. Amazon’s levers are EC2 pricing, custom silicon, and shopping entry points; Microsoft’s lever is compute allocation between Azure and Copilot; Alibaba Cloud’s levers are enterprise AI tools, data center expansion, and service revenue. All address the same question: can elevated capital expenditure generate sustainable cloud revenue and profits?
EC2 pricing is Amazon’s most direct revenue lever, but contract structures will delay realization. In its scenario analysis, Goldman Sachs assumes a 20% price increase for elastic compute services and estimates that this could generate approximately US$2 billion–US$4 billion in incremental net revenue in the second half of 2026. The business is estimated to account for more than half of AWS revenue, making pricing changes significant. Multi-year Savings Plan prices will not reset immediately, and customers will optimize usage, so this estimate is better viewed as a range of potential sensitivity.
Microsoft needs to demonstrate that Copilot can improve returns per unit of compute. Microsoft will prioritize some GPUs for Copilot and internal R&D;, which will reduce current-period Azure revenue but could generate higher application-layer profits. Goldman Sachs cited more than 20 million Copilot seats in the fiscal third quarter. The next variables to monitor are paid conversion, usage intensity, and whether fair-use terms can cover inference costs. If usage increases without corresponding price adjustments, gross margin will come under pressure.
Alibaba Cloud’s enterprise applications are beginning to scale alongside infrastructure expansion. Alibaba Cloud is expanding data centers in Europe, Malaysia, Japan, and Mexico, bringing its footprint to 32 regions and 105 availability zones. It is also advancing enterprise collaboration, development, and SAP cloud services. Whether the application layer can drive higher margins comes down to two financial metrics: cloud revenue growth and cloud EBITA margin. Citi currently forecasts 45% revenue growth and an 11.5% margin, providing a clear benchmark for the next earnings report.
Divergence Across the M7 and Emerging Cloud Providers
Divergence within the M7 stems first from differences in resource endowments. Amazon has a substantial backlog and a more mature Trainium platform, providing high growth visibility at the cost of the greatest pressure on capital expenditure and free cash flow. Microsoft faces strong Azure demand and is bringing new capacity such as Fairwater online, but in-house chips and internal compute allocation make monetization efficiency more complex. Google leads in TPU capabilities and energy efficiency, but grid interconnection and access to reliable 24/7 clean power constrain its expansion. If Meta begins leasing compute externally, it would improve GPU utilization while making it harder for investors to infer internal demand from capital expenditure alone.
Alibaba Cloud’s advantage is simultaneous improvement in revenue and margins; its weaknesses are supply and competition. Citi raised its FY1Q27 cloud revenue growth forecast to 45% and expects the margin to reach 11.5%. This represents a more verifiable path to profitability than pursuing scale alone. The report also identifies GPU and memory supply, domestic competition, and capital expenditure as key topics for the earnings call, indicating that sustained high growth still depends on supply availability and pricing.
Emerging cloud providers broaden Nvidia’s customer base but introduce new credit risks. Nvidia management highlighted new partnership models with emerging cloud customers involving co-investment, credit support, and revenue sharing. These arrangements can accelerate GPU-cloud expansion and allow Nvidia to capture more upside; however, if end-user utilization is insufficient, the chip supplier will bear greater financing and collection risks. GPU shipments should therefore be assessed alongside emerging-cloud revenue, utilization, and financing terms.
On-premises enterprise deployments will absorb some inference workloads, while the cloud will retain orchestration and elasticity demand. A former Microsoft AI transformation executive observed that enterprises will deploy individual agents on-premises or at the edge for reasons including cost, latency, governance, and data sovereignty, while using the cloud for multi-agent orchestration. Improved energy efficiency and labor savings from new servers can provide budget capacity for hardware purchases. For CSPs, this means inference workloads will become more distributed, and cloud revenue will increasingly depend on hybrid architectures, software governance, and peak compute demand.
Points of Debate, Disconfirming Evidence, and Next Week’s Watchlist
The central debate is how long capital expenditure can continue to run ahead of revenue. The bullish case assumes that backlogs are sufficiently large for new capacity to be monetized as soon as it comes online, while in-house chips and pricing can improve margins. The cautious case assumes that grid and memory constraints will delay deployment, while depreciation and interest expenses hit the income statement before revenue is recognized, weighing on free cash flow and valuation.
The next phase requires verifiable data to determine which path is materializing.
Returns on capital, in-house chips, and power constraints form the core validation framework.
For Amazon, the key question is whether revenue realization can catch up with capital investment. The next financial update should be assessed against AWS growth, backlog, incremental capacity, capital expenditure, and free cash flow. Goldman Sachs’ 10%–20% revenue upside scenario depends on relatively rapid backlog conversion; weakness in any of these metrics would reduce the model’s credibility.
For Microsoft, the focus is Azure guidance and internal compute allocation. The key metrics for the July 29 earnings release are whether Azure constant-currency growth reaches 40%–41%, whether new capacity continues to come online, and whether revenue forecasts keep pace with upward revisions to capital expenditure. Progress in Maia, AMD, and memory procurement will shape the cost curve over the next two years.
For Google and Meta, the focus is how compute capacity is utilized. Google’s key metrics are TPU share, data-center power consumption, grid interconnection, and progress toward 24/7 carbon-free energy. For Meta, the key question is whether external compute services materialize and whether they reflect robust external demand or insufficient internal utilization. The two interpretations carry entirely different implications for GPU procurement and capital expenditure.
For Alibaba Cloud, the focus is growth quality. Citi’s base case calls for 45% cloud revenue growth and an 11.5% cloud EBITA margin in FY1Q27. Revenue above expectations accompanied by margin deterioration would indicate that supply or pricing pressure remains significant; only simultaneous delivery on revenue and margins would demonstrate that enterprise AI and infrastructure investment are beginning to generate sustainable returns.