
404K SEMI-AI 2026-07-11 Memory Weekly — Long-Term Supply Agreements, NAND Upside, and the Countercase from Inference Efficiency
目录
Overall View This Week
Weekly Performance of Memory-Related Securities
DRAM/HBM: Control of Supply, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: AI CPU and Rack-Memory Spillover
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Operating Leverage
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Testing, and Materials: Second-Order Beneficiaries of Memory Capex
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Investment Ranking, Risks, and Disconfirming Evidence
What to Watch Next Week
The memory upcycle has entered a more challenging phase for investors: prices are still rising, but the market is beginning to ask how long the increases can last, whether customers can absorb them, and when new capacity will catch up with demand. DRAM/HBM benefits from customer lock-in and long-term agreements, while NAND/eSSD benefits from enterprise demand and pricing leverage. The nearline HDD thesis rests on data-lake capacity and cash flow. AI inference continues to drive memory and storage demand, but KV-cache compression is reducing hardware consumption per token. Future aggregate demand will depend on whether efficiency gains generate greater usage volumes. Downstream server vendors can still absorb some of the cost increase, but smartphones, PCs, and other price-sensitive hardware have already entered a trade-off among specifications, pricing, and unit sales.
Overall View This Week
Memory remains the most direct beneficiary of earnings upgrades within AI hardware, but the investment debate has shifted from “is there a shortage?” to “who can convert the shortage into sustainable cash flow?” Pricing evidence remained strong this week. UBS raised its forecast for sequential DDR contract-price growth to 32% in 3Q and 18% in 4Q; it raised its NAND forecast to 30% in 3Q and 12% in 4Q. At the same time, Bank of America and TrendForce cautioned that sequential DRAM and NAND price increases would decelerate rapidly after 2Q. Both views can be correct: absolute prices remain high, while the marginal rate of increase is cooling.
HBM and high-end server DRAM remain the highest-conviction assets. The reasons are specific: HBM consumes more wafer capacity, customer qualification is slow, stacking equipment has long lead times, and CSPs are locking in volumes through long-term agreements. Micron’s 2026 HBM output has already been presold, with new orders scheduled through the end of 2027. Some key customers can secure only 50%–67% of their required volumes.
UBS expects DRAM shortages to persist until at least 2Q28 and estimates that bit demand will grow 36.2% in 2027, versus supply growth of only 19.3%. The investment case here rests on customer lock-in, delivery visibility, and a pricing floor; spot-price increases are merely the result.
The greatest upside is shifting toward NAND and enterprise SSDs. Enterprise SSD revenue increased 86.1% to US$18.46 billion in 1Q26, while contract prices rose approximately 80%. SanDisk’s enterprise SSD revenue increased sevenfold year over year, and the company is developing high-bandwidth flash. NAND’s risks are equally clear: the recovery from the pricing trough has been steep, incremental supply can emerge more readily than in HBM, and the pace of price increases could slow materially in 4Q. NAND should therefore be tracked through ASPs, enterprise revenue, and inventory discipline; HBM’s long-term-contract valuation framework cannot be applied directly.
AI inference provides a second growth curve for storage demand, while also presenting the most important countercase. RAG, long-context workloads, agentic AI, and multimodal tasks will continue to generate KV caches, vector databases, checkpoints, and cold data. Google’s TurboQuant can reduce KV-cache memory requirements to one-sixth of their original level and accelerate GPU inference by up to 8x; DeepSeek’s MLA claims to reduce KV-cache usage by 90%–95%. Memory requirements per request may decline, but lower cost per token will also stimulate usage. The key metric to track is “storage consumption per token × total token volume”; compression rates alone cannot determine aggregate demand.
This week’s company ranking can be summarized in three tiers: SK hynix represents HBM certainty; Micron offers combined leverage to HBM and commodity DRAM; Samsung Electronics combines memory profits with downstream cost pressure. SanDisk and Kioxia represent high-beta exposure to NAND/eSSD, while Seagate Technology and Western Digital represent nearline HDD capacity and cash flow. Equipment, testing, and materials are second-order beneficiaries. Orders typically materialize later than memory-price increases, but exposure spans multiple memory categories. Key names include ASML, Lam Research, Advantest, FormFactor, DISCO, and the advanced-packaging materials supply chain.
Weekly Performance of Memory-Related Securities
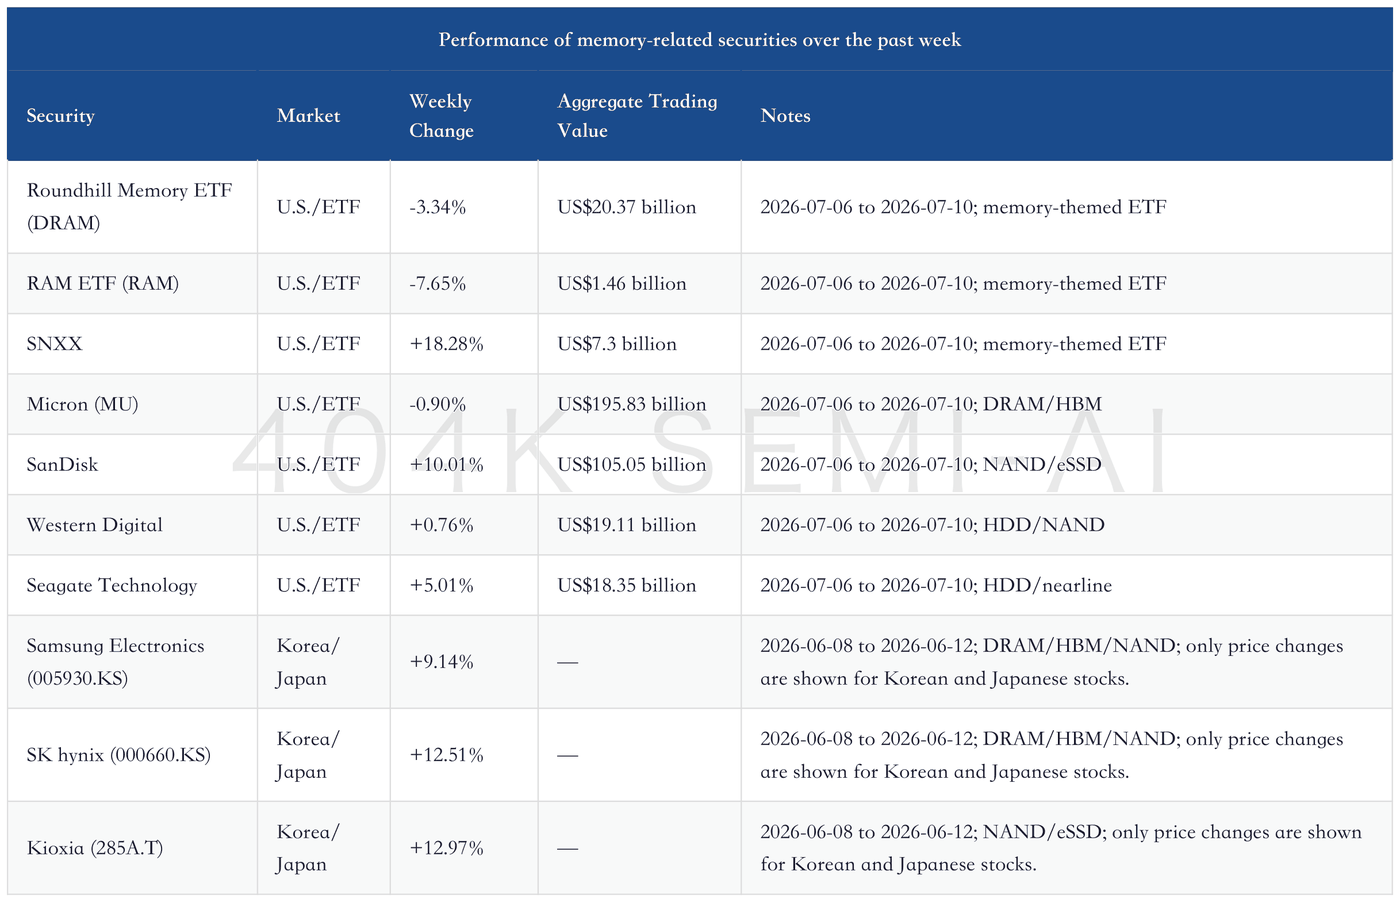
Performance dispersion indicates that capital is beginning to distinguish between certainty and upside. Micron fell 0.90% during the week, while SanDisk gained 10.01% and Seagate Technology rose 5.01%. Returns among thematic ETFs ranged from a 7.65% decline to an 18.28% gain. The market has not abandoned the memory trade as a whole; capital is favoring segments with further earnings-upgrade potential or lower prior valuations.
The observation periods also require attention. U.S. stocks and ETFs use a different period from Korean and Japanese stocks; refer to the notes in the table for the exact dates.
The two sets of returns cannot be used directly to rank same-week relative strength. Korean and Japanese equities can still indicate risk appetite during the preceding period, but the investment ranking in this report is based primarily on industry evidence rather than using non-contemporaneous prices as a substitute for fundamentals.
DRAM/HBM: Control of Supply, Long-Term Agreements, and Customer Qualification
Control of DRAM/HBM supply rests on four barriers: cleanroom capacity, wafer allocation, stacking yields, and customer qualification. HBM production consumes approximately three times as much wafer capacity as conventional DRAM. Once wafers enter production, they must still undergo precision stacking and testing, with relevant equipment lead times of approximately 12 months. Even when fabs expand, incremental wafers cannot immediately become qualified HBM. Micron, Samsung Electronics, and SK hynix therefore prefer to allocate capacity to major customers that can sign long-term agreements, provide prepayments, and jointly define products.
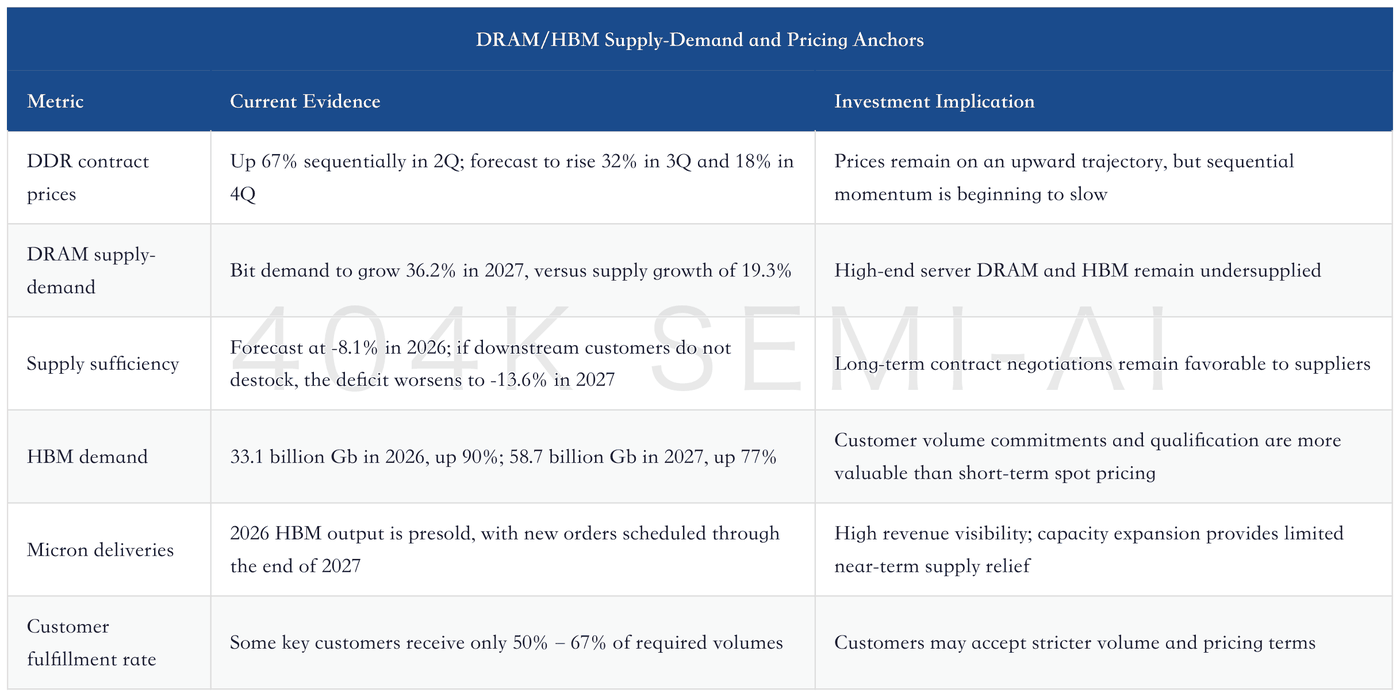
Long-term agreements are changing how profits are recognized in the traditional memory cycle. Micron’s supply agreements include price floors and ceilings. In negotiations with Korean manufacturers, approximately 60%–70% of five-year purchase volumes could combine fixed quantities with fixed prices, while the remainder would use floating prices. Samsung Electronics plans to revise long-term agreements with more major customers and may bind 50%–70% of DDR5 supply to such contracts. Contract enforceability depends on prepayments, deposits, price-reopener clauses, and customers’ financing capacity. Only when both volume and price are constrained can long-term agreements convert cyclical profits into visible cash flow.
SK hynix has the clearest advantage. Its revenue mix is more heavily weighted toward HBM, and it has less exposure to the downstream cost pressure affecting Samsung Electronics’ device businesses. HBM4E requires customized base dies, advanced process nodes, and more complex interconnects. The product is increasingly similar to a jointly designed logic chip and is less commoditized than conventional DRAM. Customers must engage earlier in development and secure supply, bringing SK hynix closer to “selling qualification and delivery certainty” and giving it stronger valuation support than exposure to commodity price increases alone.
Micron offers greater upside but is also more dependent on the cycle. It benefits from both presold HBM and conventional DRAM price increases, while launching a ¥1.5 trillion expansion in Hiroshima targeting advanced DRAM and HBM. The Japanese government will provide up to ¥500 billion in support, but the project is not expected to begin HBM shipments until around summer 2028. The added capacity will have limited impact on near-term supply and demand but will enter global supply competition after 2028. Key validation metrics for Micron are HBM market share, conventional DRAM ASPs, long-term-agreement coverage, and expansion yields.
Samsung Electronics has the strongest memory profits but also the clearest downstream offset. Production of its 4nm HBM4 base die is ramping, with related process yields of approximately 80%.
After fab utilization improved, the foundry business achieved its first monthly profit since 2023 in June 2026.
HBM improves utilization across memory, foundry, and advanced packaging. However, rising DRAM prices also increase the cost of smartphones, PCs, home appliances, and servers. For every increment of upstream profit Samsung Electronics earns, its device businesses may give some back through price increases, specification reductions, or weaker unit sales. Group-level earnings leverage is therefore less pure than at an HBM-focused leader.
Expectations for hybrid bonding should be moderated. As thickness tolerances increase, mainstream products can continue using thermocompression bonding, and Samsung Electronics and SK hynix may defer hybrid bonding further.
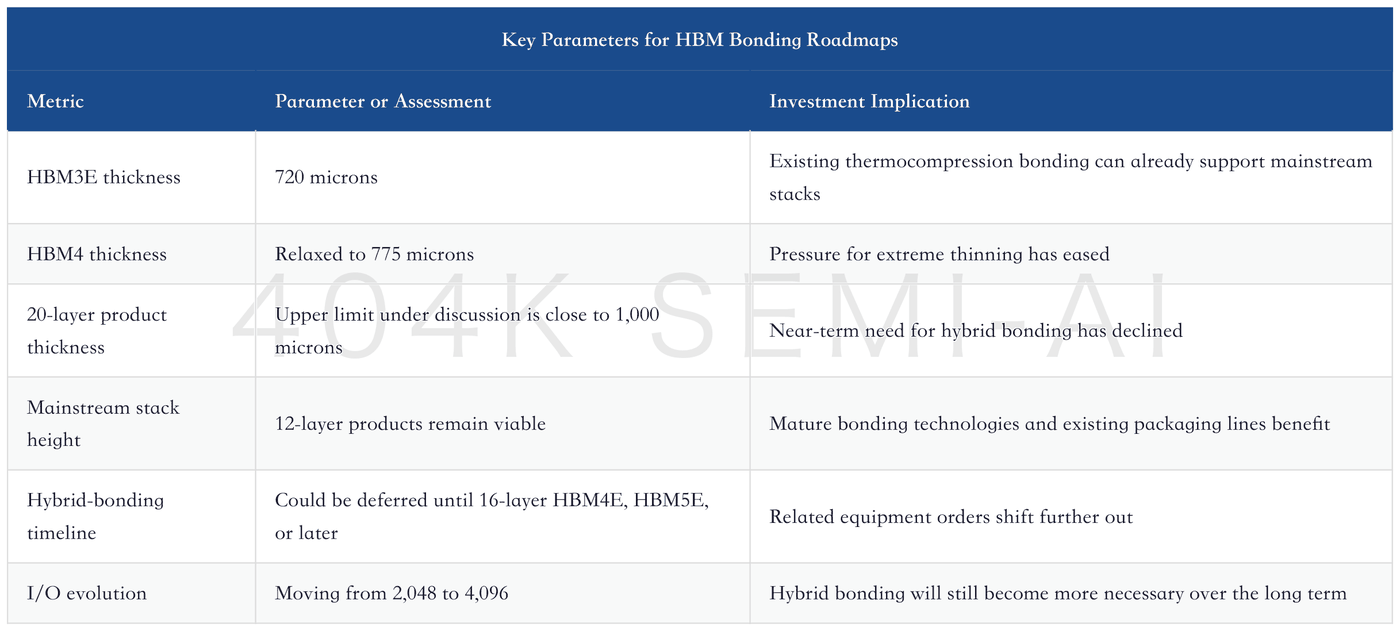
There are three invalidation conditions for this section. First, long-term agreements prove to be merely expressions of intent, with prices and purchase volumes easily reopened. Second, CSP financing capacity declines and customers proactively reduce purchases due to pressure on total capital expenditure. Third, incremental wafers, stacking equipment, and yields improve simultaneously around 2028, allowing supply to catch up with demand faster than expected. If any of these occurs, the scarcity premium for HBM and server DRAM will narrow.
LPDDR/SoCAMM: AI CPU and Rack-Memory Spillover
SoCAMM’s investment value comes from rack-level memory capacity and power efficiency, not novel specifications at the individual-chip level. AI CPUs, ASICs, and accelerators require larger main-memory pools for model parameters, KV cache, data preprocessing, and inter-node scheduling. HBM provides high bandwidth close to the compute chip, while SoCAMM and server DRAM provide higher-capacity, lower-power system memory. Both must expand together to convert expensive GPU time into useful tokens.
The strongest evidence this week came from CSPs locking in server DRAM and SoCAMM supply. Samsung Electronics, SK hynix, and Micron are reallocating cleanroom capacity and advanced DRAM resources toward HBM, DDR5, and server products, reducing consumer DRAM availability.
AWS again raised its third-quarter ASIC server shipment forecast by 20%–30%, with volume production of Trainium 3 rack-scale systems scheduled for July. The previous generation has already sold out, and the new generation is also close to fully booked. The expansion of custom ASICs has not bypassed memory; instead, it has increased demand for high-capacity, low-power rack memory.
The LPDDR spillover thesis depends more heavily on downstream product choices. Premium AI PCs, edge inference, and certain server form factors require higher-bandwidth, lower-power memory, but currently verifiable data do not yet cover standalone LPDDR pricing, shipments, or customer qualifications. As AI servers absorb high-end DRAM resources, consumer and edge products will face tighter supply and higher procurement costs. Whether LPDDR can become a standalone earnings driver will require direct evidence from OEM configurations, contract pricing, and supplier shares.
SoCAMM also faces two categories of risk. First, memory controllers, software stacks, and rack designs for CPUs and ASICs could still change per-node configurations; specification upgrades may not translate into proportional increases in unit value. Second, CXL memory pooling can reallocate idle capacity to hosts that need it, improving utilization. Server installations will continue to grow, but the physical redundancy required for each workload could decline. Investors should prioritize suppliers that have already entered customer qualification and long-term agreements, and avoid paying premiums for unconfirmed specification narratives.
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Operating Leverage
NAND/eSSD demand has expanded from training data to inference state. RAG requires storage for vector indexes and document repositories, while long-context models and agents require more frequent reads and writes of KV cache, checkpoints, logs, and session state. Data lakes must also retain large volumes of colder content. HBM and DRAM handle data needed immediately; enterprise SSDs handle data needed soon and requiring low-latency retrieval; nearline HDDs serve the colder, higher-capacity tier.
Enterprise SSD fundamentals are stronger than those of consumer NAND. Enterprise SSD revenue rose 86.1% to $18.46 billion in the first quarter of 2026, while contract prices increased by approximately 80%. Sandisk’s enterprise SSD revenue increased sevenfold year over year, and the company plans to advance high-bandwidth flash.
Product upgrades are also materializing. Micron demonstrated the PCIe Gen6 9650 data-center SSD. Kioxia’s tenth-generation BiCS FLASH increases bit density by 60% and interface speed to 4.8 Gb/s while reducing power consumption. Customers are willing to pay for throughput, latency, power efficiency, and reliability, allowing enterprise products to partially escape pure bit-price competition.
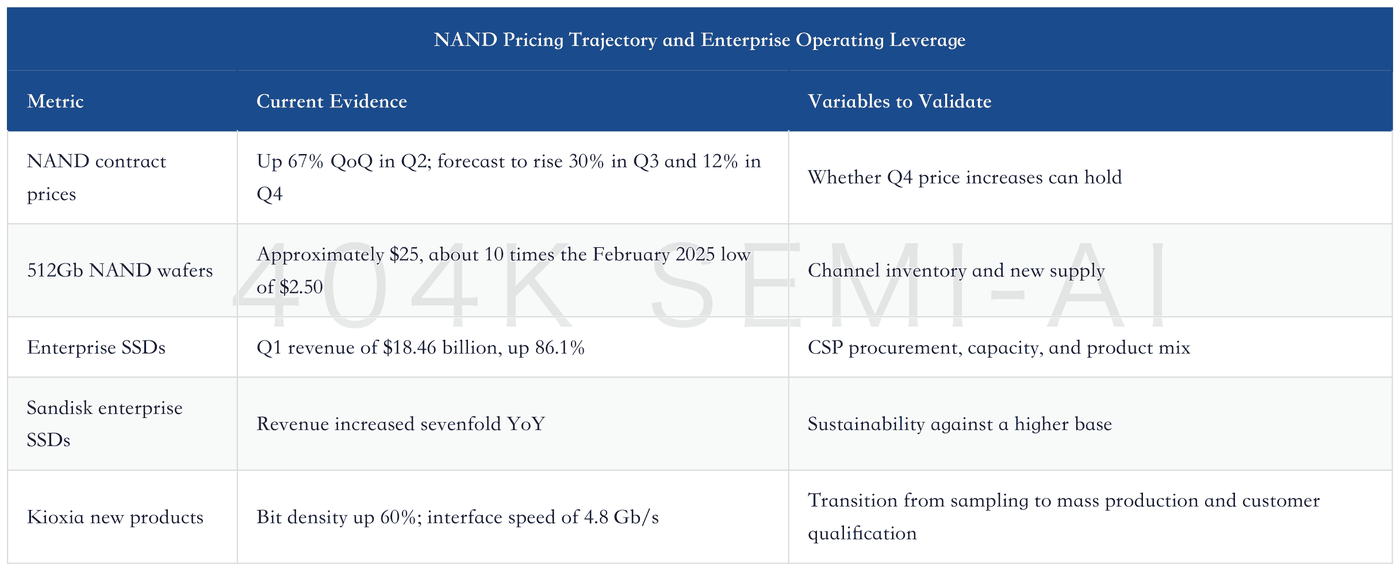
NAND’s greatest risk is that supply constraints are less stringent than in HBM. TrendForce previously lowered its forecast for second-quarter NAND ASP growth from 70%–75% to 55%–60%.
Bank of America projects a steeper deceleration, with sequential price increases of 65%, 13%, and 1% in the second, third, and fourth quarters, respectively. Prices may continue to rise, but incremental profit gains could diminish rapidly. If high margins prompt suppliers to relax capital discipline, NAND will return to inventory and price competition sooner than HBM.
Sandisk and Kioxia offer high operating leverage and should be valued against enterprise revenue, ASPs, product qualifications, and capital-expenditure discipline. Sandisk gained 10.01% this week, indicating that the market has begun pricing in earnings upgrades from enterprise SSDs and high-bandwidth flash. Kioxia’s key drivers are next-generation BiCS, its enterprise product mix, and supply discipline. Both companies must guard against an excessively rapid recovery in consumer NAND that could dilute enterprise improvements, as well as customers reducing SSD demand per task through compression, tiered storage, and higher utilization.
AI inference efficiency is the most important counterargument in this section. CMX, CXL, TurboQuant, and MLA all reduce recomputation, data duplication, and idle capacity. Efficiency gains reduce memory and SSD consumption per inference, but they may also lower inference costs and drive more applications, users, and tokens. Demand analysis should separate three metrics: storage usage per token, total token volume, and the tiering ratio between hot and cold data. Looking only at model context length risks overstating actual physical-storage demand.
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
The advantage of nearline HDDs is their low cost for storing massive volumes of cold data. AI data lakes will continue accumulating raw corpora, video, images, logs, training versions, checkpoints, and compliance backups, most of which do not require SSD-level latency. Bank of America expects storage exabyte growth to exceed 25% over the next three to five years, driven by AI training, inference, cloud uploads, and physical AI. As long as data generation outpaces deletion and compression, nearline HDDs will remain essential assets in the high-capacity tier.
The HDD investment framework differs from that of NAND. NAND is a play on ASP leverage and product mix, while HDD depends more on supply discipline in a duopoly, build-to-order production, nearline exabyte shipments, and free cash flow. Build-to-order production reduces channel inventory and price undercutting, while higher-capacity drives lower customers’ total cost of ownership per terabyte. Investors should require Seagate Technology and Western Digital to convert capacity growth into gross profit, cash generation, and capital returns, rather than merely pursuing higher platter volumes.
Currently verifiable data do not yet cover new nearline HDD orders, capacity per drive, or free cash flow, so operating strength cannot be inferred from share-price performance. Seagate Technology gained 5.01% this week, while Western Digital rose 0.76%. This only indicates that trading sentiment favored Seagate Technology; it does not directly prove that a gap has emerged in orders or cash flow. Subsequent validation must focus on nearline exabytes, average capacity per drive, build-to-order coverage, inventory turnover, and free cash flow.
The counterarguments to the HDD thesis are also clear. Data deduplication, compression, and lifecycle management reduce the physical footprint of cold data. Nearline growth would slow if enterprises place more hot data on SSDs and reduce long-term retention. Insufficient yield improvements for high-capacity drives could also delay deliveries and raise costs. The HDD thesis requires simultaneous improvement in exabyte growth, supply discipline, and cash flow; without all three, it remains merely a capacity story.
Equipment, Testing, and Materials: Second-Order Beneficiaries of Memory Capex
Opportunities in equipment, testing, and materials arise from two drivers: wafer capacity expansion and the increasing manufacturing complexity of each memory device. Micron’s Hiroshima project and new Korean fabs are pushing advanced DRAM, HBM, and NAND capacity additions into 2027–2030.
Near-term pricing is determined primarily by legacy capacity and long-term agreements. Equipment revenue materializes later, following fab construction, tool installation, yield ramp-up, and process complexity, but may also persist for longer.
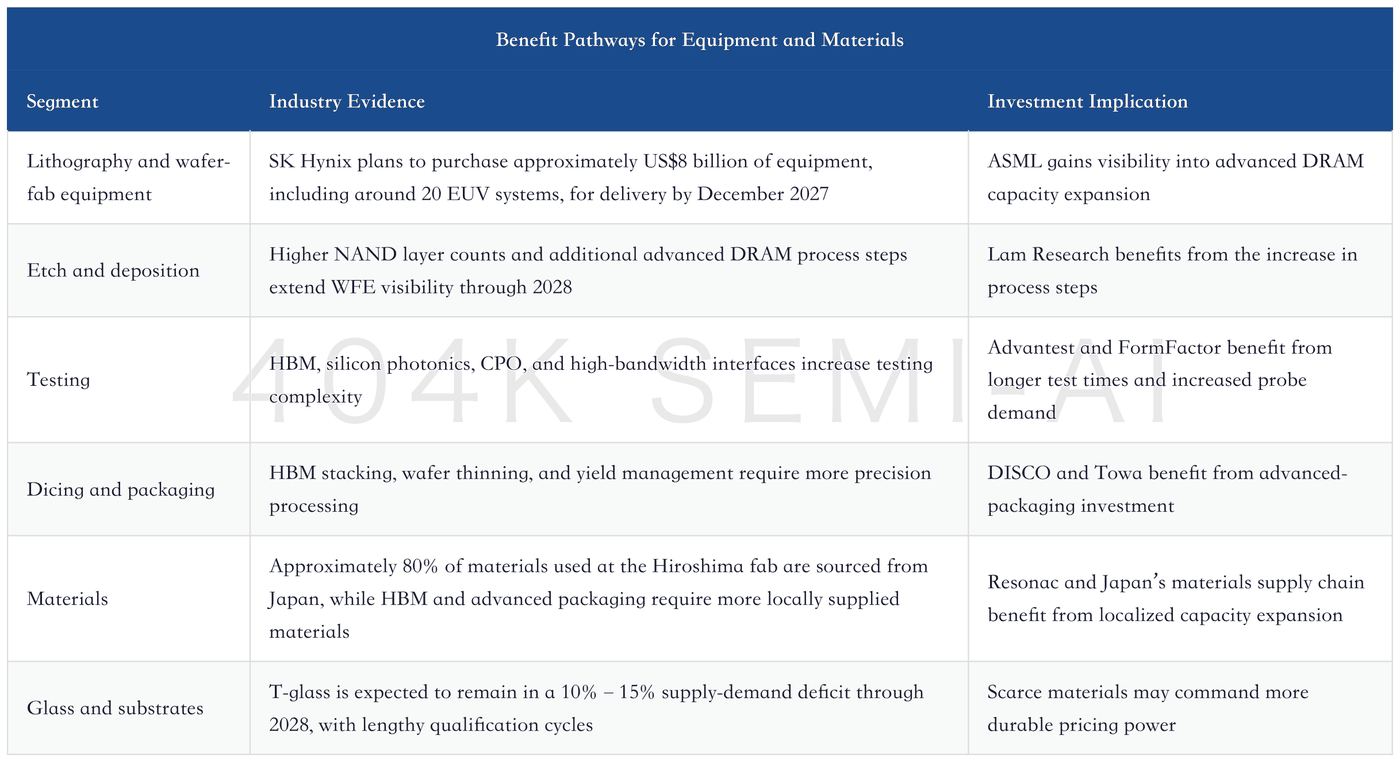
The equipment chain cannot be assessed solely on aggregate capital expenditure. If HBM hybrid bonding continues to be delayed, related equipment orders may arrive later than the market expects. Continued use of thermocompression bonding for 12-layer products would extend the lifecycle of mature packaging tools. If high margins trigger unconstrained NAND expansion, equipment suppliers will benefit from near-term orders, while incremental supply will depress memory manufacturers’ medium-term profits. Equipment and memory stocks can rise simultaneously, but their long-term interests are not fully aligned.
Testing offers greater certainty than a bet on any single technology path. As HBM layer counts, I/O, base dies, and thermal management become more complex, test duration and failure analysis become increasingly important. PCIe Gen6 enterprise SSDs, high-bandwidth flash, and silicon photonics also increase interface-testing difficulty.
FormFactor reported first-quarter 2026 revenue of US$226 million, up 32% year on year, and EPS of US$0.56, above the US$0.44 consensus estimate, indicating that testing demand has already begun to translate into financial results. The risks are that customers develop testing capabilities in-house, yields mature rapidly, and higher equipment utilization reduces demand for incremental systems.
The materials moat lies in qualification lead times. Approximately 80% of materials used at the Hiroshima fab are sourced from Japan, so capacity expansion will initially benefit suppliers already within the supply system. T-glass, low-dielectric glass, CMP materials, electroplating additives, and advanced-packaging chemicals all require lengthy validation. New suppliers can build capacity but cannot bypass customer qualification. Materials companies should be evaluated based on initial volume shipments and customer share, not merely announced investment amounts.
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Rising memory prices are reshaping downstream bills of materials. Servers can absorb some of the cost through higher compute utilization and AI service revenue, while smartphones, PCs, EVs, and other durable goods depend more heavily on consumers’ ability to pay. The “chip inflation” narrative—DRAM prices rising more than sixfold within a year—has spread from the memory industry to end markets. Brands have only three options: raise prices, reduce specifications, or compress gross margins.
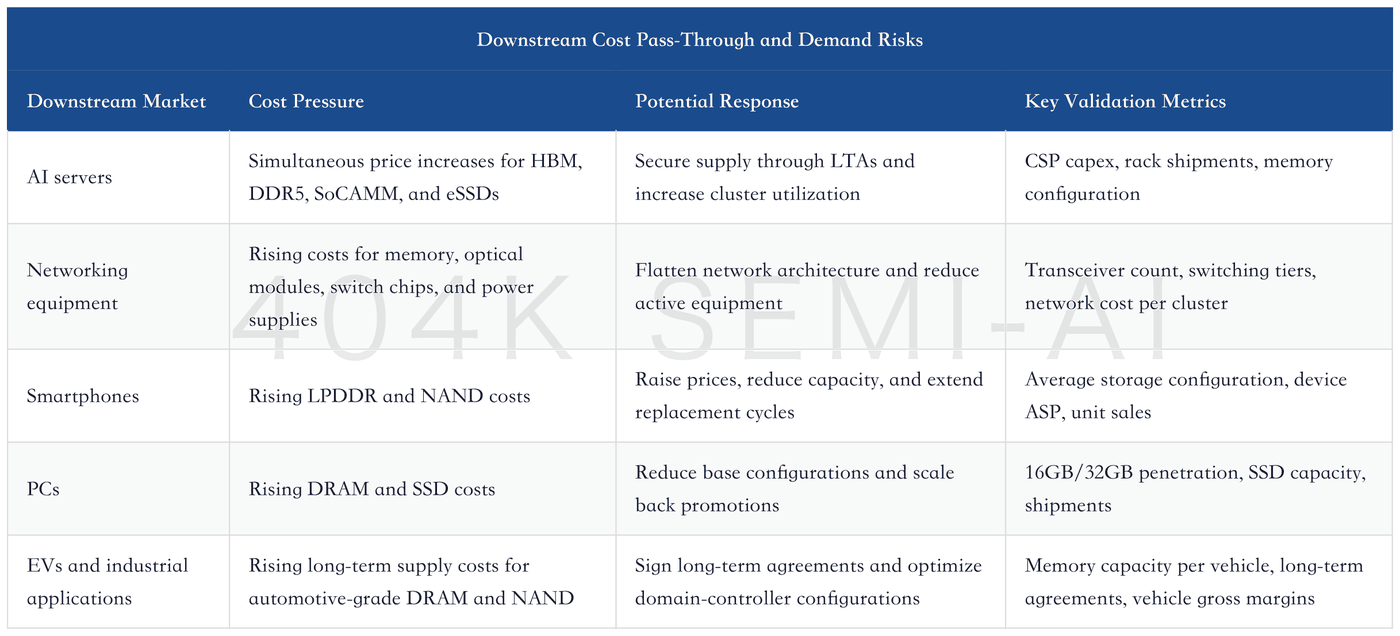
AI servers have the greatest capacity to absorb these costs, but funding constraints cannot be ignored. The five largest hyperscalers’ aggregate capital expenditure has already exceeded their combined operating cash flow, while the four largest US technology companies’ 2026 capex is expected to rise approximately 80% year on year. When power, GPUs, networking, storage, and construction costs all increase simultaneously, customers will prioritize the scarcest GPUs and HBM, then reduce spending on general-purpose servers, network tiers, or redundant configurations. Long-term agreements protect memory manufacturers’ revenue but also turn customers’ ability to pay into a systemic risk for memory stocks.
Network architecture optimization may reduce some memory and interconnect demand. The flattened architectures of Amazon RNG and OpenAI MRC are estimated to potentially reduce active networking equipment by more than 60% and transceiver counts by 40%–50%. These forecasts remain disputed, while delays to CPO and Kyber could extend the window for pluggable optical modules. Nevertheless, the direction warrants attention: customers will use system design to offset hardware inflation. Memory pooling, cache compression, and fewer network hops all pursue the same objective—raising the effective utilization of expensive hardware.
Smartphones and PCs are the most vulnerable to demand destruction. Higher memory prices will first raise prices for high-capacity models, then force entry-level products to reduce DRAM or NAND configurations. Lenovo’s adoption of Yangtze Memory Technologies SSDs in laptops sold globally shows that brands are also diversifying suppliers to control costs. Alternative supply can ease procurement pressure but will also weaken overseas NAND manufacturers’ pricing power in consumer markets. Key indicators include whether base capacities stop increasing, device prices rise, and replacement cycles lengthen.
EV and industrial customers place greater value on long-term supply. Micron has signed a long-term automotive memory supply agreement with Ford and described it as one of several such agreements. Automotive qualification and long product lifecycles support contract stability but cannot fully insulate customers from pricing pressure. If vehicle gross margins come under pressure, customers may optimize domain controllers, reduce redundancy, or defer advanced driver-assistance configurations. Memory manufacturers must demonstrate that long-term agreements can lock in both volume and pricing without pushing downstream customers toward more aggressive specification reductions.
Investment Ranking, Risks, and Disconfirming Evidence
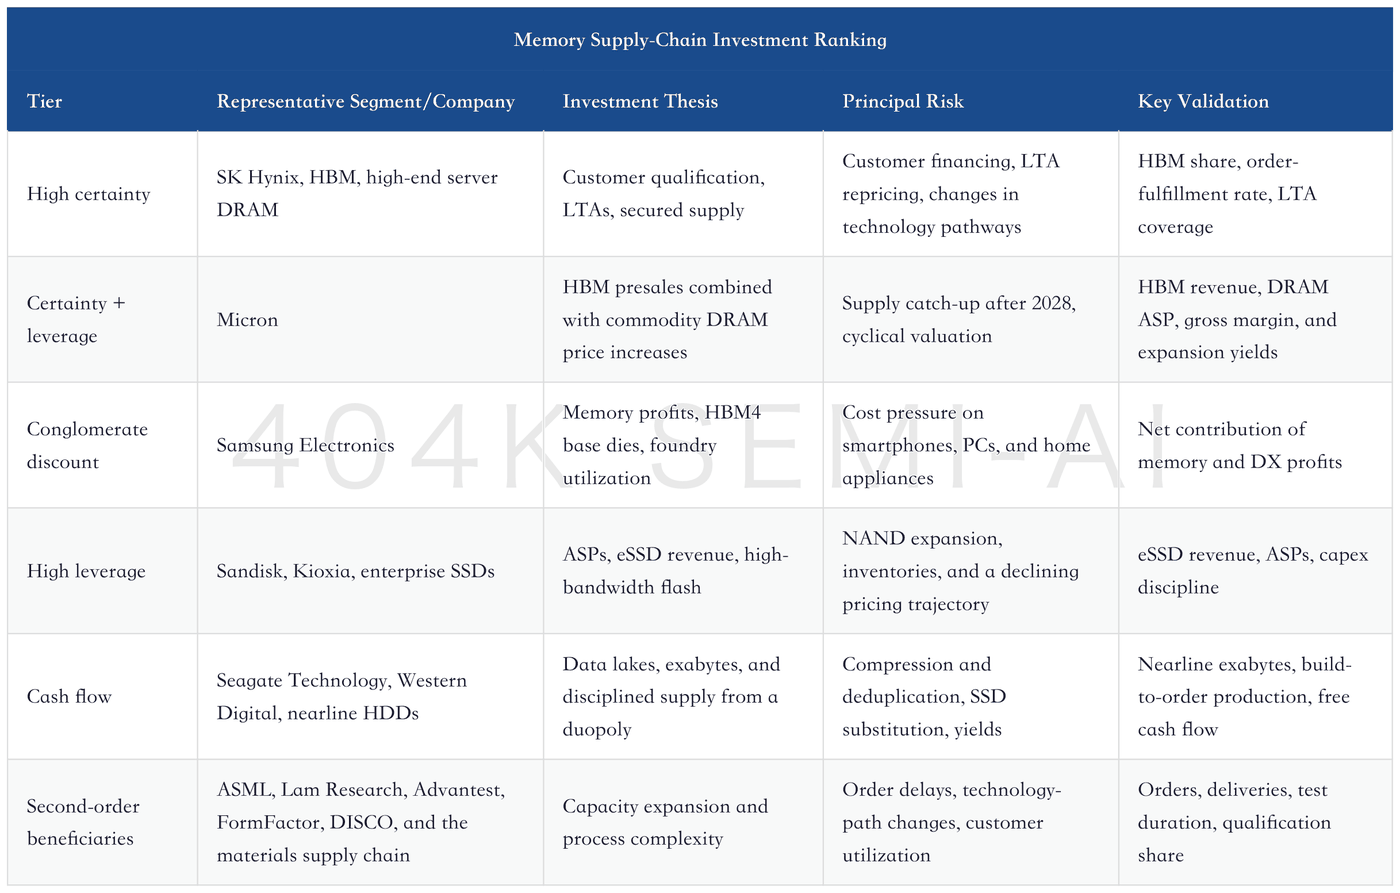
Investment ranking should prioritize certainty, followed by earnings leverage, and finally cash flow. The first tier comprises HBM and high-end DRAM, with SK Hynix preferred, followed by Micron; Samsung Electronics requires an offset for the adverse impact on its end-device businesses. The second tier is NAND/eSSDs, where Sandisk and Kioxia offer greater earnings leverage but also carry higher pricing and inventory risk. The third tier is nearline HDDs, where Seagate Technology and Western Digital must validate the thesis through exabyte shipments, build-to-order discipline, and free cash flow. The fourth tier comprises equipment, testing, and materials, with preference given to segments that have already secured orders, entered qualification, or benefit from increasing process complexity.
The first disconfirming indicator is that LTAs may not be sufficiently binding. If contracts allow customers to cancel, defer, or renegotiate pricing easily, purported long-term visibility remains merely an optimistic indication at the top of the cycle. Investors should monitor prepayments, deposits, minimum purchase commitments, pricing floors and ceilings, and default provisions—not merely count the number of agreements signed.
The second is active downstream specification reduction. If base memory capacities in smartphones and PCs stop increasing, servers reduce redundancy, or EVs defer advanced computing configurations, upstream pricing has already begun to damage demand. Memory manufacturers’ pricing power is valuable only if customer unit sales and product specifications remain materially intact.
The third is unconstrained NAND expansion. Several institutions have already lowered their forecasts for the pace of NAND price increases, which may slow to the low single digits in the fourth quarter. If suppliers simultaneously increase capital expenditure, bit growth, and channel inventories, the structural improvement in enterprise SSDs could be overwhelmed by declining commodity prices.
The fourth is KV-cache and system-efficiency improvement outpacing token growth. TurboQuant, MLA, CXL, and tiered caching will reduce the physical capacity required per workload. If total token volume does not expand correspondingly, inference-storage demand will fall short of the market’s linear extrapolation. Investors should continuously compare cost per token, inference-call volumes, cache hit rates, and enterprise SSD configurations.
The fifth is crowded positioning and interest-rate disruption. Some products tracking SK Hynix, Samsung Electronics, and memory themes have already grown larger than the underlying stocks’ average daily trading volume, indicating increasing position concentration. High interest rates reduce the valuation of long-dated earnings and raise financing costs for hyperscalers and data-center operators. Even if fundamentals remain strong, memory stocks may still experience substantial drawdowns due to positioning, exchange rates, and interest rates.
What to Watch Next Week
Start with long-term contract details. Contract coverage, fixed volume/price ratios, prepayments, and price-reopener clauses at Samsung Electronics, SK hynix, and Micron will determine whether control over supply can translate into cash flow.
Next, monitor the pricing trajectory. DDR and NAND prices are still expected to rise in the third quarter. The focus should be on comparing actual transaction prices with forecasts of 32% and 30% increases, respectively, and assessing whether fourth-quarter quotes continue to be revised down.
Track HBM customer fulfillment rates. If key customers continue to receive only 50%–67% of requested volumes, suppliers’ pricing power will persist. If fulfillment rates improve rapidly, the duration of the shortage will need to be reassessed.
Track enterprise SSDs. Enterprise revenue, PCIe Gen6 qualification, and high-bandwidth flash qualification at SanDisk, Kioxia, and Micron will determine whether NAND can shift from price recovery to a product-mix upgrade.
Track four nearline HDD metrics: exabyte shipments, average capacity per drive, build-to-order coverage, and free cash flow. Capacity growth without improved cash flow is insufficient to support higher valuations.
Track order conversion for semiconductor equipment. ASML’s EUV deliveries, Lam Research’s memory-equipment demand, test-equipment orders at Advantest and FormFactor, and delivery trends at DISCO and packaging-material suppliers will indicate whether memory capex is beginning to spread upstream.
Track AI inference efficiency. Real-world deployment of TurboQuant, MLA, CXL, and tiered caching will determine memory and SSD consumption per token. At the same time, monitor whether lower costs drive faster growth in total token volumes.
Track downstream demand destruction. Base memory configurations in smartphones and PCs, server-rack shipments, advanced compute configurations in EVs, and CSP capex will ultimately determine whether memory price increases can continue to pass through.
Related Reading
404K SEMI-AI 2026-07-05 Storage Weekly — AI Inference Memory, NAND/eSSD, Nearline HDD
404K Technology Weekly 2026-07-04 — Memory Pricing Power, Compute Assetization, Hardware Bottlenecks Spreading404K SEMI-AI 2026-07-11 Memory Weekly — Long-Term Supply Agreements, NAND Upside, and the Countercase from Inference Efficiency
目录
Overall View This Week
Weekly Performance of Memory-Related Securities
DRAM/HBM: Control of Supply, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: AI CPU and Rack-Memory Spillover
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Operating Leverage
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Testing, and Materials: Second-Order Beneficiaries of Memory Capex
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Investment Ranking, Risks, and Disconfirming Evidence
What to Watch Next Week
The memory upcycle has entered a more challenging phase for investors: prices are still rising, but the market is beginning to ask how long the increases can last, whether customers can absorb them, and when new capacity will catch up with demand. DRAM/HBM benefits from customer lock-in and long-term agreements, while NAND/eSSD benefits from enterprise demand and pricing leverage. The nearline HDD thesis rests on data-lake capacity and cash flow. AI inference continues to drive memory and storage demand, but KV-cache compression is reducing hardware consumption per token. Future aggregate demand will depend on whether efficiency gains generate greater usage volumes. Downstream server vendors can still absorb some of the cost increase, but smartphones, PCs, and other price-sensitive hardware have already entered a trade-off among specifications, pricing, and unit sales.
Overall View This Week
Memory remains the most direct beneficiary of earnings upgrades within AI hardware, but the investment debate has shifted from “is there a shortage?” to “who can convert the shortage into sustainable cash flow?” Pricing evidence remained strong this week. UBS raised its forecast for sequential DDR contract-price growth to 32% in 3Q and 18% in 4Q; it raised its NAND forecast to 30% in 3Q and 12% in 4Q. At the same time, Bank of America and TrendForce cautioned that sequential DRAM and NAND price increases would decelerate rapidly after 2Q. Both views can be correct: absolute prices remain high, while the marginal rate of increase is cooling.
HBM and high-end server DRAM remain the highest-conviction assets. The reasons are specific: HBM consumes more wafer capacity, customer qualification is slow, stacking equipment has long lead times, and CSPs are locking in volumes through long-term agreements. Micron’s 2026 HBM output has already been presold, with new orders scheduled through the end of 2027. Some key customers can secure only 50%–67% of their required volumes.
UBS expects DRAM shortages to persist until at least 2Q28 and estimates that bit demand will grow 36.2% in 2027, versus supply growth of only 19.3%. The investment case here rests on customer lock-in, delivery visibility, and a pricing floor; spot-price increases are merely the result.
The greatest upside is shifting toward NAND and enterprise SSDs. Enterprise SSD revenue increased 86.1% to US$18.46 billion in 1Q26, while contract prices rose approximately 80%. SanDisk’s enterprise SSD revenue increased sevenfold year over year, and the company is developing high-bandwidth flash. NAND’s risks are equally clear: the recovery from the pricing trough has been steep, incremental supply can emerge more readily than in HBM, and the pace of price increases could slow materially in 4Q. NAND should therefore be tracked through ASPs, enterprise revenue, and inventory discipline; HBM’s long-term-contract valuation framework cannot be applied directly.
AI inference provides a second growth curve for storage demand, while also presenting the most important countercase. RAG, long-context workloads, agentic AI, and multimodal tasks will continue to generate KV caches, vector databases, checkpoints, and cold data. Google’s TurboQuant can reduce KV-cache memory requirements to one-sixth of their original level and accelerate GPU inference by up to 8x; DeepSeek’s MLA claims to reduce KV-cache usage by 90%–95%. Memory requirements per request may decline, but lower cost per token will also stimulate usage. The key metric to track is “storage consumption per token × total token volume”; compression rates alone cannot determine aggregate demand.
This week’s company ranking can be summarized in three tiers: SK hynix represents HBM certainty; Micron offers combined leverage to HBM and commodity DRAM; Samsung Electronics combines memory profits with downstream cost pressure. SanDisk and Kioxia represent high-beta exposure to NAND/eSSD, while Seagate Technology and Western Digital represent nearline HDD capacity and cash flow. Equipment, testing, and materials are second-order beneficiaries. Orders typically materialize later than memory-price increases, but exposure spans multiple memory categories. Key names include ASML, Lam Research, Advantest, FormFactor, DISCO, and the advanced-packaging materials supply chain.
Weekly Performance of Memory-Related Securities
Performance dispersion indicates that capital is beginning to distinguish between certainty and upside. Micron fell 0.90% during the week, while SanDisk gained 10.01% and Seagate Technology rose 5.01%. Returns among thematic ETFs ranged from a 7.65% decline to an 18.28% gain. The market has not abandoned the memory trade as a whole; capital is favoring segments with further earnings-upgrade potential or lower prior valuations.
The observation periods also require attention. U.S. stocks and ETFs use a different period from Korean and Japanese stocks; refer to the notes in the table for the exact dates.
The two sets of returns cannot be used directly to rank same-week relative strength. Korean and Japanese equities can still indicate risk appetite during the preceding period, but the investment ranking in this report is based primarily on industry evidence rather than using non-contemporaneous prices as a substitute for fundamentals.
DRAM/HBM: Control of Supply, Long-Term Agreements, and Customer Qualification
Control of DRAM/HBM supply rests on four barriers: cleanroom capacity, wafer allocation, stacking yields, and customer qualification. HBM production consumes approximately three times as much wafer capacity as conventional DRAM. Once wafers enter production, they must still undergo precision stacking and testing, with relevant equipment lead times of approximately 12 months. Even when fabs expand, incremental wafers cannot immediately become qualified HBM. Micron, Samsung Electronics, and SK hynix therefore prefer to allocate capacity to major customers that can sign long-term agreements, provide prepayments, and jointly define products.
Long-term agreements are changing how profits are recognized in the traditional memory cycle. Micron’s supply agreements include price floors and ceilings. In negotiations with Korean manufacturers, approximately 60%–70% of five-year purchase volumes could combine fixed quantities with fixed prices, while the remainder would use floating prices. Samsung Electronics plans to revise long-term agreements with more major customers and may bind 50%–70% of DDR5 supply to such contracts. Contract enforceability depends on prepayments, deposits, price-reopener clauses, and customers’ financing capacity. Only when both volume and price are constrained can long-term agreements convert cyclical profits into visible cash flow.
SK hynix has the clearest advantage. Its revenue mix is more heavily weighted toward HBM, and it has less exposure to the downstream cost pressure affecting Samsung Electronics’ device businesses. HBM4E requires customized base dies, advanced process nodes, and more complex interconnects. The product is increasingly similar to a jointly designed logic chip and is less commoditized than conventional DRAM. Customers must engage earlier in development and secure supply, bringing SK hynix closer to “selling qualification and delivery certainty” and giving it stronger valuation support than exposure to commodity price increases alone.
Micron offers greater upside but is also more dependent on the cycle. It benefits from both presold HBM and conventional DRAM price increases, while launching a ¥1.5 trillion expansion in Hiroshima targeting advanced DRAM and HBM. The Japanese government will provide up to ¥500 billion in support, but the project is not expected to begin HBM shipments until around summer 2028. The added capacity will have limited impact on near-term supply and demand but will enter global supply competition after 2028. Key validation metrics for Micron are HBM market share, conventional DRAM ASPs, long-term-agreement coverage, and expansion yields.
Samsung Electronics has the strongest memory profits but also the clearest downstream offset. Production of its 4nm HBM4 base die is ramping, with related process yields of approximately 80%.
After fab utilization improved, the foundry business achieved its first monthly profit since 2023 in June 2026.
HBM improves utilization across memory, foundry, and advanced packaging. However, rising DRAM prices also increase the cost of smartphones, PCs, home appliances, and servers. For every increment of upstream profit Samsung Electronics earns, its device businesses may give some back through price increases, specification reductions, or weaker unit sales. Group-level earnings leverage is therefore less pure than at an HBM-focused leader.
Expectations for hybrid bonding should be moderated. As thickness tolerances increase, mainstream products can continue using thermocompression bonding, and Samsung Electronics and SK hynix may defer hybrid bonding further.
There are three invalidation conditions for this section. First, long-term agreements prove to be merely expressions of intent, with prices and purchase volumes easily reopened. Second, CSP financing capacity declines and customers proactively reduce purchases due to pressure on total capital expenditure. Third, incremental wafers, stacking equipment, and yields improve simultaneously around 2028, allowing supply to catch up with demand faster than expected. If any of these occurs, the scarcity premium for HBM and server DRAM will narrow.
LPDDR/SoCAMM: AI CPU and Rack-Memory Spillover
SoCAMM’s investment value comes from rack-level memory capacity and power efficiency, not novel specifications at the individual-chip level. AI CPUs, ASICs, and accelerators require larger main-memory pools for model parameters, KV cache, data preprocessing, and inter-node scheduling. HBM provides high bandwidth close to the compute chip, while SoCAMM and server DRAM provide higher-capacity, lower-power system memory. Both must expand together to convert expensive GPU time into useful tokens.
The strongest evidence this week came from CSPs locking in server DRAM and SoCAMM supply. Samsung Electronics, SK hynix, and Micron are reallocating cleanroom capacity and advanced DRAM resources toward HBM, DDR5, and server products, reducing consumer DRAM availability.
AWS again raised its third-quarter ASIC server shipment forecast by 20%–30%, with volume production of Trainium 3 rack-scale systems scheduled for July. The previous generation has already sold out, and the new generation is also close to fully booked. The expansion of custom ASICs has not bypassed memory; instead, it has increased demand for high-capacity, low-power rack memory.
The LPDDR spillover thesis depends more heavily on downstream product choices. Premium AI PCs, edge inference, and certain server form factors require higher-bandwidth, lower-power memory, but currently verifiable data do not yet cover standalone LPDDR pricing, shipments, or customer qualifications. As AI servers absorb high-end DRAM resources, consumer and edge products will face tighter supply and higher procurement costs. Whether LPDDR can become a standalone earnings driver will require direct evidence from OEM configurations, contract pricing, and supplier shares.
SoCAMM also faces two categories of risk. First, memory controllers, software stacks, and rack designs for CPUs and ASICs could still change per-node configurations; specification upgrades may not translate into proportional increases in unit value. Second, CXL memory pooling can reallocate idle capacity to hosts that need it, improving utilization. Server installations will continue to grow, but the physical redundancy required for each workload could decline. Investors should prioritize suppliers that have already entered customer qualification and long-term agreements, and avoid paying premiums for unconfirmed specification narratives.
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Operating Leverage
NAND/eSSD demand has expanded from training data to inference state. RAG requires storage for vector indexes and document repositories, while long-context models and agents require more frequent reads and writes of KV cache, checkpoints, logs, and session state. Data lakes must also retain large volumes of colder content. HBM and DRAM handle data needed immediately; enterprise SSDs handle data needed soon and requiring low-latency retrieval; nearline HDDs serve the colder, higher-capacity tier.
Enterprise SSD fundamentals are stronger than those of consumer NAND. Enterprise SSD revenue rose 86.1% to $18.46 billion in the first quarter of 2026, while contract prices increased by approximately 80%. Sandisk’s enterprise SSD revenue increased sevenfold year over year, and the company plans to advance high-bandwidth flash.
Product upgrades are also materializing. Micron demonstrated the PCIe Gen6 9650 data-center SSD. Kioxia’s tenth-generation BiCS FLASH increases bit density by 60% and interface speed to 4.8 Gb/s while reducing power consumption. Customers are willing to pay for throughput, latency, power efficiency, and reliability, allowing enterprise products to partially escape pure bit-price competition.
NAND’s greatest risk is that supply constraints are less stringent than in HBM. TrendForce previously lowered its forecast for second-quarter NAND ASP growth from 70%–75% to 55%–60%.
Bank of America projects a steeper deceleration, with sequential price increases of 65%, 13%, and 1% in the second, third, and fourth quarters, respectively. Prices may continue to rise, but incremental profit gains could diminish rapidly. If high margins prompt suppliers to relax capital discipline, NAND will return to inventory and price competition sooner than HBM.
Sandisk and Kioxia offer high operating leverage and should be valued against enterprise revenue, ASPs, product qualifications, and capital-expenditure discipline. Sandisk gained 10.01% this week, indicating that the market has begun pricing in earnings upgrades from enterprise SSDs and high-bandwidth flash. Kioxia’s key drivers are next-generation BiCS, its enterprise product mix, and supply discipline. Both companies must guard against an excessively rapid recovery in consumer NAND that could dilute enterprise improvements, as well as customers reducing SSD demand per task through compression, tiered storage, and higher utilization.
AI inference efficiency is the most important counterargument in this section. CMX, CXL, TurboQuant, and MLA all reduce recomputation, data duplication, and idle capacity. Efficiency gains reduce memory and SSD consumption per inference, but they may also lower inference costs and drive more applications, users, and tokens. Demand analysis should separate three metrics: storage usage per token, total token volume, and the tiering ratio between hot and cold data. Looking only at model context length risks overstating actual physical-storage demand.
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
The advantage of nearline HDDs is their low cost for storing massive volumes of cold data. AI data lakes will continue accumulating raw corpora, video, images, logs, training versions, checkpoints, and compliance backups, most of which do not require SSD-level latency. Bank of America expects storage exabyte growth to exceed 25% over the next three to five years, driven by AI training, inference, cloud uploads, and physical AI. As long as data generation outpaces deletion and compression, nearline HDDs will remain essential assets in the high-capacity tier.
The HDD investment framework differs from that of NAND. NAND is a play on ASP leverage and product mix, while HDD depends more on supply discipline in a duopoly, build-to-order production, nearline exabyte shipments, and free cash flow. Build-to-order production reduces channel inventory and price undercutting, while higher-capacity drives lower customers’ total cost of ownership per terabyte. Investors should require Seagate Technology and Western Digital to convert capacity growth into gross profit, cash generation, and capital returns, rather than merely pursuing higher platter volumes.
Currently verifiable data do not yet cover new nearline HDD orders, capacity per drive, or free cash flow, so operating strength cannot be inferred from share-price performance. Seagate Technology gained 5.01% this week, while Western Digital rose 0.76%. This only indicates that trading sentiment favored Seagate Technology; it does not directly prove that a gap has emerged in orders or cash flow. Subsequent validation must focus on nearline exabytes, average capacity per drive, build-to-order coverage, inventory turnover, and free cash flow.
The counterarguments to the HDD thesis are also clear. Data deduplication, compression, and lifecycle management reduce the physical footprint of cold data. Nearline growth would slow if enterprises place more hot data on SSDs and reduce long-term retention. Insufficient yield improvements for high-capacity drives could also delay deliveries and raise costs. The HDD thesis requires simultaneous improvement in exabyte growth, supply discipline, and cash flow; without all three, it remains merely a capacity story.
Equipment, Testing, and Materials: Second-Order Beneficiaries of Memory Capex
Opportunities in equipment, testing, and materials arise from two drivers: wafer capacity expansion and the increasing manufacturing complexity of each memory device. Micron’s Hiroshima project and new Korean fabs are pushing advanced DRAM, HBM, and NAND capacity additions into 2027–2030.
Near-term pricing is determined primarily by legacy capacity and long-term agreements. Equipment revenue materializes later, following fab construction, tool installation, yield ramp-up, and process complexity, but may also persist for longer.
The equipment chain cannot be assessed solely on aggregate capital expenditure. If HBM hybrid bonding continues to be delayed, related equipment orders may arrive later than the market expects. Continued use of thermocompression bonding for 12-layer products would extend the lifecycle of mature packaging tools. If high margins trigger unconstrained NAND expansion, equipment suppliers will benefit from near-term orders, while incremental supply will depress memory manufacturers’ medium-term profits. Equipment and memory stocks can rise simultaneously, but their long-term interests are not fully aligned.
Testing offers greater certainty than a bet on any single technology path. As HBM layer counts, I/O, base dies, and thermal management become more complex, test duration and failure analysis become increasingly important. PCIe Gen6 enterprise SSDs, high-bandwidth flash, and silicon photonics also increase interface-testing difficulty.
FormFactor reported first-quarter 2026 revenue of US$226 million, up 32% year on year, and EPS of US$0.56, above the US$0.44 consensus estimate, indicating that testing demand has already begun to translate into financial results. The risks are that customers develop testing capabilities in-house, yields mature rapidly, and higher equipment utilization reduces demand for incremental systems.
The materials moat lies in qualification lead times. Approximately 80% of materials used at the Hiroshima fab are sourced from Japan, so capacity expansion will initially benefit suppliers already within the supply system. T-glass, low-dielectric glass, CMP materials, electroplating additives, and advanced-packaging chemicals all require lengthy validation. New suppliers can build capacity but cannot bypass customer qualification. Materials companies should be evaluated based on initial volume shipments and customer share, not merely announced investment amounts.
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Rising memory prices are reshaping downstream bills of materials. Servers can absorb some of the cost through higher compute utilization and AI service revenue, while smartphones, PCs, EVs, and other durable goods depend more heavily on consumers’ ability to pay. The “chip inflation” narrative—DRAM prices rising more than sixfold within a year—has spread from the memory industry to end markets. Brands have only three options: raise prices, reduce specifications, or compress gross margins.
AI servers have the greatest capacity to absorb these costs, but funding constraints cannot be ignored. The five largest hyperscalers’ aggregate capital expenditure has already exceeded their combined operating cash flow, while the four largest US technology companies’ 2026 capex is expected to rise approximately 80% year on year. When power, GPUs, networking, storage, and construction costs all increase simultaneously, customers will prioritize the scarcest GPUs and HBM, then reduce spending on general-purpose servers, network tiers, or redundant configurations. Long-term agreements protect memory manufacturers’ revenue but also turn customers’ ability to pay into a systemic risk for memory stocks.
Network architecture optimization may reduce some memory and interconnect demand. The flattened architectures of Amazon RNG and OpenAI MRC are estimated to potentially reduce active networking equipment by more than 60% and transceiver counts by 40%–50%. These forecasts remain disputed, while delays to CPO and Kyber could extend the window for pluggable optical modules. Nevertheless, the direction warrants attention: customers will use system design to offset hardware inflation. Memory pooling, cache compression, and fewer network hops all pursue the same objective—raising the effective utilization of expensive hardware.
Smartphones and PCs are the most vulnerable to demand destruction. Higher memory prices will first raise prices for high-capacity models, then force entry-level products to reduce DRAM or NAND configurations. Lenovo’s adoption of Yangtze Memory Technologies SSDs in laptops sold globally shows that brands are also diversifying suppliers to control costs. Alternative supply can ease procurement pressure but will also weaken overseas NAND manufacturers’ pricing power in consumer markets. Key indicators include whether base capacities stop increasing, device prices rise, and replacement cycles lengthen.
EV and industrial customers place greater value on long-term supply. Micron has signed a long-term automotive memory supply agreement with Ford and described it as one of several such agreements. Automotive qualification and long product lifecycles support contract stability but cannot fully insulate customers from pricing pressure. If vehicle gross margins come under pressure, customers may optimize domain controllers, reduce redundancy, or defer advanced driver-assistance configurations. Memory manufacturers must demonstrate that long-term agreements can lock in both volume and pricing without pushing downstream customers toward more aggressive specification reductions.
Investment Ranking, Risks, and Disconfirming Evidence
Investment ranking should prioritize certainty, followed by earnings leverage, and finally cash flow. The first tier comprises HBM and high-end DRAM, with SK Hynix preferred, followed by Micron; Samsung Electronics requires an offset for the adverse impact on its end-device businesses. The second tier is NAND/eSSDs, where Sandisk and Kioxia offer greater earnings leverage but also carry higher pricing and inventory risk. The third tier is nearline HDDs, where Seagate Technology and Western Digital must validate the thesis through exabyte shipments, build-to-order discipline, and free cash flow. The fourth tier comprises equipment, testing, and materials, with preference given to segments that have already secured orders, entered qualification, or benefit from increasing process complexity.
The first disconfirming indicator is that LTAs may not be sufficiently binding. If contracts allow customers to cancel, defer, or renegotiate pricing easily, purported long-term visibility remains merely an optimistic indication at the top of the cycle. Investors should monitor prepayments, deposits, minimum purchase commitments, pricing floors and ceilings, and default provisions—not merely count the number of agreements signed.
The second is active downstream specification reduction. If base memory capacities in smartphones and PCs stop increasing, servers reduce redundancy, or EVs defer advanced computing configurations, upstream pricing has already begun to damage demand. Memory manufacturers’ pricing power is valuable only if customer unit sales and product specifications remain materially intact.
The third is unconstrained NAND expansion. Several institutions have already lowered their forecasts for the pace of NAND price increases, which may slow to the low single digits in the fourth quarter. If suppliers simultaneously increase capital expenditure, bit growth, and channel inventories, the structural improvement in enterprise SSDs could be overwhelmed by declining commodity prices.
The fourth is KV-cache and system-efficiency improvement outpacing token growth. TurboQuant, MLA, CXL, and tiered caching will reduce the physical capacity required per workload. If total token volume does not expand correspondingly, inference-storage demand will fall short of the market’s linear extrapolation. Investors should continuously compare cost per token, inference-call volumes, cache hit rates, and enterprise SSD configurations.
The fifth is crowded positioning and interest-rate disruption. Some products tracking SK Hynix, Samsung Electronics, and memory themes have already grown larger than the underlying stocks’ average daily trading volume, indicating increasing position concentration. High interest rates reduce the valuation of long-dated earnings and raise financing costs for hyperscalers and data-center operators. Even if fundamentals remain strong, memory stocks may still experience substantial drawdowns due to positioning, exchange rates, and interest rates.
What to Watch Next Week
Start with long-term contract details. Contract coverage, fixed volume/price ratios, prepayments, and price-reopener clauses at Samsung Electronics, SK hynix, and Micron will determine whether control over supply can translate into cash flow.
Next, monitor the pricing trajectory. DDR and NAND prices are still expected to rise in the third quarter. The focus should be on comparing actual transaction prices with forecasts of 32% and 30% increases, respectively, and assessing whether fourth-quarter quotes continue to be revised down.
Track HBM customer fulfillment rates. If key customers continue to receive only 50%–67% of requested volumes, suppliers’ pricing power will persist. If fulfillment rates improve rapidly, the duration of the shortage will need to be reassessed.
Track enterprise SSDs. Enterprise revenue, PCIe Gen6 qualification, and high-bandwidth flash qualification at SanDisk, Kioxia, and Micron will determine whether NAND can shift from price recovery to a product-mix upgrade.
Track four nearline HDD metrics: exabyte shipments, average capacity per drive, build-to-order coverage, and free cash flow. Capacity growth without improved cash flow is insufficient to support higher valuations.
Track order conversion for semiconductor equipment. ASML’s EUV deliveries, Lam Research’s memory-equipment demand, test-equipment orders at Advantest and FormFactor, and delivery trends at DISCO and packaging-material suppliers will indicate whether memory capex is beginning to spread upstream.
Track AI inference efficiency. Real-world deployment of TurboQuant, MLA, CXL, and tiered caching will determine memory and SSD consumption per token. At the same time, monitor whether lower costs drive faster growth in total token volumes.
Track downstream demand destruction. Base memory configurations in smartphones and PCs, server-rack shipments, advanced compute configurations in EVs, and CSP capex will ultimately determine whether memory price increases can continue to pass through.
Related Reading
404K SEMI-AI 2026-07-05 Storage Weekly — AI Inference Memory, NAND/eSSD, Nearline HDD