
404K SEMI-AI 2026-07-05 Storage Weekly — AI Inference Memory, NAND/eSSD, Nearline HDD
目录
Overall View This Week
Weekly Performance of Storage-Related Names
DRAM/HBM: Supply Rights, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: AI CPU and Rack-Memory Spillover
NAND/eSSD/SSD: Inference, RAG, and Enterprise-SSD Elasticity
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Test, and Materials: Second-Order Beneficiaries of Memory Capex
Downstream Costs and Demand Destruction: Servers, Network Equipment, Smartphones, PCs, EVs
Investment Ranking, Risks, and Falsification
Next Week’s Watchlist
Overview
Overall View This Week
The storage chain has entered its second phase, and the market is starting to distinguish between visibility, elasticity, and cash flow. HBM and high-end DRAM are being bought for customer qualification, supply constraints, and long-term agreements. NAND and enterprise SSDs are being bought for ASP upside and inference-cache elasticity. Nearline HDDs are being bought for the duopoly, BTO orders, and cash-flow quality. All three lines are being pulled by AI, but their valuation, cadence, and falsification conditions are completely different.
Last week’s decline in the U.S. storage chain does not mean the industry logic has weakened. The Roundhill Memory ETF fell 14.87%, Micron fell 13.54%, SanDisk fell 15.41%, while Western Digital and Seagate Technology fell 7.07% and 8.00%, respectively. This looks more like position and valuation digestion after elevated expectations. Comparable Korean and Japanese storage names still rose during the prior market window, suggesting capital has not fully exited storage, but is repricing certainty and elasticity.
The strongest evidence this week remains in memory supply. Jefferies’ memory price estimates extend the upcycle window into 2027 and place real incremental supply pressure in 2028. Micron already has 16 long-term contracts, with more than half of sales locked through 2030. SK Hynix and Samsung Electronics’ long-term investment plans show that AI memory has moved from a short-term upcycle to a national-level capacity project. These data points support valuation rerating for the leaders, but they also make the counter-evidence clearer: if customer LTAs are not binding, or if AI demand falls short of capacity expansion before 2028, cyclical-stock valuations will be compressed again.
AI inference is pushing NAND and SSDs into a more important position. Long context, RAG, agent workloads, and Warm KV Cache turn data from “stored but unused” into “read repeatedly.” The value of enterprise SSDs expands from capacity to latency, throughput, endurance, and cost. The claim that Vera Rubin single-server NAND demand could reach up to 1,152TB is the strongest hard anchor in this week’s NAND elasticity narrative.
Downstream cost pass-through has started to become a risk. Higher storage prices benefit original manufacturers, but they squeeze the BOM of AI servers, networking equipment, PCs, smartphones, and some edge hardware. Goldman Sachs warned that “reducing memory usage” could become a downside risk for Micron and the chip sector, while Nvidia and Qualcomm also have incentives to reduce dependence on high-priced storage. For investment, storage price increases cannot be assessed only through upstream profits; investors also need to watch whether customers begin cutting capacity, changing specifications, or delaying procurement.
Weekly Performance of Storage-Related Names
Short-term prices in the storage chain reflect cooling crowded trades, while industry validation is not over. U.S. ETFs and individual stocks pulled back most in high-elasticity areas, while leading Korean and Japanese names remained strong during the prior market window. This divergence shows that the market is starting to price DRAM/HBM, NAND/eSSD, and HDD cash flow differently.
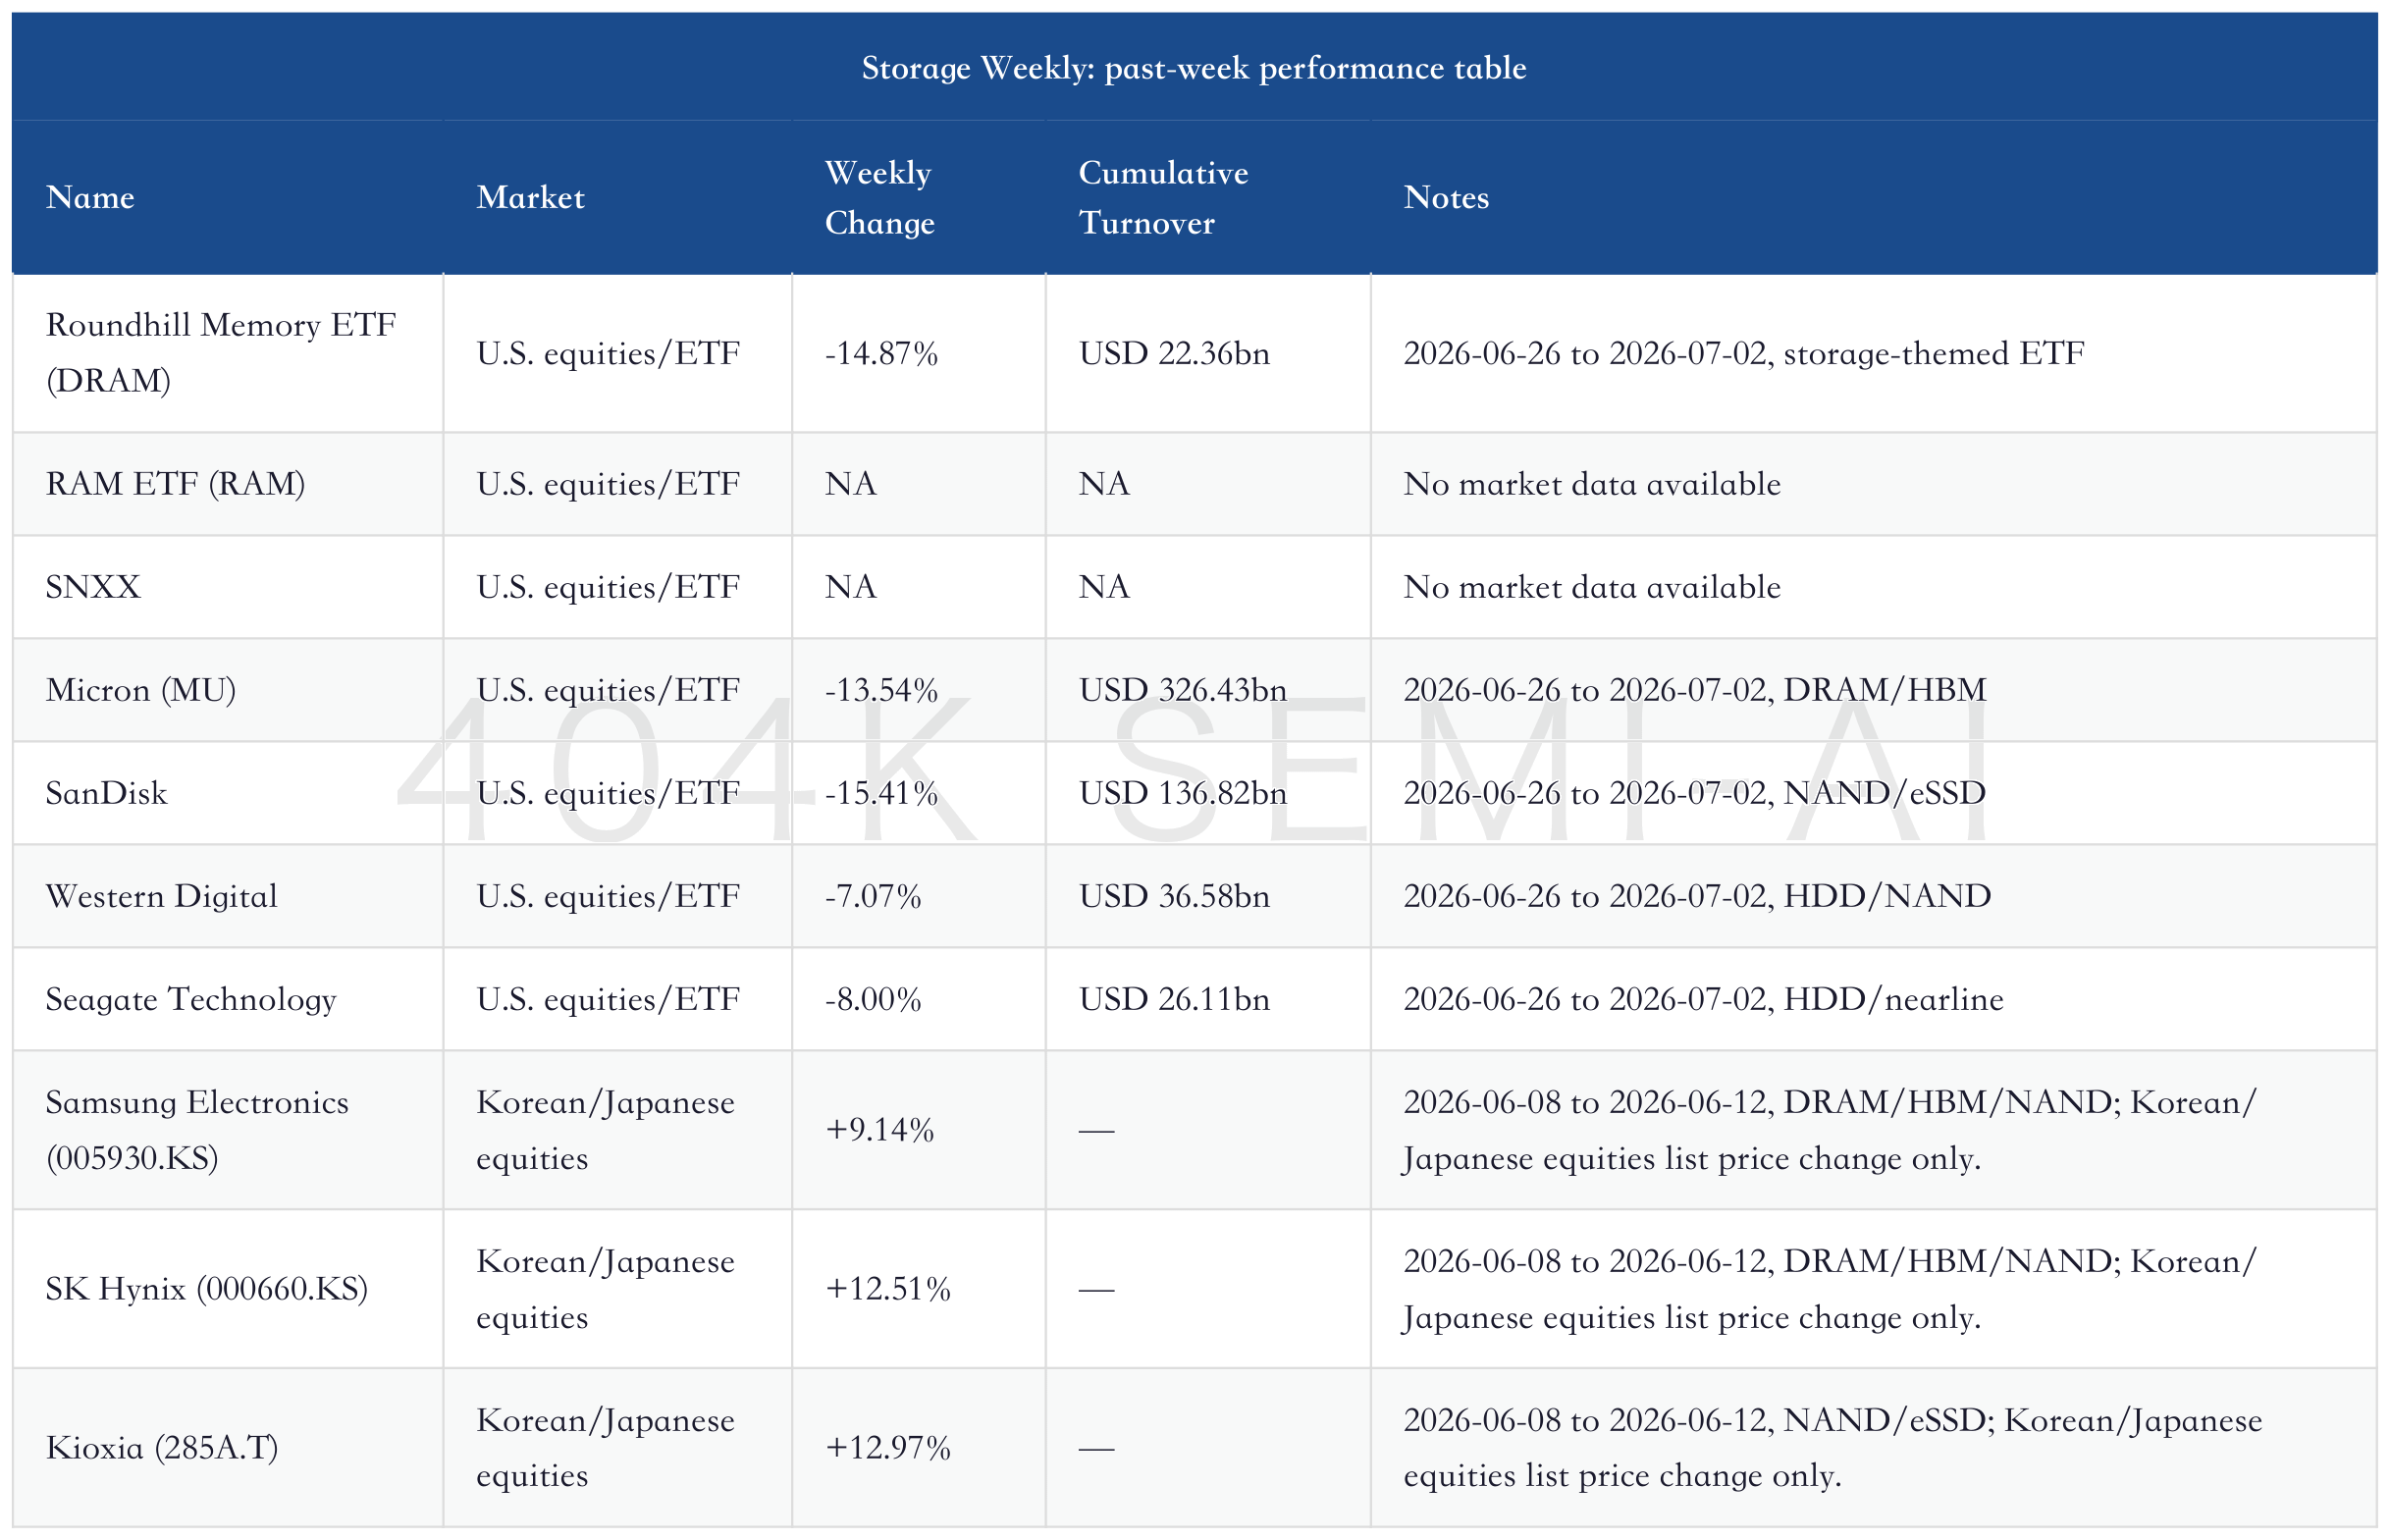
Among U.S. equities, SanDisk and Micron saw the largest declines, indicating that the market is more concerned in the short term that NAND elasticity and DRAM expectations have already been priced in quickly. Western Digital and Seagate Technology fell less. HDD trading is more tied to orders, cash flow, and capital returns, and was not pushed into the most crowded part of the “price-hike narrative” in the same way as Micron and SanDisk.
The gains in Korean and Japanese names have two implications. First, SK Hynix and Samsung Electronics are driven more by HBM, AI memory capex, and customer qualification, and capital is paying a certainty premium. Second, Kioxia’s rise shows that NAND/eSSD elasticity is being traded again, but this line will depend more on enterprise SSD share, pricing discipline, and the pace of new capacity.
DRAM/HBM: Supply Rights, Long-Term Agreements, and Customer Qualification
The strongest change in this DRAM/HBM cycle is that customers have started to lock in supply early, while manufacturers have begun to use long-term agreements to weaken the traditional spot cycle. Micron’s 16 long-term contracts, SK Hynix’s HBM ASP revision, and Samsung Electronics’ HBM fab investment all point to the same question: whether AI customers are willing to pay higher prices for memory certainty.
The most important pricing framework this week comes from Jefferies. It breaks the memory upcycle into three questions: the pace of price increases, the timing of supply pressure, and the scale of incremental capacity. This framework also makes the bearish case more specific: capacity expansion will come, and what determines the length of the cycle is whether AI demand can absorb the 2028 supply additions.
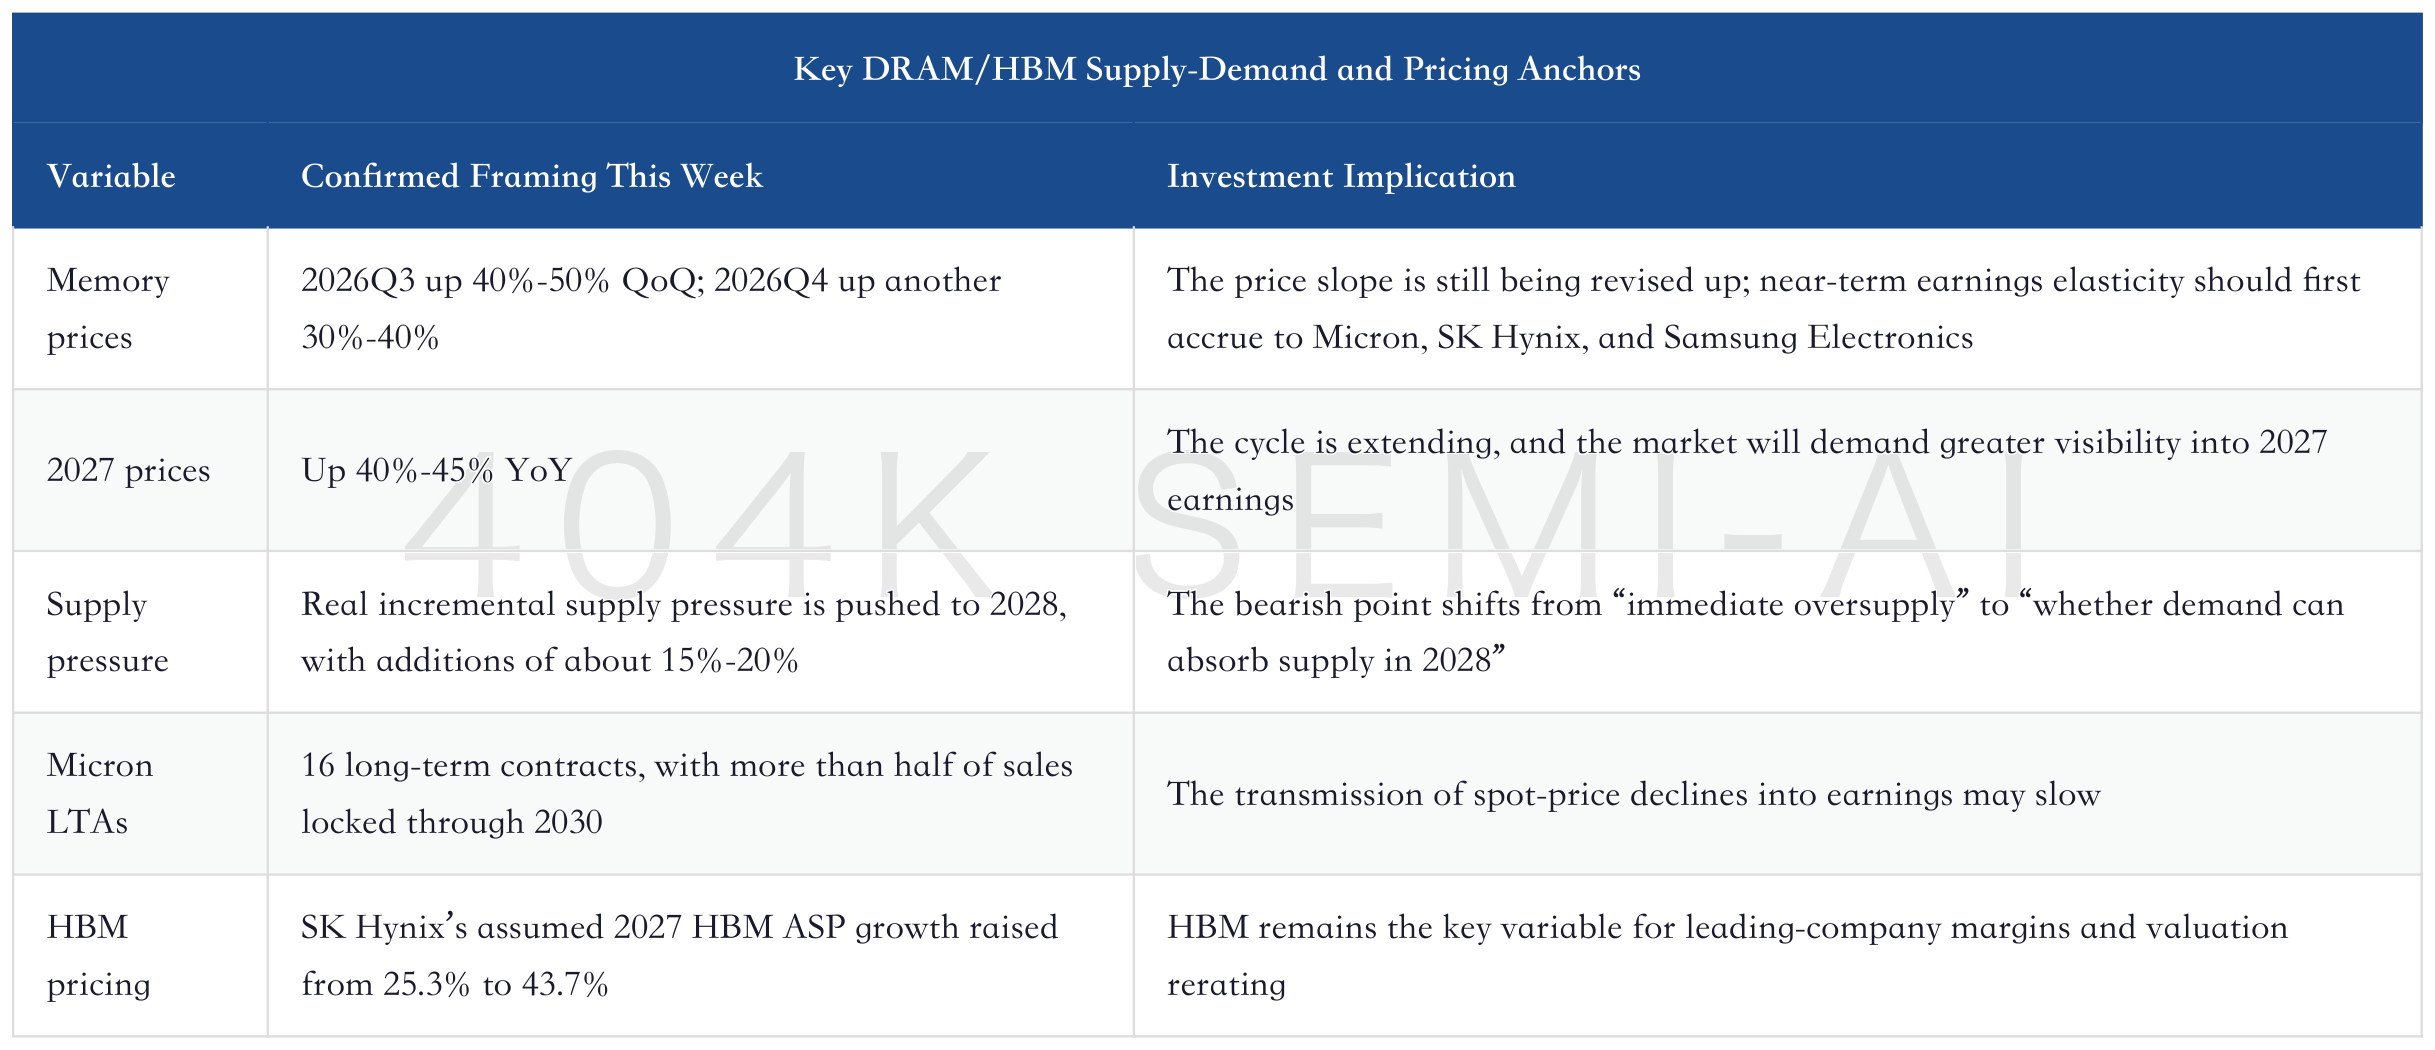
Micron’s investment thesis now looks more like “high-end memory supply rights” than in the past. Multiple institutions raised target prices after results, but report dates and securities definitions do not provide fully consistent split-adjusted information, so this is treated only as a signal of earnings-assumption upgrades, not as a precise ranking. The more important evidence is that Micron FY26Q3 was cited with revenue of USD 41.5bn and EPS of USD 25.11, above buy-side expectations of USD 38.1bn and USD 22.38; August-quarter guidance was also strong. What the market is really buying is whether the AI memory supercycle can help Micron escape the traditional cyclical-stock discount.
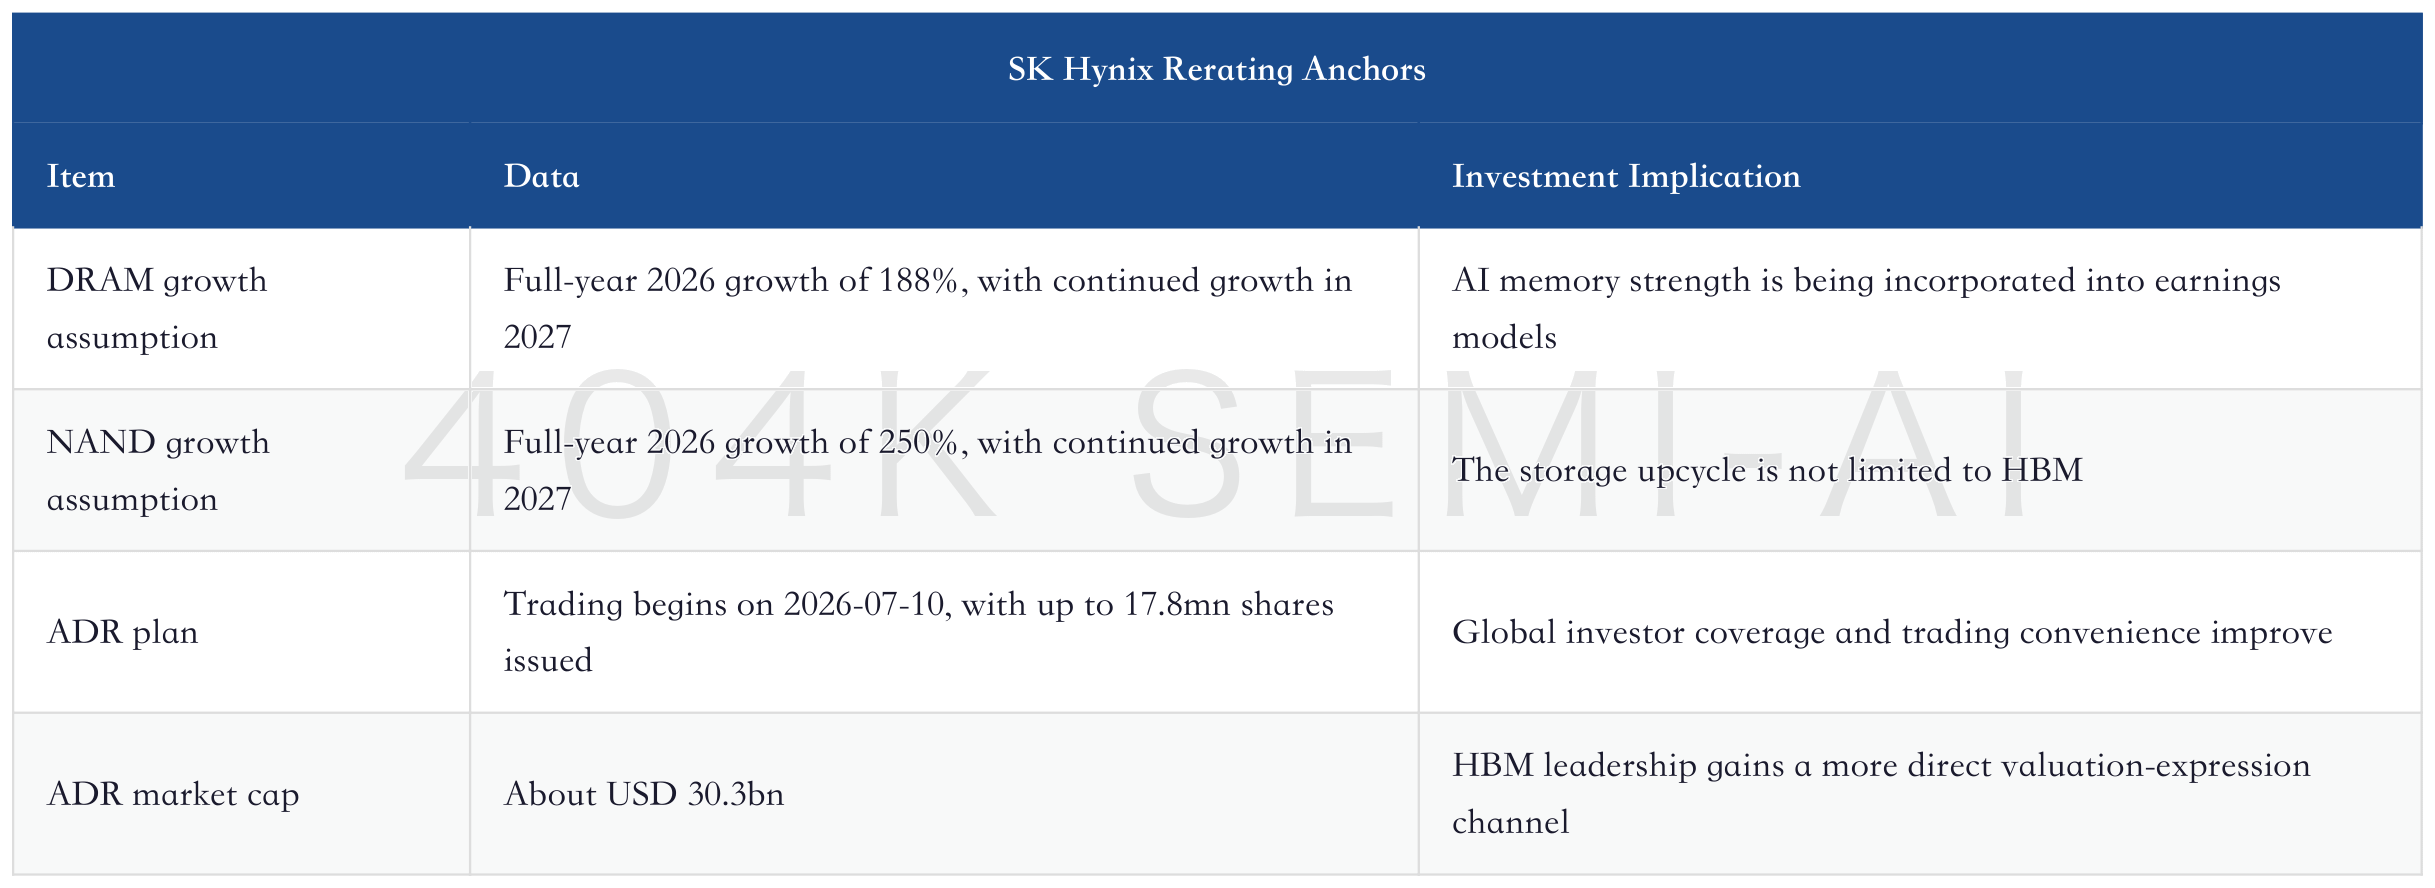
SK Hynix is being bought for HBM customer lock-in and capital-market tradability. Mirae Asset Securities’ assumptions push DRAM, NAND, and HBM ASPs all to higher levels, while the ADR plan improves trading convenience for global capital.
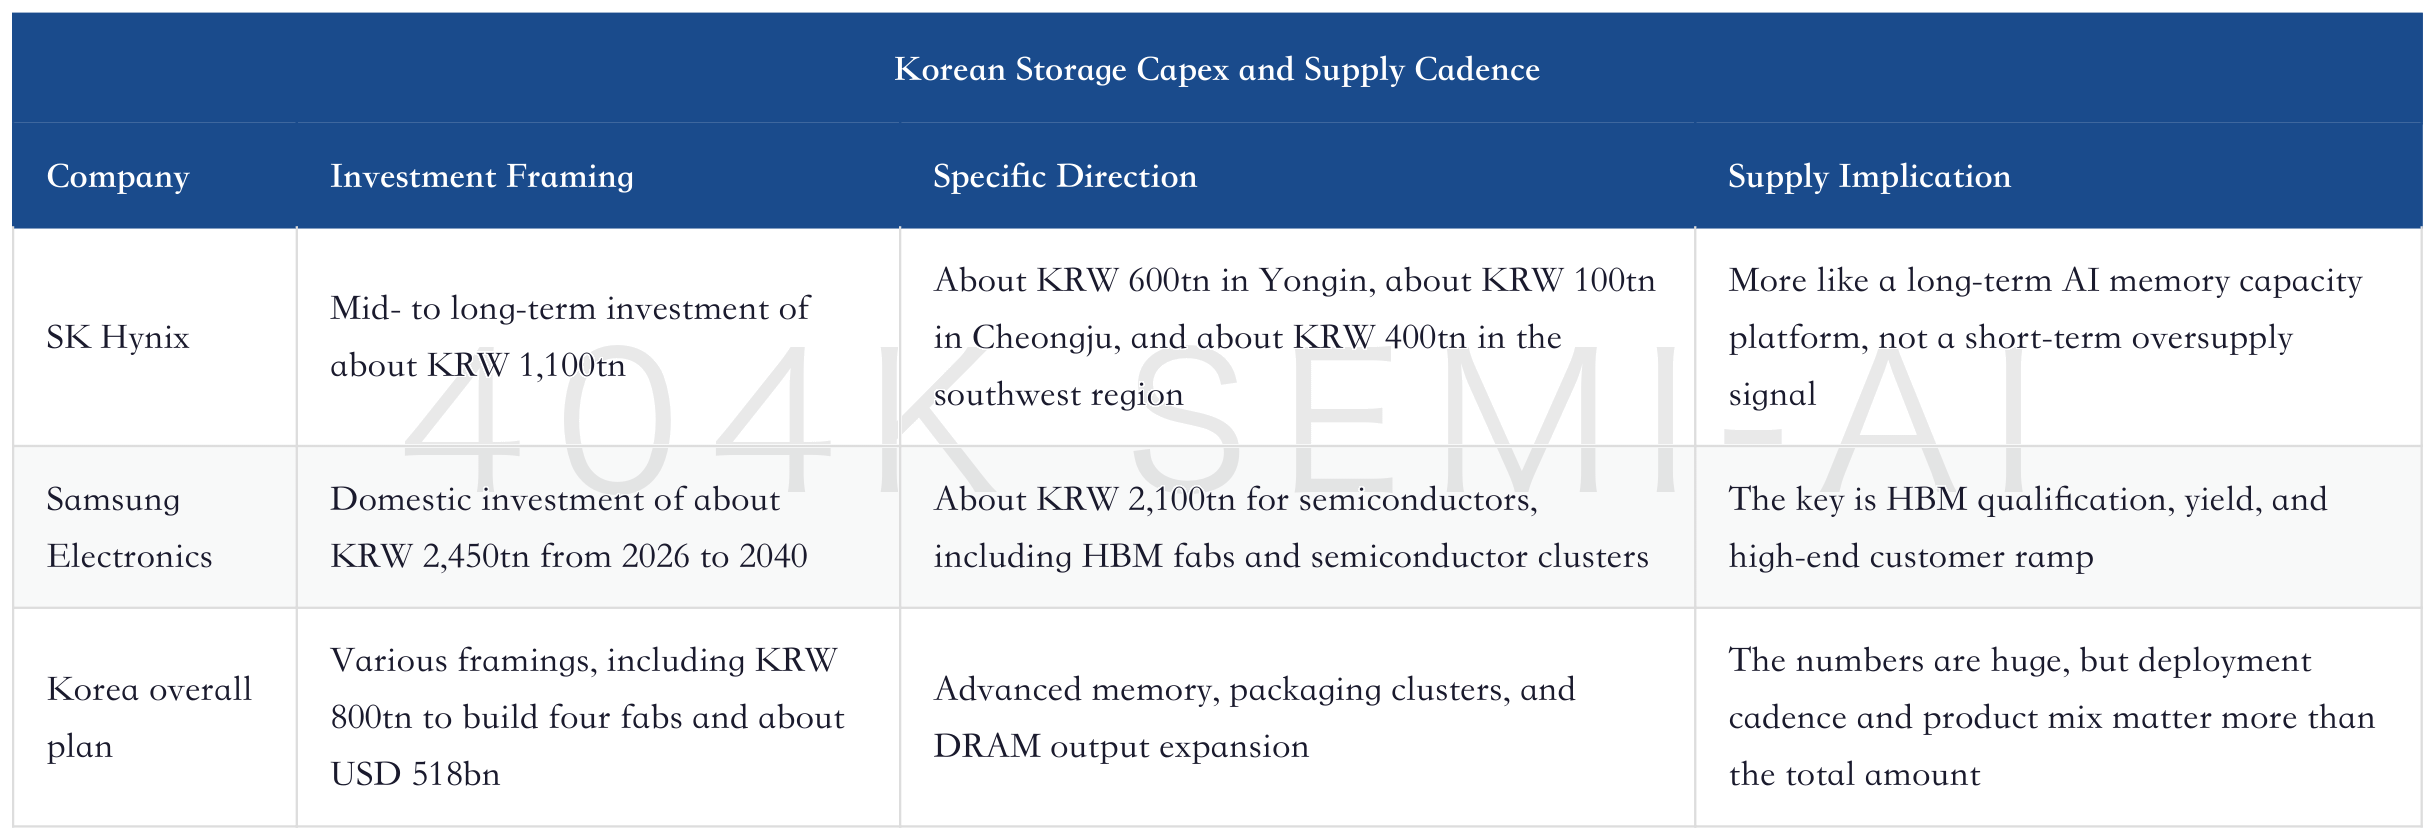
For Samsung Electronics, the key is restoring HBM qualification and supply credibility. Samsung’s 2026-2040 domestic Korea investment vision is about KRW 2,450tn, including about KRW 2,100tn for semiconductors and the Cheonan-Onyang HBM fab. Its elasticity comes from industry price increases, high-end customer validation, HBM back-end capability, and advanced-node progress. Once qualification and yield improve, Samsung will affect both HBM supply distribution and ordinary DRAM price expectations.
Korean capex numbers are large, but they should not be treated as a short-term supply shock. SK Hynix’s fourth Yongin fab is targeted for completion by 2033, while Samsung’s vision extends to 2040. These are long-cycle projects. Short-term pricing is more affected by existing capacity, HBM’s crowding-out of ordinary DRAM wafers, yield, and customer LTAs.
ChangXin Memory Technologies will not immediately crush global DRAM prices. Its roughly USD 3bn, 3-5 year server DRAM LTA with Tencent, and talks with Alibaba Cloud, ByteDance, Xiaomi, and others, show that Chinese cloud vendors are also locking in supply. But its current monthly capacity is about 300,000 wafers, with plans to double to about 600,000 wafers; DDR5 yield still lags, and capacity remains far below domestic demand. In the short term, CXMT looks more like a supply buffer for local Chinese demand than an unconstrained incremental source for global pricing.
The counter-evidence is also clear. Goldman Sachs listed “reducing memory usage” as a key downside risk for Micron and the chip sector, and warned that HBM capacity expansion in 2027-2028 could suppress pricing momentum. The DRAM big three also face U.S. class-action litigation. Although existing cases have required plaintiffs to prove more evidence of collusion, rather than relying only on synchronized price increases or production cuts, the litigation will increase trading volatility.
DRAM/HBM tracking indicators should focus on three things. First, whether LTAs truly cover price, volume, and duration, rather than serving as soft constraints. Second, whether HBM customer qualification continues to concentrate toward SK Hynix, Micron, and Samsung Electronics. Third, whether wafer allocation among ordinary DRAM, HBM, and server DDR continues to crowd each other out after 2027.
LPDDR/SoCAMM: AI CPU and Rack-Memory Spillover
LPDDR/SoCAMM is the most easily underestimated signal this week. It links AI CPUs, rack memory, edge AI, and the Apple supply chain, rather than a traditional handset-memory restocking cycle. Nvidia’s 2027 LPDDR demand is only about 60% fulfilled, and it is cutting SoCAMM capacity in half, showing that even the highest-priority customers cannot freely secure enough low-power, high-bandwidth memory.
The implication of LPDDR/SoCAMM tightness is not simply “higher handset prices.” Low-power memory is now being contested by AI servers, accelerator cards, CPU platforms, and edge AI at the same time. If Nvidia cannot fully secure supply, then Apple, as it pushes edge AI and premium foldables, will struggle to solve memory allocation issues through spot procurement.
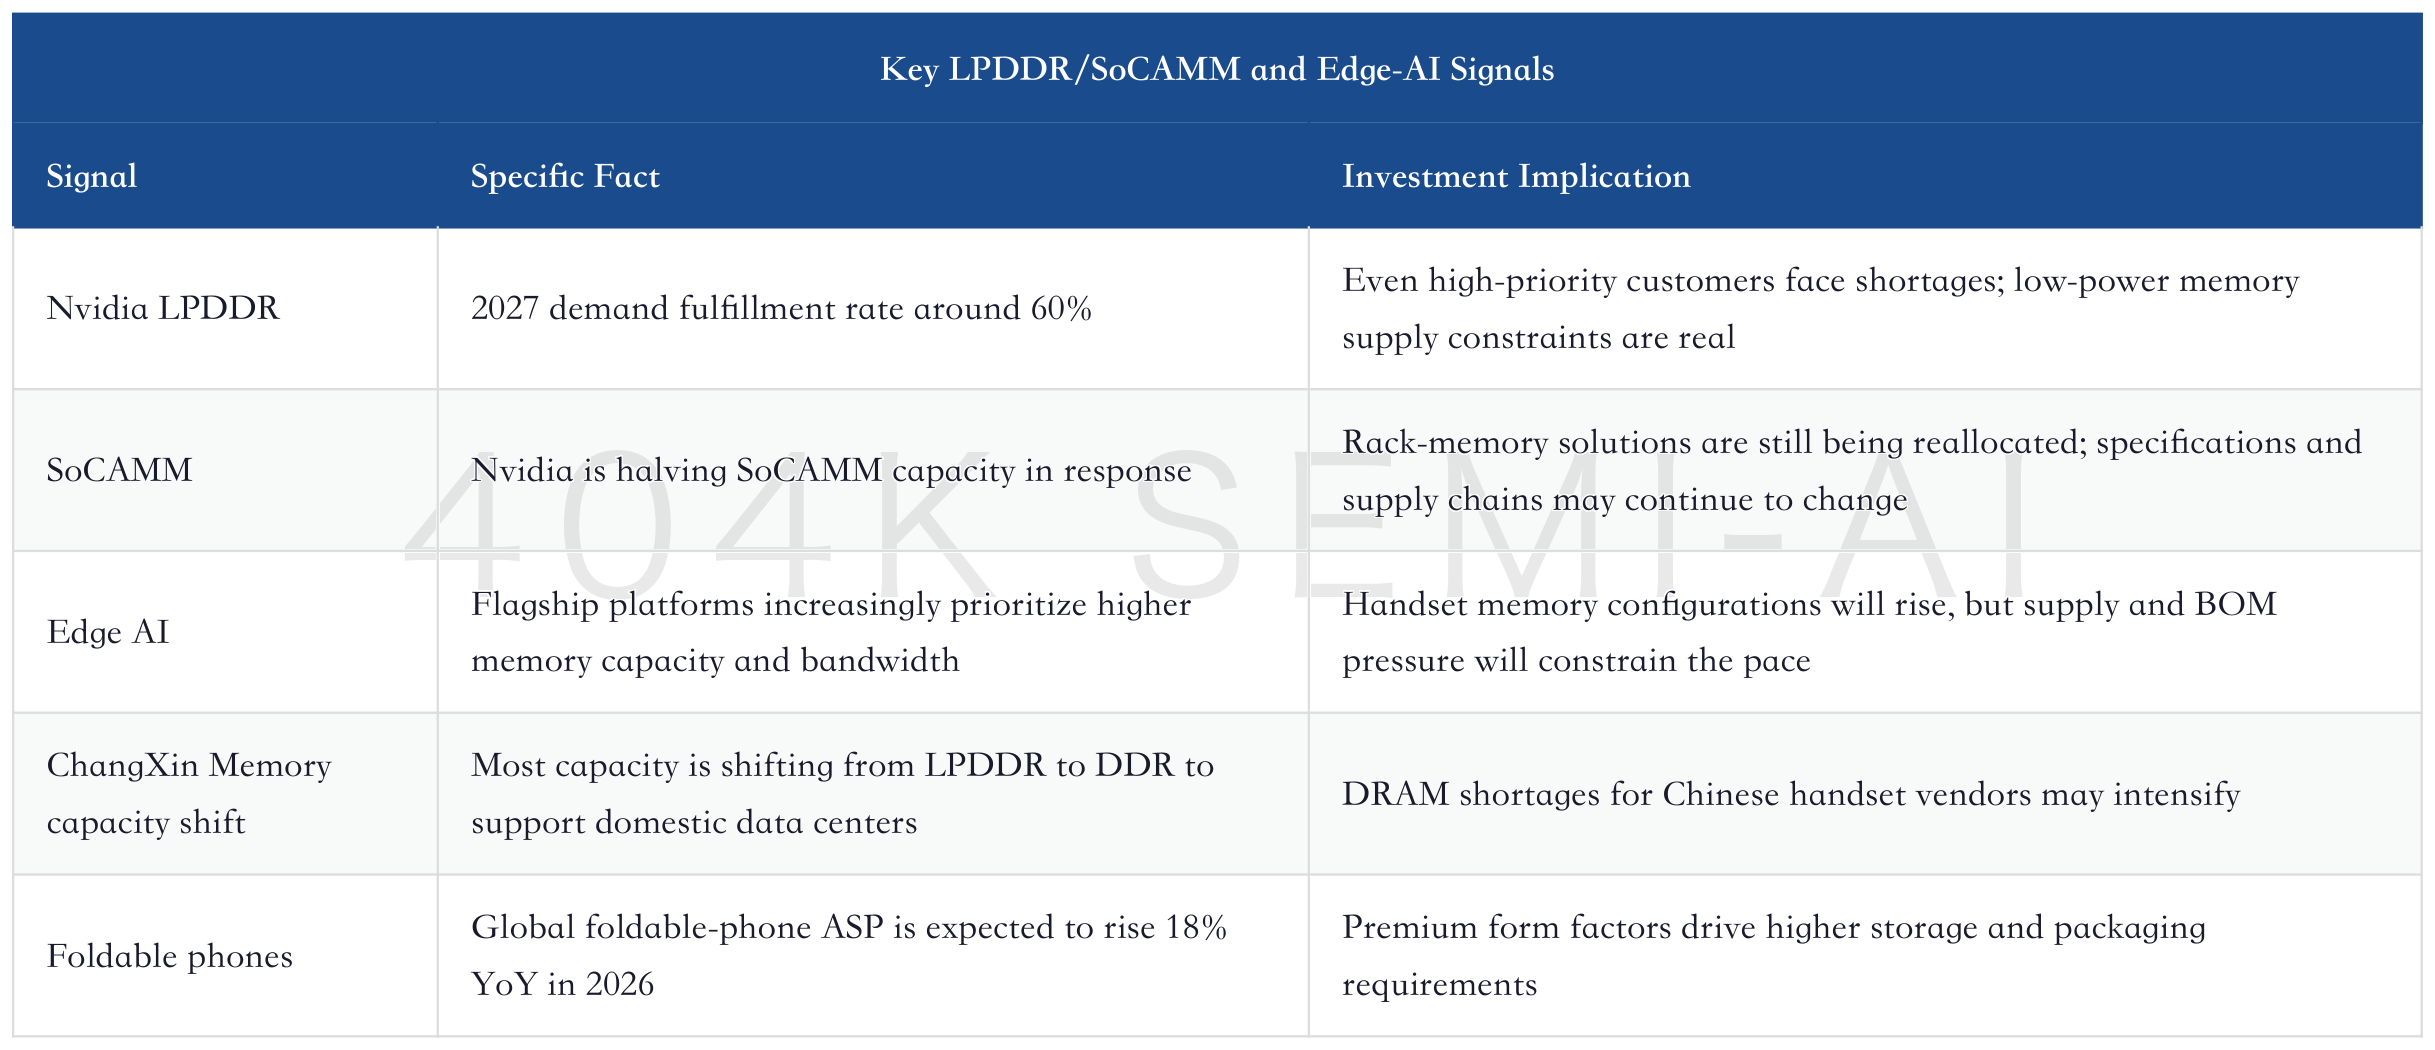
Apple is in the most typical squeeze between cost and supply. Counterpoint noted that edge-AI models will lead flagship platforms to prioritize higher memory capacity and bandwidth; foldable phones also combine larger screens, multitasking, and higher price bands. In 2026, book-style foldables are expected to rise to 76% of foldable shipments, while models priced above US$1,600 are expected to rise to 60%. This will increase the memory and packaging value content of premium smartphones and pass BOM pressure to OEMs.
Potential supply from ChangXin Memory cannot be treated as a cost cure for Apple. Korean research views suggest that Apple would find it difficult to procure DRAM from ChangXin Memory, with challenges including quality validation, geopolitical constraints, and ChangXin Memory’s greater capacity allocation toward data-center DDR. Even if Apple secures some supply, it would more likely reduce shortage risk than meaningfully improve costs.
The investment implication of LPDDR/SoCAMM is more about “spillover” than a single-company breakout. Micron, Samsung Electronics, and SK Hynix benefit from tight supply in high-end LPDDR and server DDR; smaller memory vendors such as Winbond Electronics and Nanya Technology benefit from gaps outside the big three; TSMC and Winbond’s WoW collaboration also shows that the logic is moving closer to memory, with memory supply entering the advanced-packaging and foundry ecosystem.
The counter-evidence for this line is model architecture and memory efficiency. If new models significantly reduce KV cache or context-memory usage, LPDDR and SoCAMM tightness would ease. Another counterpoint is configuration cuts by device makers: if handsets and PCs reduce AI memory configurations because of price increases, edge-AI demand would be delayed.
NAND/eSSD/SSD: Inference, RAG, and Enterprise-SSD Elasticity
The NAND investment logic is shifting from the “consumer-electronics inventory cycle” to “inference caching and enterprise-SSD elasticity.” AI inference, RAG, and agent workloads generate large amounts of repeatedly accessed data. Data is not merely kept in cold storage; it must also be quickly retrieved, ranked, cached, and updated. Enterprise SSDs are therefore beginning to capture part of AI infrastructure value outside memory.
SanDisk is the most concentrated NAND-elasticity name this week. Target-price and EPS estimate upgrades, together with a higher eSSD revenue share, show that the market is beginning to move NAND from cyclical-bottom recovery to repricing it as an enterprise-SSD elasticity asset. The target-price framework cannot be precisely ranked against other institutions; here it is only used as a signal of upgraded earnings assumptions.
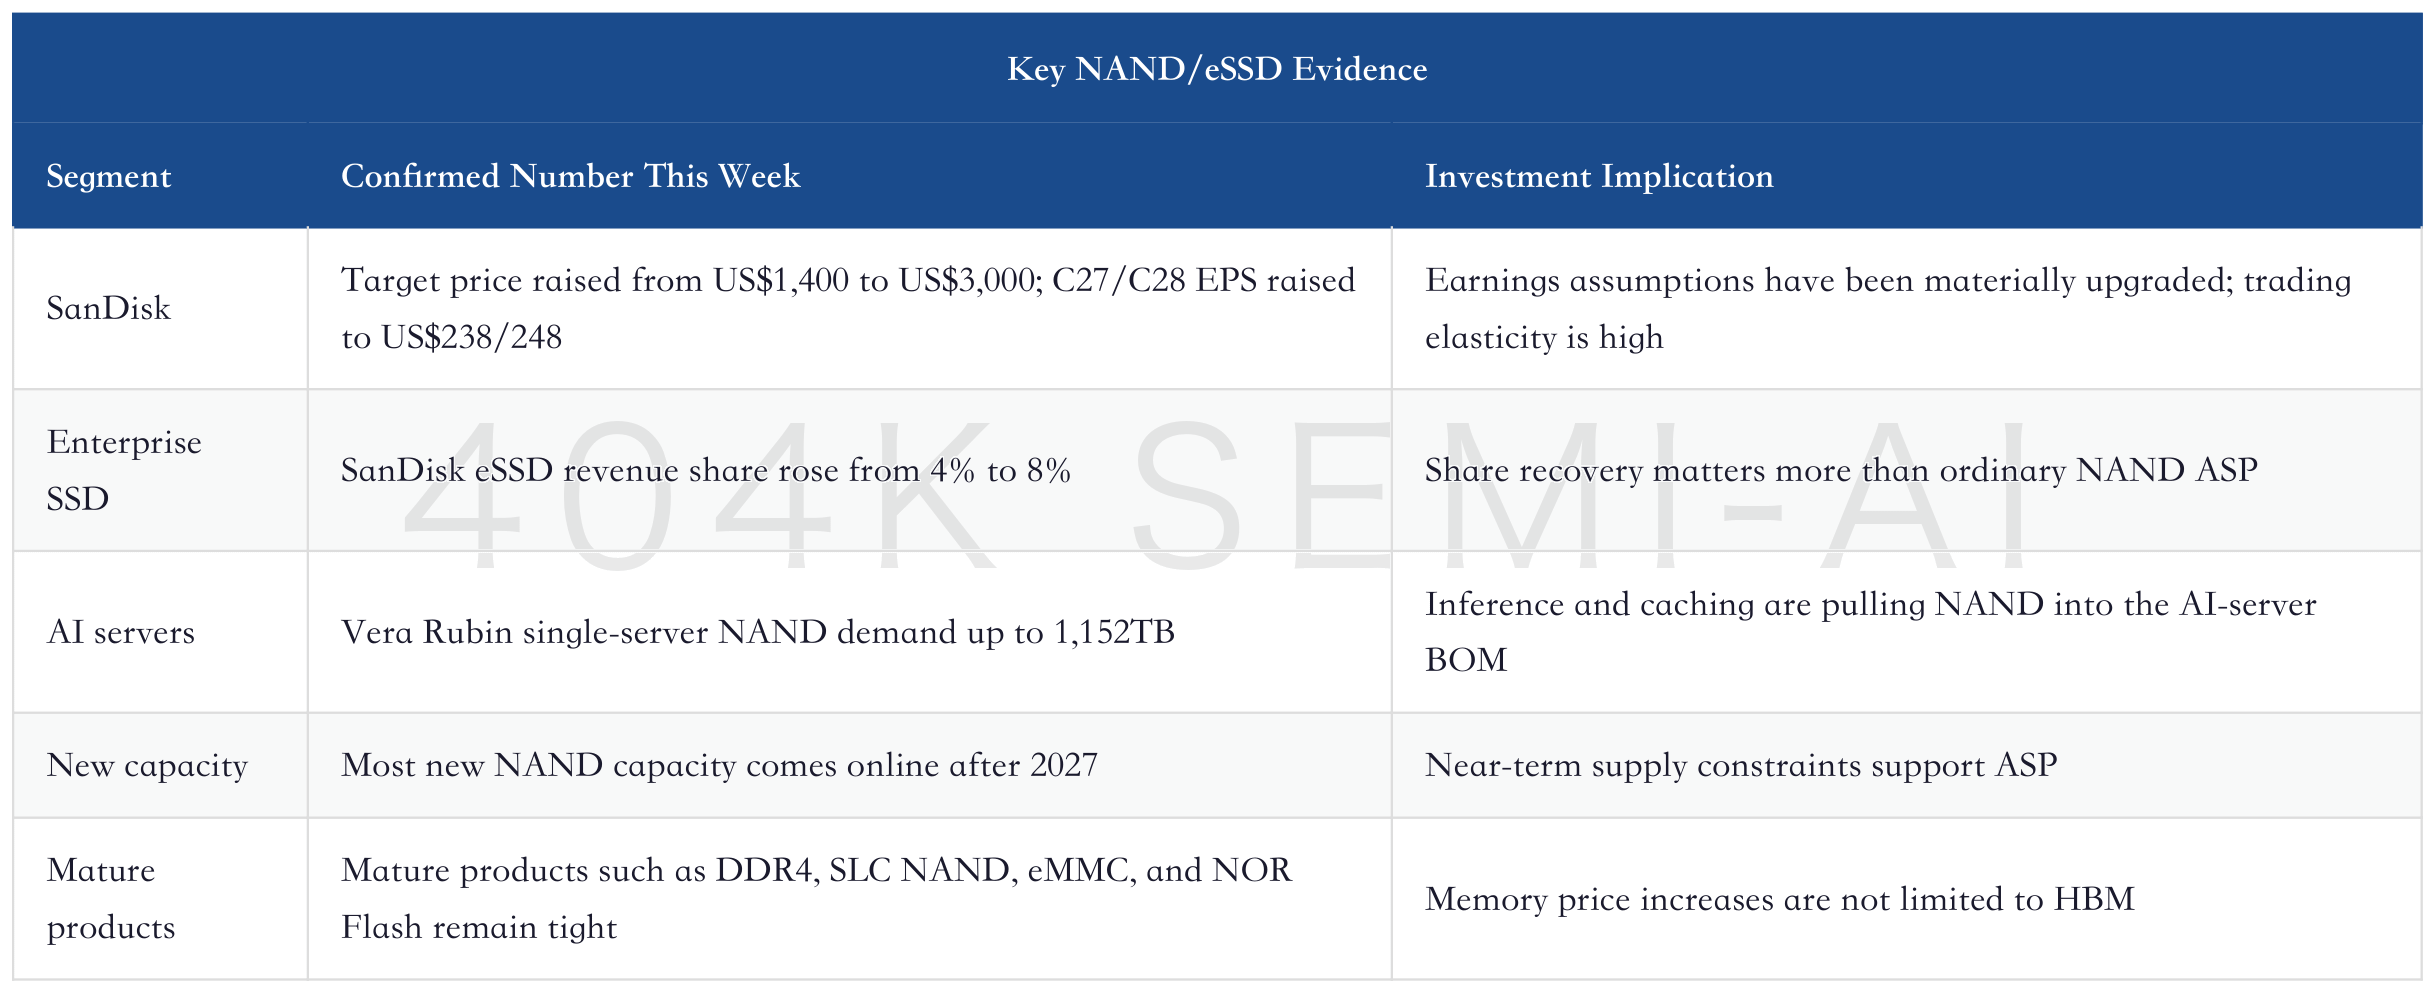
NAND has higher elasticity than DRAM/HBM, but weaker certainty. DRAM/HBM has customer qualification, long-term agreements, and high-end GPU attachment; NAND requires joint validation from enterprise-SSD orders, price discipline, and supplier restraint. If original manufacturers restart expansion at high prices, or if consumer-electronics demand cannot absorb price increases, NAND’s earnings elasticity will quickly reverse.
Warm KV Cache is the key concept behind NAND revaluation. In long-context and RAG scenarios, models will not keep all data long term in expensive HBM or DRAM. Lower-cost, higher-capacity enterprise SSDs can handle part of hot and warm data. This logic does not mean NAND becomes HBM, but it does raise the priority of enterprise SSDs in AI servers.
Kioxia’s rally should also be viewed in this context. Kioxia is a relatively pure NAND/eSSD asset. If enterprise-SSD pricing and share continue to improve, Kioxia will benefit more directly than diversified memory companies. Conversely, if NAND original manufacturers expand supply to compete for share, Kioxia’s profit elasticity would also be compressed faster.
Phison and the controller chain also deserve tracking. AI inference does not only buy NAND wafers; it also buys controllers, firmware, reliability, read/write performance, and end-to-end system solutions. Profit allocation in enterprise SSDs will be redistributed among NAND original manufacturers, controller companies, and server platforms.
There are three main counterpoints for NAND/eSSD. First, if new NAND capacity is released early or without discipline, ASP will come under pressure first. Second, if customers improve RAG and KV-cache compression, per-server SSD demand will be lower than the high-case scenario. Third, when the AI-server BOM is squeezed by HBM, GPUs, networking, and power, SSD capacity may become a configurable item that gets cut.
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
There were no new nearline exabyte shipment figures for HDDs this week, so the investment conclusion should remain measured. What can be confirmed is that the market is already trading Western Digital and Seagate Technology as part of the AI storage chain, but their logic differs from DRAM/NAND. HDD exposure is about the duopoly structure, BTO orders, nearline capacity growth, and free cash flow.
AI data lakes and RAG will increase demand for long-term data retention. Training data, retrieval corpora, logs, video, synthetic data, and model versions all require low-cost, high-capacity storage. Enterprise SSDs address hot data and low-latency access, while nearline HDDs address capacity cost and long-term retention. The two serve different price tiers within tiered storage.
Western Digital and Seagate Technology have had smaller share-price pullbacks than Micron and SanDisk, indicating that the market has not treated HDDs as the highest-beta trade in the short term. Western Digital has both HDD and NAND-related exposure; Seagate Technology is more purely exposed to nearline HDDs and cash flow. If AI data-center procurement moves into a clearer BTO and long-term order model, Seagate Technology’s cash-flow certainty would become more pronounced.
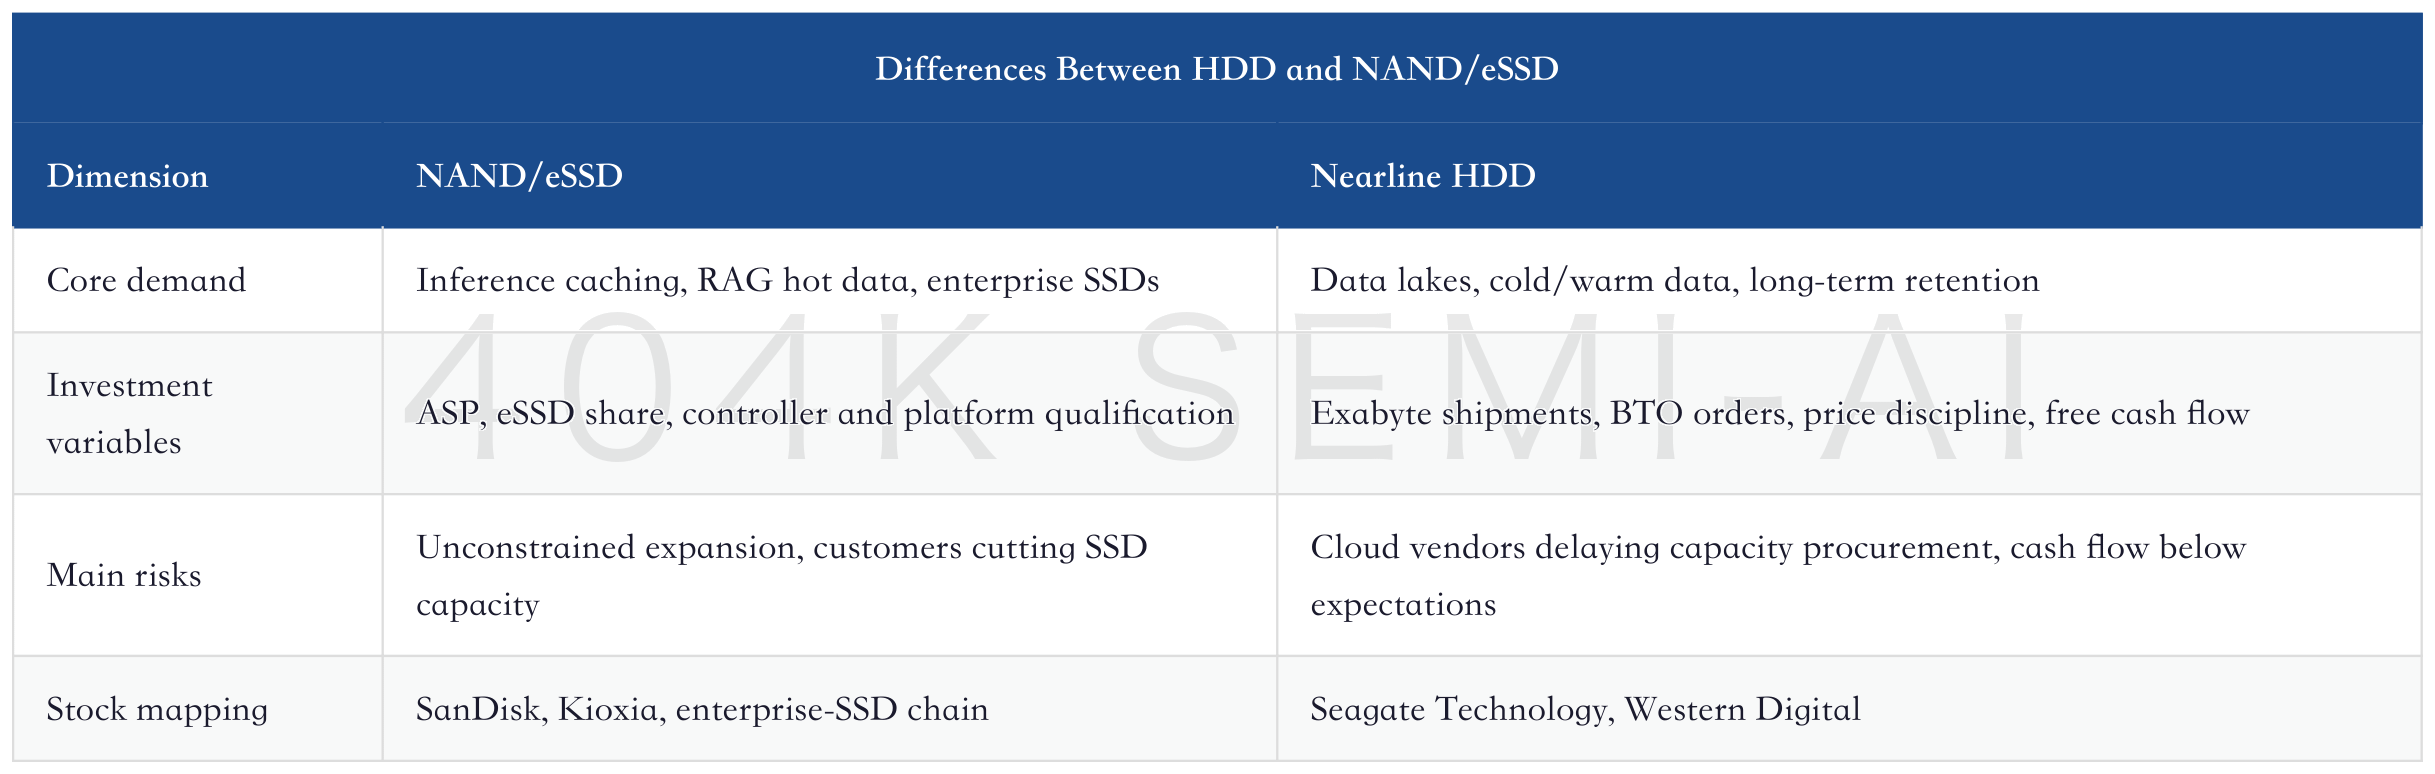
HDD is falsified more slowly than NAND. NAND can be validated quickly through pricing and enterprise-SSD share, while HDD depends more on order visibility, customer inventory, and cash collection. If cloud vendors delay AI data-lake capacity demand, the HDD thesis will not be immediately validated by price; if nearline BTO continues to strengthen, HDD may instead provide more stable cash flow than high-beta memory.
In investment ranking, HDD belongs in the “cash flow” and “defensive AI storage” bucket, and should not be compared with HBM on the slope of price increases. Western Digital’s complexity lies in the fact that both NAND and HDD affect valuation: its share price may at times be driven by NAND elasticity, and at other times supported by HDD cash flow. Seagate Technology is more suitable for observing nearline exabytes, BTO orders, and capital returns.
Equipment, Test, and Materials: Second-Order Beneficiaries of Memory Capex
The second-order beneficiary chain of memory capex is becoming clearer. Long-term investment by SK Hynix and Samsung Electronics will not immediately release supply, but it will continue to drive equipment, test, advanced packaging, materials, fab utilities, and power infrastructure. For the equipment and materials chain, total investment numbers only indicate direction; the order cadence for HBM back-end, new NAND fabs, WoW stacking, and advanced-packaging equipment is more important.
HBM back-end is one of the clearest directions in the equipment chain. SK Hynix’s Cheongju investment explicitly includes a new wafer fab, equipment introduction, and strengthening HBM back-end advanced-packaging capability. Samsung Electronics’ HBM Fab construction will also transmit demand to packaging, test, cleanrooms, materials, and substrates. The profit elasticity of this chain may not be as large as that of memory original manufacturers, but order visibility is longer.
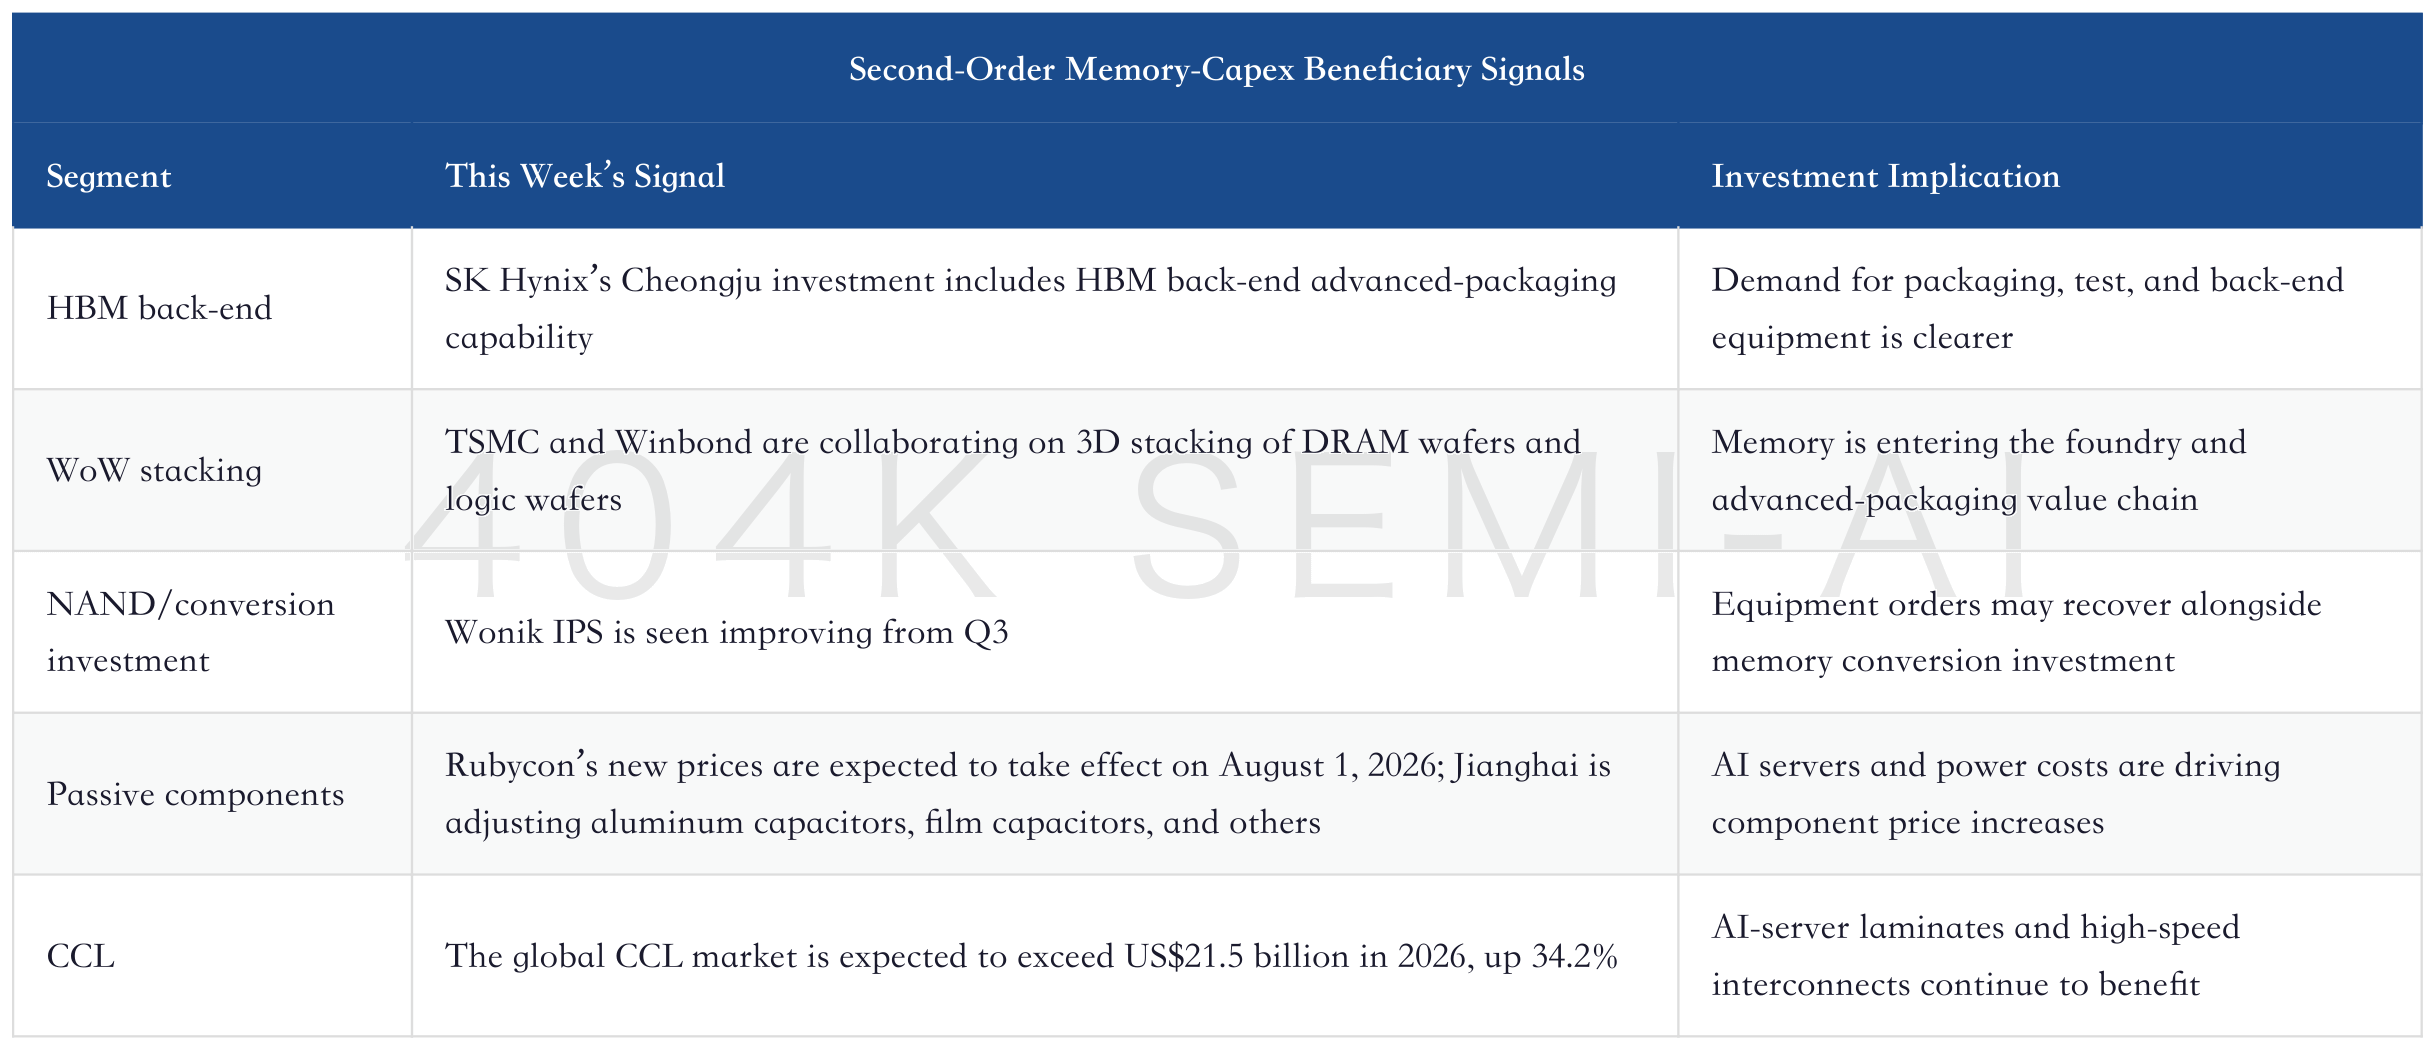
Wonik IPS is a relatively specific Korean anchor in the equipment chain. Its changes show that the equipment chain will not benefit from original-manufacturer price increases in sync; order confirmation and revenue timing will lag.
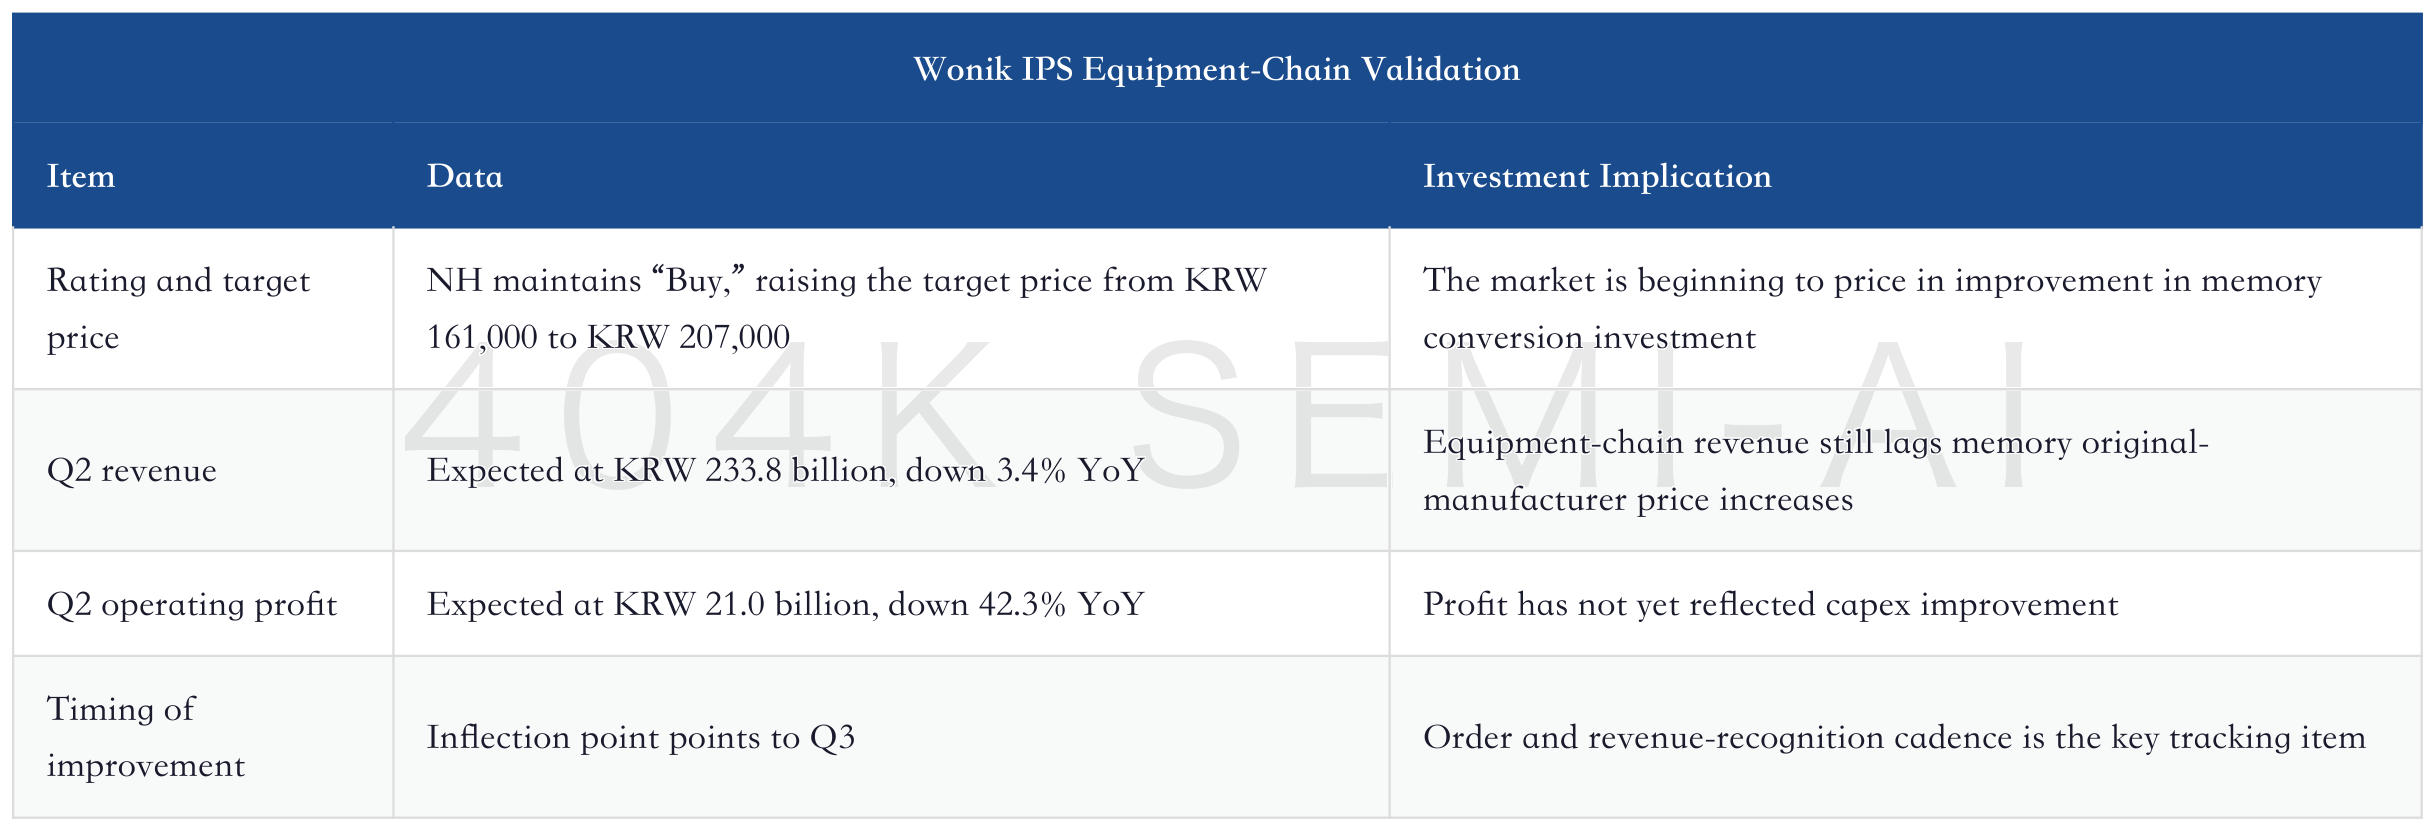
TSMC and Winbond’s WoW collaboration is another important signal. TSMC has historically relied on external memory suppliers such as Samsung Electronics, SK Hynix, and Micron. Now it is bringing Winbond into the local DRAM supply chain and pursuing 3D stacking of DRAM wafers and logic wafers, with the goal of improving AI-chip supply stability. For Winbond, this could expand its business boundary from traditional memory into the AI-server and high-performance-computing supply chain.
Materials and passive components are also beginning to raise prices. Rubycon’s new prices for aluminum electrolytic capacitors, solid aluminum capacitors, and film capacitors are expected to take effect on August 1, 2026, while Jianghai is also adjusting aluminum capacitors, film capacitors, and supercapacitors. The reasons for price increases are not only raw materials; AI-server shipments, logistics, power, and upstream metal costs are all being passed through.
The risks for the equipment and materials chain are order cadence and customer bargaining power. Original-manufacturer capex ambitions are large, but construction cycles are long and order execution will occur in stages. If AI customers begin cutting configurations, or if memory prices rise too quickly and suppress server shipments, the order slope for the equipment and materials chain will also slow.
Downstream Costs and Demand Destruction: Servers, Network Equipment, Smartphones, PCs, EVs
Rising memory prices are shifting profit from downstream hardware chains to upstream original manufacturers. Server customers are willing to pay high prices for HBM, DRAM, enterprise SSDs, and LPDDR because inference cost, latency, and concurrency are all constrained by memory. But when prices rise too quickly, customers will reassess configurations, compress KV cache, reduce storage usage, or defer procurement.
AI servers are the first downstream segment to come under pressure. Vera Rubin’s single-server NAND demand can reach up to 1,152TB, indicating that SSD capacity may rise quickly; HBM also continues to crowd out standard DRAM wafers. When GPUs, HBM, enterprise SSDs, CXL, optical interconnects, and power supplies all become more expensive at the same time, OEMs and cloud customers will allocate every dollar of capex to the areas that improve token throughput the most.
Network equipment and optical interconnects are on the same cost curve. UBS described CXL as a key interconnect for agentic AI infrastructure and raised price targets for Marvell Technology and Astera Labs; on the optical side, there are also signals such as shortages of high-end lasers, sold-out supply over the next two years, and POET needing roughly 10x capacity expansion. When storage, interconnects, and power are all tight, server procurement can easily face “a shortage in one link delaying full-system delivery.”
Cost pressure is more direct for smartphones and PCs. On-device AI requires higher memory capacity and bandwidth, while foldable phones are pushing high-end configurations higher, but consumers are more sensitive to price increases. Foldable smartphone ASP is expected to rise 18% YoY in 2026. A higher share of premium models will bring margin leverage, but it will also raise the risk of demand destruction. On the PC and NAS side, SSD price increases will pass through more quickly to end prices and channel inventory.
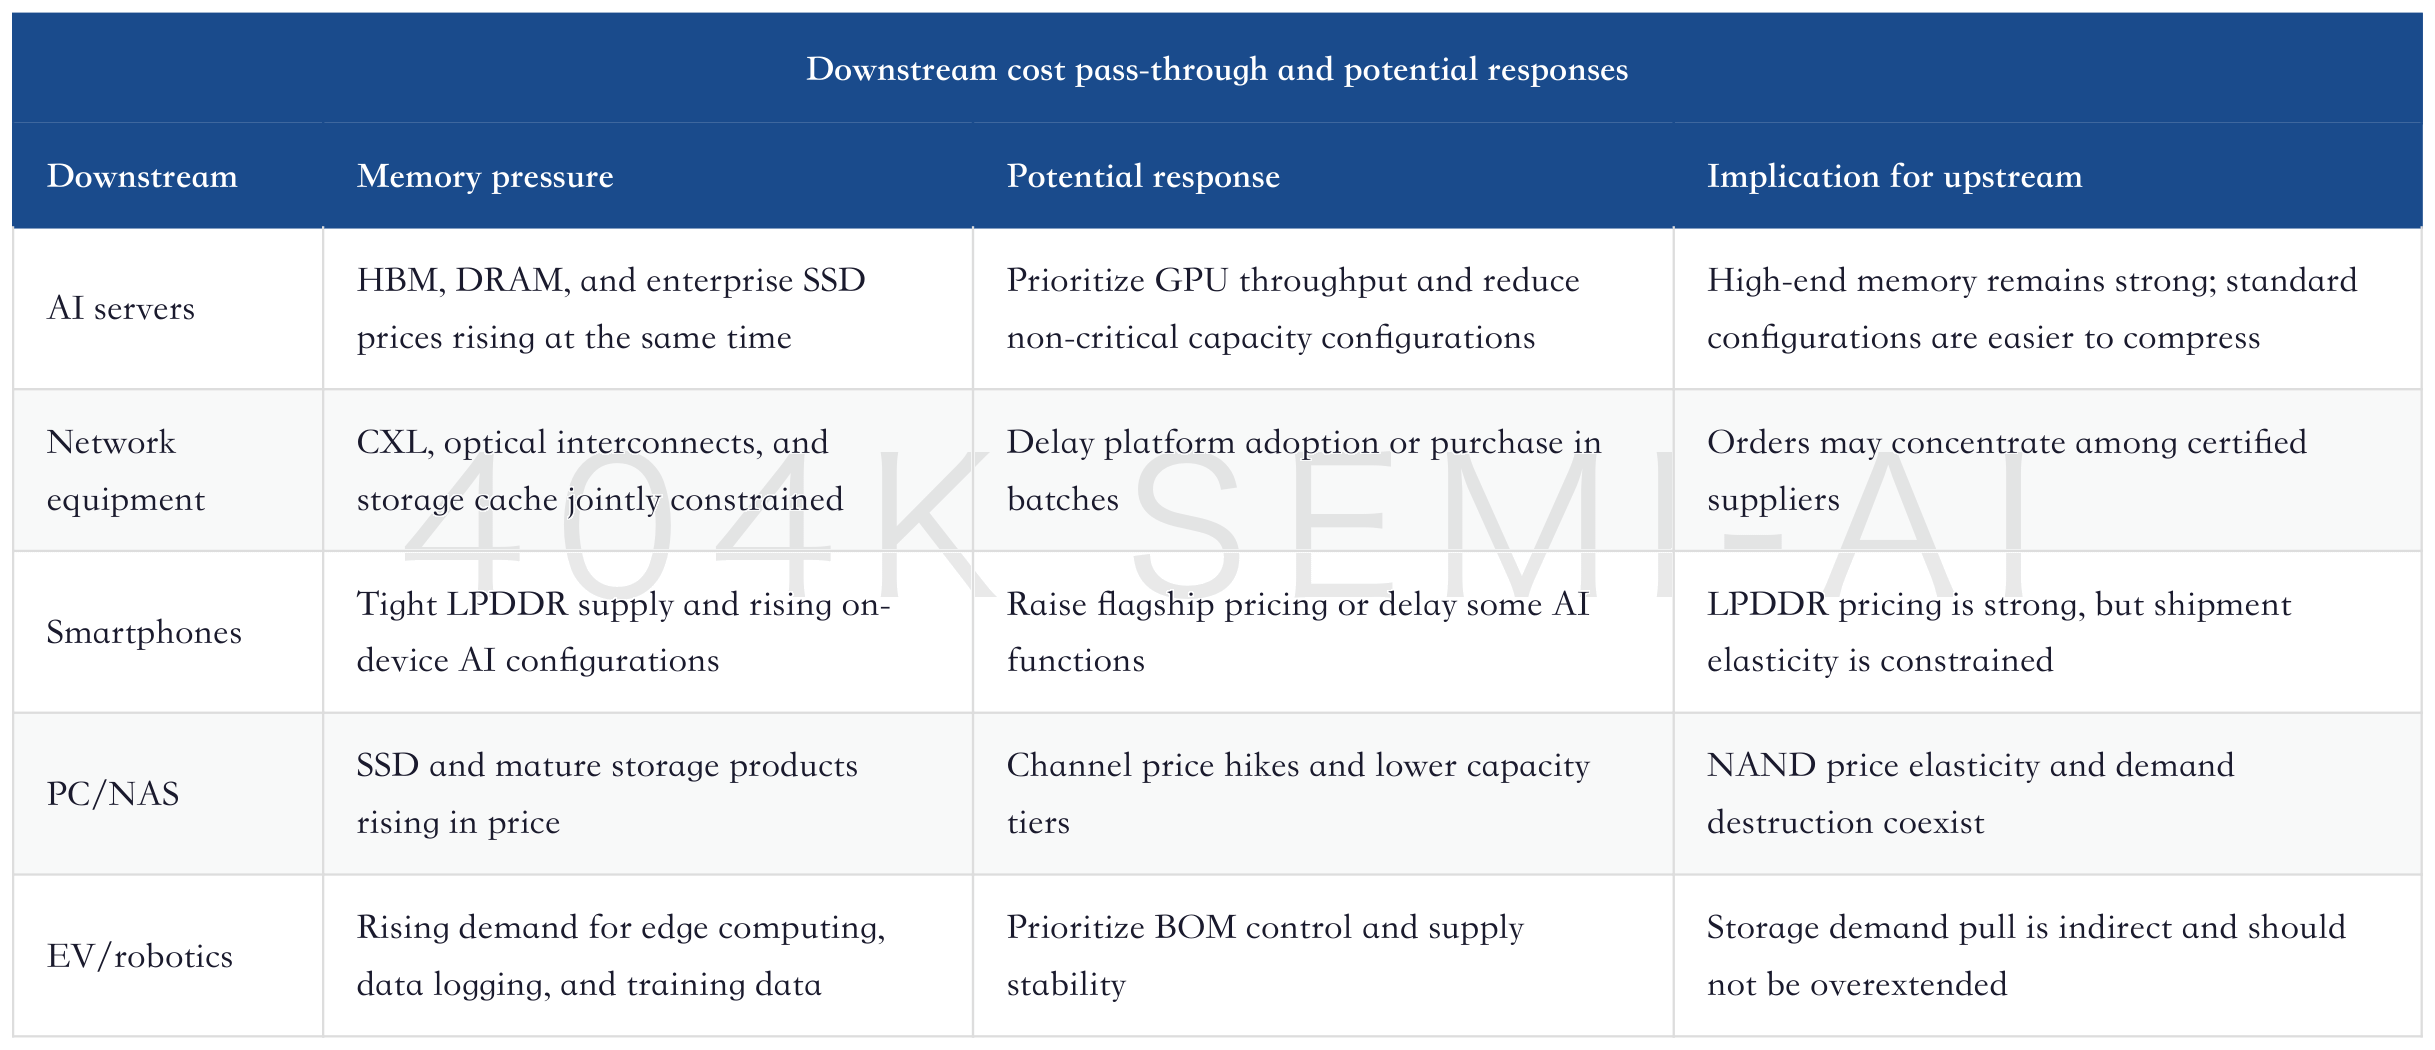
Goldman Sachs’ highlighted risk of “reducing memory usage” deserves to be placed front and center. Nvidia, Qualcomm, and major customers all have incentives to reduce reliance on HBM or high-priced storage. As long as new architectures can complete the same inference tasks with less memory, the pricing power of memory original manufacturers will be reassessed.
The storage pull from the EV and robotics chains is still not firm enough. The stronger evidence that can be confirmed this week is more concentrated in AI data centers, on-device AI, and the direction of the robotics industry, while evidence on EV storage capacity per vehicle or order changes is lacking. Physical AI, autonomous-driving logs, and robotics training data can be monitored for long-term storage demand, but they should not be written directly as short-term order elasticity.
Investment Ranking, Risks, and Falsification
The current investment ranking for memory should first look at certainty, then elasticity, and finally cash flow and second-order beneficiaries. Certainty belongs to HBM/high-end DRAM, elasticity belongs to NAND/eSSD, cash flow belongs to nearline HDD, and second-order benefits belong to equipment, testing, and materials. This ranking will change with the strength of evidence.
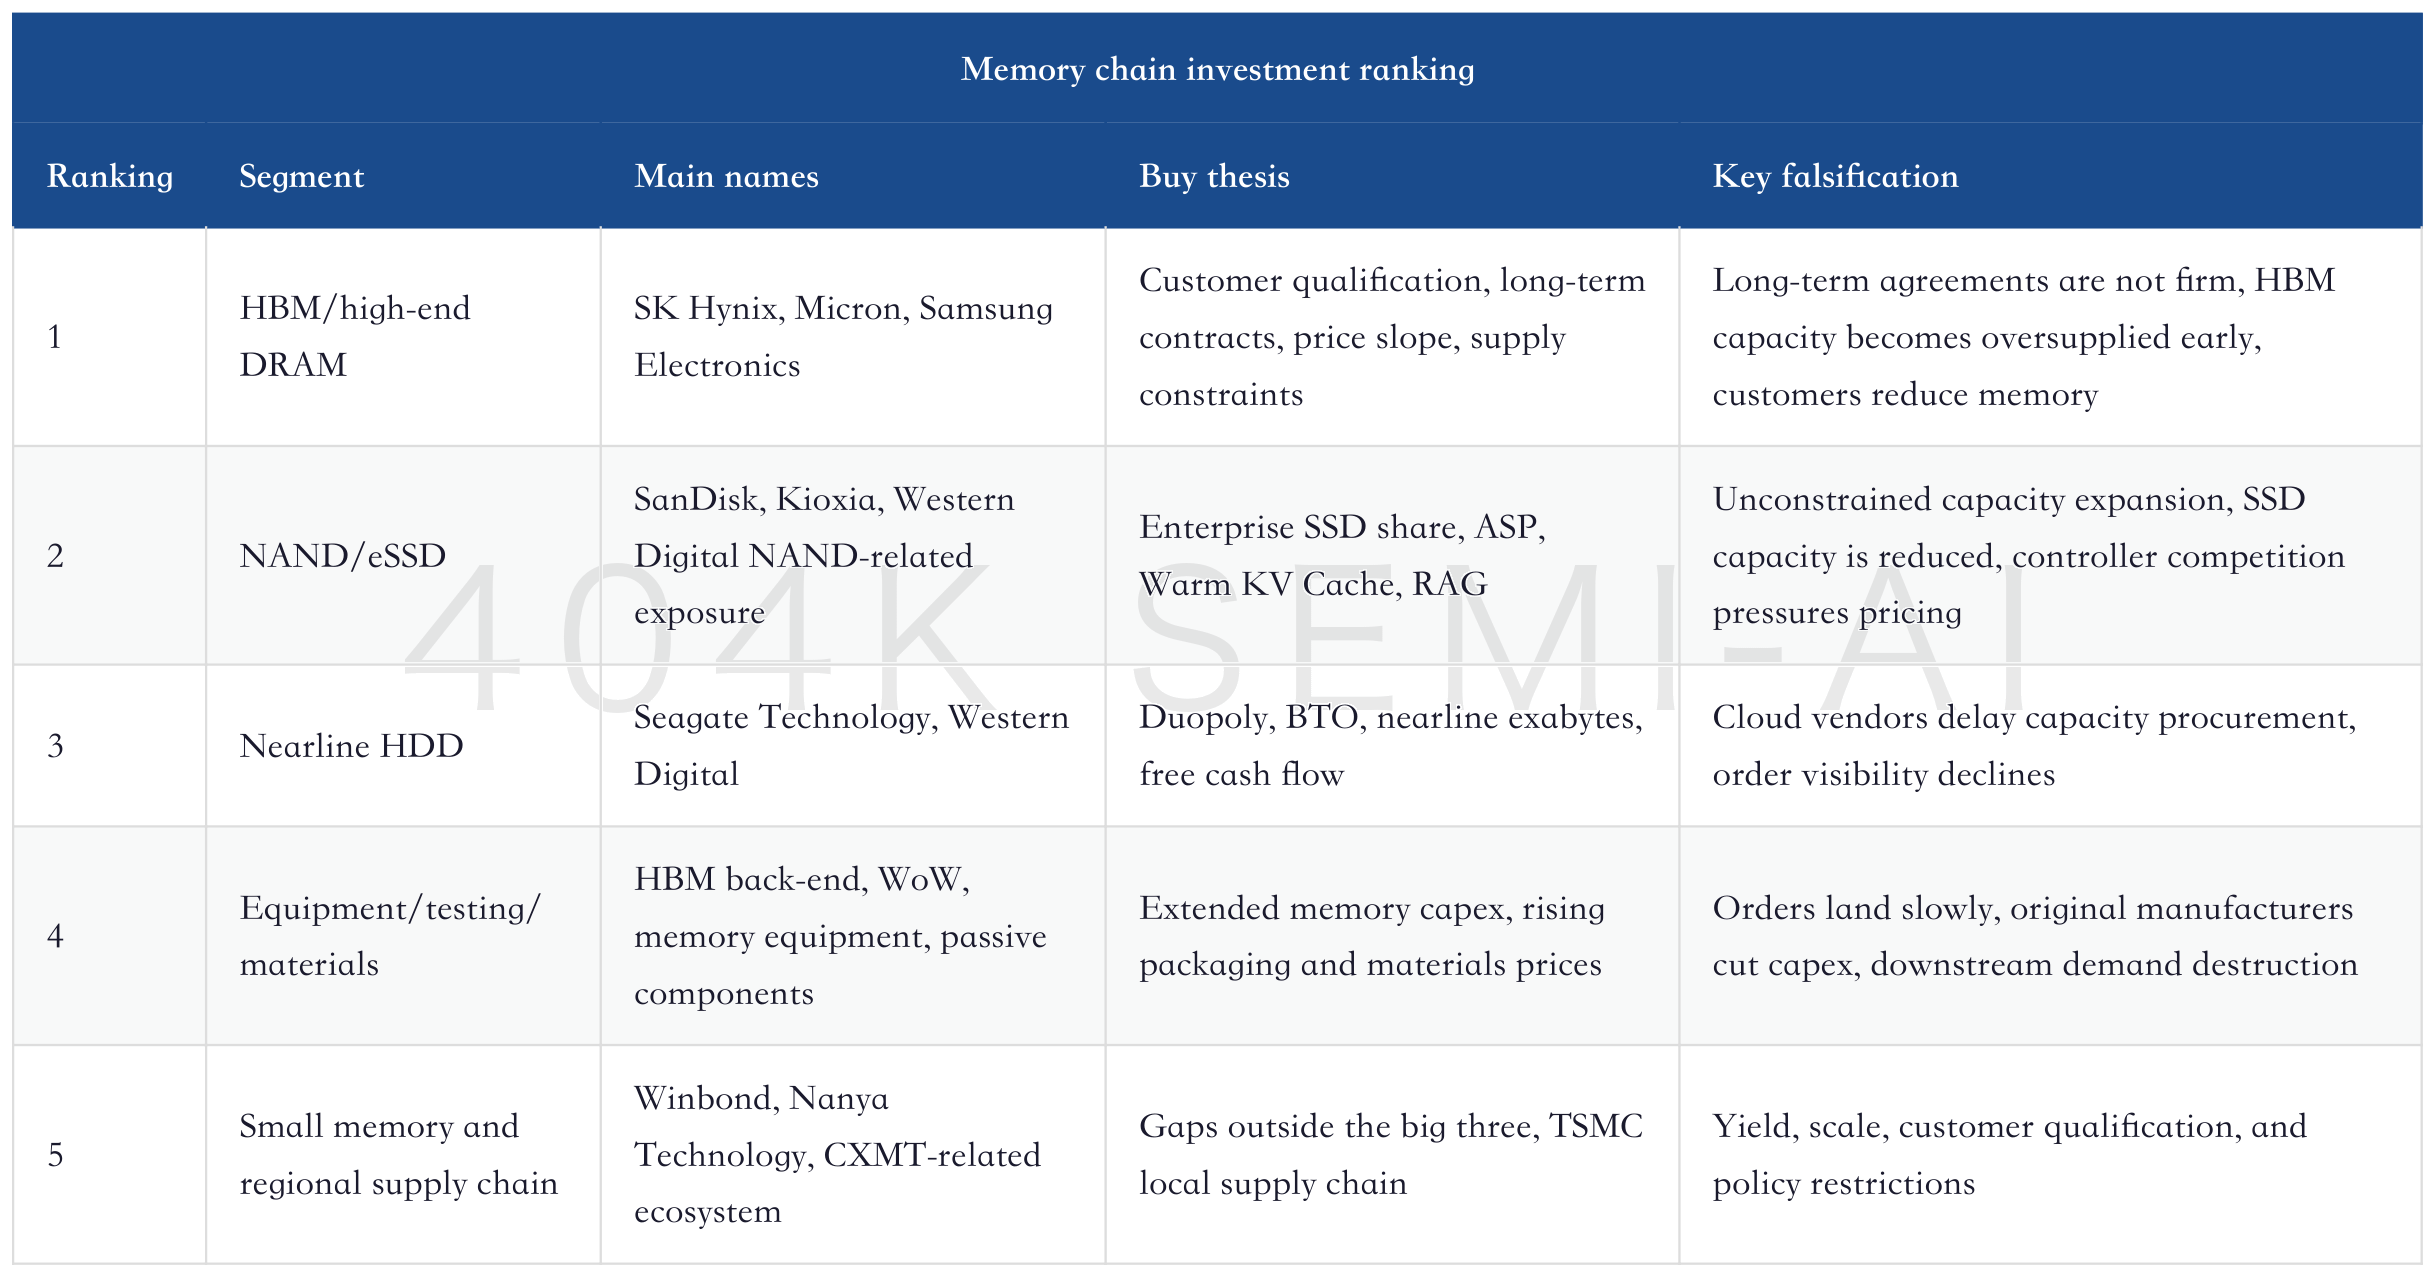
HBM/high-end DRAM remains ranked first. The reason is that the evidence is the firmest: price estimates, long-term contracts, customer lock-ins, long-term Korean investment, and HBM ASP assumptions all point to supply-side bargaining power. Even though U.S.-listed memory stocks pulled back last week, industrial validation for this theme is not over.
NAND/eSSD ranks second because elasticity is greater and counter-evidence can also appear faster. SanDisk’s price target and EPS estimate upgrades, eSSD share rising from 4% to 8%, and Vera Rubin’s single-server NAND demand of up to 1,152TB are all strong signals. But NAND’s pricing discipline has historically been more fragile. Once capacity expansion and share competition resume, profit elasticity will be diluted quickly.
HDD ranks third and is suitable for allocation based on a cash-flow framework. Seagate Technology and Western Digital are not the strongest beta this week, but nearline HDD can absorb demand from AI data lakes and long-term capacity needs. To buy them, investors need to track exabytes, BTO, and free cash flow, rather than just the four words “AI storage.”
Equipment, testing, and materials rank fourth because industry momentum is clear but elasticity lags. Samsung Electronics’ and SK Hynix’s capex ambitions are large, and the direction of HBM back-end and WoW stacking is clear, but it takes time for orders to convert into revenue. The equipment and materials chain is suitable for a higher weighting when original manufacturers’ capacity-expansion ambitions turn into orders.
The biggest macro risk this week is crowded positioning and rate disturbance. The rapid pullback in U.S.-listed memory names shows that high-expectation assets are sensitive to valuation discount rates. If the ROIC of AI capex is questioned again, or if price cuts by model companies such as OpenAI make investors worry that the payback cycle is lengthening, the memory chain will first reflect that risk through valuation compression.
Technical falsification is more fatal than macro falsification. If new model architectures significantly reduce KV cache usage, or if more efficient inference frameworks reduce memory access, the long-term TAM for AI memory will be revised down. This risk has not been confirmed in the short term, but it is the most important black swan for the three major memory manufacturers.
Customer behavior is the most practical falsification indicator. Whether Nvidia, Qualcomm, Apple, and cloud vendors continue to raise memory configurations, accept long-term agreements, and pass higher storage costs through to products and services is a more reliable validation signal than macro narratives. As soon as customers collectively start cutting capacity or deferring procurement, memory price increases will shift from positive catalyst to demand destruction.
Next Week’s Watchlist
The first item next week is SK Hynix’s ADR plan on July 10, 2026. If the transaction proceeds smoothly, global capital will gain a more direct way to express exposure to the HBM leader. The follow-up will be trading activity, pricing feedback, and whether foreign coverage expands.
Second, continue to track memory prices and long-term contract language. The strong DRAM/HBM thesis needs simultaneous validation from spot prices, contract prices, and long-term agreements. If only spot prices rise while long-term agreements are not firm, earnings visibility will be lower than market expectations.
Third, track SanDisk, Kioxia, and enterprise SSD share. The trading elasticity of NAND/eSSD comes from enterprise SSDs, not consumer SSD restocking. Whether eSSD revenue share can continue to rise is a more important validation signal than price target upgrades.
Fourth, track Nvidia LPDDR and SoCAMM allocation. The signal that 2027 LPDDR demand fulfillment is around 60% is very strong. Any subsequent changes in allocation, specifications, suppliers, or SoCAMM capacity will affect low-power memory pricing.
Fifth, track progress in TSMC and Winbond’s WoW cooperation. If DRAM wafer and logic wafer stacking enters a clearer validation or supply stage, Winbond, TSMC advanced packaging, and the local memory supply chain will continue to be re-rated.
Sixth, track signs of downstream configuration cuts. Once AI servers, network equipment, smartphones, and PCs start reducing memory capacity or SSD capacity, the marginal benefit of memory price increases will turn into demand destruction. This signal is more important than a single day’s stock-price move.
Seventh, track nearline HDD orders and cash flow. HDD lacked a new quantitative EB anchor this week. Going forward, Seagate Technology and Western Digital need to provide clearer signals on order visibility, BTO structure, and free cash flow.
Finally, the memory trade has moved from “who can raise prices the most” to “who can retain price increases in the income statement.” For HBM/high-end DRAM, watch customer lock-ins; for NAND/eSSD, watch share and pricing discipline; for HDD, watch cash flow; for equipment and materials, watch order conversion. As long as these four lines are tracked, the memory weekly report will not be pulled off course by short-term price moves.404K SEMI-AI 2026-07-05 Storage Weekly — AI Inference Memory, NAND/eSSD, Nearline HDD
目录
Overall View This Week
Weekly Performance of Storage-Related Names
DRAM/HBM: Supply Rights, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: AI CPU and Rack-Memory Spillover
NAND/eSSD/SSD: Inference, RAG, and Enterprise-SSD Elasticity
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Test, and Materials: Second-Order Beneficiaries of Memory Capex
Downstream Costs and Demand Destruction: Servers, Network Equipment, Smartphones, PCs, EVs
Investment Ranking, Risks, and Falsification
Next Week’s Watchlist
Overview
Overall View This Week
The storage chain has entered its second phase, and the market is starting to distinguish between visibility, elasticity, and cash flow. HBM and high-end DRAM are being bought for customer qualification, supply constraints, and long-term agreements. NAND and enterprise SSDs are being bought for ASP upside and inference-cache elasticity. Nearline HDDs are being bought for the duopoly, BTO orders, and cash-flow quality. All three lines are being pulled by AI, but their valuation, cadence, and falsification conditions are completely different.
Last week’s decline in the U.S. storage chain does not mean the industry logic has weakened. The Roundhill Memory ETF fell 14.87%, Micron fell 13.54%, SanDisk fell 15.41%, while Western Digital and Seagate Technology fell 7.07% and 8.00%, respectively. This looks more like position and valuation digestion after elevated expectations. Comparable Korean and Japanese storage names still rose during the prior market window, suggesting capital has not fully exited storage, but is repricing certainty and elasticity.
The strongest evidence this week remains in memory supply. Jefferies’ memory price estimates extend the upcycle window into 2027 and place real incremental supply pressure in 2028. Micron already has 16 long-term contracts, with more than half of sales locked through 2030. SK Hynix and Samsung Electronics’ long-term investment plans show that AI memory has moved from a short-term upcycle to a national-level capacity project. These data points support valuation rerating for the leaders, but they also make the counter-evidence clearer: if customer LTAs are not binding, or if AI demand falls short of capacity expansion before 2028, cyclical-stock valuations will be compressed again.
AI inference is pushing NAND and SSDs into a more important position. Long context, RAG, agent workloads, and Warm KV Cache turn data from “stored but unused” into “read repeatedly.” The value of enterprise SSDs expands from capacity to latency, throughput, endurance, and cost. The claim that Vera Rubin single-server NAND demand could reach up to 1,152TB is the strongest hard anchor in this week’s NAND elasticity narrative.
Downstream cost pass-through has started to become a risk. Higher storage prices benefit original manufacturers, but they squeeze the BOM of AI servers, networking equipment, PCs, smartphones, and some edge hardware. Goldman Sachs warned that “reducing memory usage” could become a downside risk for Micron and the chip sector, while Nvidia and Qualcomm also have incentives to reduce dependence on high-priced storage. For investment, storage price increases cannot be assessed only through upstream profits; investors also need to watch whether customers begin cutting capacity, changing specifications, or delaying procurement.
Weekly Performance of Storage-Related Names
Short-term prices in the storage chain reflect cooling crowded trades, while industry validation is not over. U.S. ETFs and individual stocks pulled back most in high-elasticity areas, while leading Korean and Japanese names remained strong during the prior market window. This divergence shows that the market is starting to price DRAM/HBM, NAND/eSSD, and HDD cash flow differently.
Among U.S. equities, SanDisk and Micron saw the largest declines, indicating that the market is more concerned in the short term that NAND elasticity and DRAM expectations have already been priced in quickly. Western Digital and Seagate Technology fell less. HDD trading is more tied to orders, cash flow, and capital returns, and was not pushed into the most crowded part of the “price-hike narrative” in the same way as Micron and SanDisk.
The gains in Korean and Japanese names have two implications. First, SK Hynix and Samsung Electronics are driven more by HBM, AI memory capex, and customer qualification, and capital is paying a certainty premium. Second, Kioxia’s rise shows that NAND/eSSD elasticity is being traded again, but this line will depend more on enterprise SSD share, pricing discipline, and the pace of new capacity.
DRAM/HBM: Supply Rights, Long-Term Agreements, and Customer Qualification
The strongest change in this DRAM/HBM cycle is that customers have started to lock in supply early, while manufacturers have begun to use long-term agreements to weaken the traditional spot cycle. Micron’s 16 long-term contracts, SK Hynix’s HBM ASP revision, and Samsung Electronics’ HBM fab investment all point to the same question: whether AI customers are willing to pay higher prices for memory certainty.
The most important pricing framework this week comes from Jefferies. It breaks the memory upcycle into three questions: the pace of price increases, the timing of supply pressure, and the scale of incremental capacity. This framework also makes the bearish case more specific: capacity expansion will come, and what determines the length of the cycle is whether AI demand can absorb the 2028 supply additions.
Micron’s investment thesis now looks more like “high-end memory supply rights” than in the past. Multiple institutions raised target prices after results, but report dates and securities definitions do not provide fully consistent split-adjusted information, so this is treated only as a signal of earnings-assumption upgrades, not as a precise ranking. The more important evidence is that Micron FY26Q3 was cited with revenue of USD 41.5bn and EPS of USD 25.11, above buy-side expectations of USD 38.1bn and USD 22.38; August-quarter guidance was also strong. What the market is really buying is whether the AI memory supercycle can help Micron escape the traditional cyclical-stock discount.
SK Hynix is being bought for HBM customer lock-in and capital-market tradability. Mirae Asset Securities’ assumptions push DRAM, NAND, and HBM ASPs all to higher levels, while the ADR plan improves trading convenience for global capital.
For Samsung Electronics, the key is restoring HBM qualification and supply credibility. Samsung’s 2026-2040 domestic Korea investment vision is about KRW 2,450tn, including about KRW 2,100tn for semiconductors and the Cheonan-Onyang HBM fab. Its elasticity comes from industry price increases, high-end customer validation, HBM back-end capability, and advanced-node progress. Once qualification and yield improve, Samsung will affect both HBM supply distribution and ordinary DRAM price expectations.
Korean capex numbers are large, but they should not be treated as a short-term supply shock. SK Hynix’s fourth Yongin fab is targeted for completion by 2033, while Samsung’s vision extends to 2040. These are long-cycle projects. Short-term pricing is more affected by existing capacity, HBM’s crowding-out of ordinary DRAM wafers, yield, and customer LTAs.
ChangXin Memory Technologies will not immediately crush global DRAM prices. Its roughly USD 3bn, 3-5 year server DRAM LTA with Tencent, and talks with Alibaba Cloud, ByteDance, Xiaomi, and others, show that Chinese cloud vendors are also locking in supply. But its current monthly capacity is about 300,000 wafers, with plans to double to about 600,000 wafers; DDR5 yield still lags, and capacity remains far below domestic demand. In the short term, CXMT looks more like a supply buffer for local Chinese demand than an unconstrained incremental source for global pricing.
The counter-evidence is also clear. Goldman Sachs listed “reducing memory usage” as a key downside risk for Micron and the chip sector, and warned that HBM capacity expansion in 2027-2028 could suppress pricing momentum. The DRAM big three also face U.S. class-action litigation. Although existing cases have required plaintiffs to prove more evidence of collusion, rather than relying only on synchronized price increases or production cuts, the litigation will increase trading volatility.
DRAM/HBM tracking indicators should focus on three things. First, whether LTAs truly cover price, volume, and duration, rather than serving as soft constraints. Second, whether HBM customer qualification continues to concentrate toward SK Hynix, Micron, and Samsung Electronics. Third, whether wafer allocation among ordinary DRAM, HBM, and server DDR continues to crowd each other out after 2027.
LPDDR/SoCAMM: AI CPU and Rack-Memory Spillover
LPDDR/SoCAMM is the most easily underestimated signal this week. It links AI CPUs, rack memory, edge AI, and the Apple supply chain, rather than a traditional handset-memory restocking cycle. Nvidia’s 2027 LPDDR demand is only about 60% fulfilled, and it is cutting SoCAMM capacity in half, showing that even the highest-priority customers cannot freely secure enough low-power, high-bandwidth memory.
The implication of LPDDR/SoCAMM tightness is not simply “higher handset prices.” Low-power memory is now being contested by AI servers, accelerator cards, CPU platforms, and edge AI at the same time. If Nvidia cannot fully secure supply, then Apple, as it pushes edge AI and premium foldables, will struggle to solve memory allocation issues through spot procurement.
Apple is in the most typical squeeze between cost and supply. Counterpoint noted that edge-AI models will lead flagship platforms to prioritize higher memory capacity and bandwidth; foldable phones also combine larger screens, multitasking, and higher price bands. In 2026, book-style foldables are expected to rise to 76% of foldable shipments, while models priced above US$1,600 are expected to rise to 60%. This will increase the memory and packaging value content of premium smartphones and pass BOM pressure to OEMs.
Potential supply from ChangXin Memory cannot be treated as a cost cure for Apple. Korean research views suggest that Apple would find it difficult to procure DRAM from ChangXin Memory, with challenges including quality validation, geopolitical constraints, and ChangXin Memory’s greater capacity allocation toward data-center DDR. Even if Apple secures some supply, it would more likely reduce shortage risk than meaningfully improve costs.
The investment implication of LPDDR/SoCAMM is more about “spillover” than a single-company breakout. Micron, Samsung Electronics, and SK Hynix benefit from tight supply in high-end LPDDR and server DDR; smaller memory vendors such as Winbond Electronics and Nanya Technology benefit from gaps outside the big three; TSMC and Winbond’s WoW collaboration also shows that the logic is moving closer to memory, with memory supply entering the advanced-packaging and foundry ecosystem.
The counter-evidence for this line is model architecture and memory efficiency. If new models significantly reduce KV cache or context-memory usage, LPDDR and SoCAMM tightness would ease. Another counterpoint is configuration cuts by device makers: if handsets and PCs reduce AI memory configurations because of price increases, edge-AI demand would be delayed.
NAND/eSSD/SSD: Inference, RAG, and Enterprise-SSD Elasticity
The NAND investment logic is shifting from the “consumer-electronics inventory cycle” to “inference caching and enterprise-SSD elasticity.” AI inference, RAG, and agent workloads generate large amounts of repeatedly accessed data. Data is not merely kept in cold storage; it must also be quickly retrieved, ranked, cached, and updated. Enterprise SSDs are therefore beginning to capture part of AI infrastructure value outside memory.
SanDisk is the most concentrated NAND-elasticity name this week. Target-price and EPS estimate upgrades, together with a higher eSSD revenue share, show that the market is beginning to move NAND from cyclical-bottom recovery to repricing it as an enterprise-SSD elasticity asset. The target-price framework cannot be precisely ranked against other institutions; here it is only used as a signal of upgraded earnings assumptions.
NAND has higher elasticity than DRAM/HBM, but weaker certainty. DRAM/HBM has customer qualification, long-term agreements, and high-end GPU attachment; NAND requires joint validation from enterprise-SSD orders, price discipline, and supplier restraint. If original manufacturers restart expansion at high prices, or if consumer-electronics demand cannot absorb price increases, NAND’s earnings elasticity will quickly reverse.
Warm KV Cache is the key concept behind NAND revaluation. In long-context and RAG scenarios, models will not keep all data long term in expensive HBM or DRAM. Lower-cost, higher-capacity enterprise SSDs can handle part of hot and warm data. This logic does not mean NAND becomes HBM, but it does raise the priority of enterprise SSDs in AI servers.
Kioxia’s rally should also be viewed in this context. Kioxia is a relatively pure NAND/eSSD asset. If enterprise-SSD pricing and share continue to improve, Kioxia will benefit more directly than diversified memory companies. Conversely, if NAND original manufacturers expand supply to compete for share, Kioxia’s profit elasticity would also be compressed faster.
Phison and the controller chain also deserve tracking. AI inference does not only buy NAND wafers; it also buys controllers, firmware, reliability, read/write performance, and end-to-end system solutions. Profit allocation in enterprise SSDs will be redistributed among NAND original manufacturers, controller companies, and server platforms.
There are three main counterpoints for NAND/eSSD. First, if new NAND capacity is released early or without discipline, ASP will come under pressure first. Second, if customers improve RAG and KV-cache compression, per-server SSD demand will be lower than the high-case scenario. Third, when the AI-server BOM is squeezed by HBM, GPUs, networking, and power, SSD capacity may become a configurable item that gets cut.
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
There were no new nearline exabyte shipment figures for HDDs this week, so the investment conclusion should remain measured. What can be confirmed is that the market is already trading Western Digital and Seagate Technology as part of the AI storage chain, but their logic differs from DRAM/NAND. HDD exposure is about the duopoly structure, BTO orders, nearline capacity growth, and free cash flow.
AI data lakes and RAG will increase demand for long-term data retention. Training data, retrieval corpora, logs, video, synthetic data, and model versions all require low-cost, high-capacity storage. Enterprise SSDs address hot data and low-latency access, while nearline HDDs address capacity cost and long-term retention. The two serve different price tiers within tiered storage.
Western Digital and Seagate Technology have had smaller share-price pullbacks than Micron and SanDisk, indicating that the market has not treated HDDs as the highest-beta trade in the short term. Western Digital has both HDD and NAND-related exposure; Seagate Technology is more purely exposed to nearline HDDs and cash flow. If AI data-center procurement moves into a clearer BTO and long-term order model, Seagate Technology’s cash-flow certainty would become more pronounced.
HDD is falsified more slowly than NAND. NAND can be validated quickly through pricing and enterprise-SSD share, while HDD depends more on order visibility, customer inventory, and cash collection. If cloud vendors delay AI data-lake capacity demand, the HDD thesis will not be immediately validated by price; if nearline BTO continues to strengthen, HDD may instead provide more stable cash flow than high-beta memory.
In investment ranking, HDD belongs in the “cash flow” and “defensive AI storage” bucket, and should not be compared with HBM on the slope of price increases. Western Digital’s complexity lies in the fact that both NAND and HDD affect valuation: its share price may at times be driven by NAND elasticity, and at other times supported by HDD cash flow. Seagate Technology is more suitable for observing nearline exabytes, BTO orders, and capital returns.
Equipment, Test, and Materials: Second-Order Beneficiaries of Memory Capex
The second-order beneficiary chain of memory capex is becoming clearer. Long-term investment by SK Hynix and Samsung Electronics will not immediately release supply, but it will continue to drive equipment, test, advanced packaging, materials, fab utilities, and power infrastructure. For the equipment and materials chain, total investment numbers only indicate direction; the order cadence for HBM back-end, new NAND fabs, WoW stacking, and advanced-packaging equipment is more important.
HBM back-end is one of the clearest directions in the equipment chain. SK Hynix’s Cheongju investment explicitly includes a new wafer fab, equipment introduction, and strengthening HBM back-end advanced-packaging capability. Samsung Electronics’ HBM Fab construction will also transmit demand to packaging, test, cleanrooms, materials, and substrates. The profit elasticity of this chain may not be as large as that of memory original manufacturers, but order visibility is longer.
Wonik IPS is a relatively specific Korean anchor in the equipment chain. Its changes show that the equipment chain will not benefit from original-manufacturer price increases in sync; order confirmation and revenue timing will lag.
TSMC and Winbond’s WoW collaboration is another important signal. TSMC has historically relied on external memory suppliers such as Samsung Electronics, SK Hynix, and Micron. Now it is bringing Winbond into the local DRAM supply chain and pursuing 3D stacking of DRAM wafers and logic wafers, with the goal of improving AI-chip supply stability. For Winbond, this could expand its business boundary from traditional memory into the AI-server and high-performance-computing supply chain.
Materials and passive components are also beginning to raise prices. Rubycon’s new prices for aluminum electrolytic capacitors, solid aluminum capacitors, and film capacitors are expected to take effect on August 1, 2026, while Jianghai is also adjusting aluminum capacitors, film capacitors, and supercapacitors. The reasons for price increases are not only raw materials; AI-server shipments, logistics, power, and upstream metal costs are all being passed through.
The risks for the equipment and materials chain are order cadence and customer bargaining power. Original-manufacturer capex ambitions are large, but construction cycles are long and order execution will occur in stages. If AI customers begin cutting configurations, or if memory prices rise too quickly and suppress server shipments, the order slope for the equipment and materials chain will also slow.
Downstream Costs and Demand Destruction: Servers, Network Equipment, Smartphones, PCs, EVs
Rising memory prices are shifting profit from downstream hardware chains to upstream original manufacturers. Server customers are willing to pay high prices for HBM, DRAM, enterprise SSDs, and LPDDR because inference cost, latency, and concurrency are all constrained by memory. But when prices rise too quickly, customers will reassess configurations, compress KV cache, reduce storage usage, or defer procurement.
AI servers are the first downstream segment to come under pressure. Vera Rubin’s single-server NAND demand can reach up to 1,152TB, indicating that SSD capacity may rise quickly; HBM also continues to crowd out standard DRAM wafers. When GPUs, HBM, enterprise SSDs, CXL, optical interconnects, and power supplies all become more expensive at the same time, OEMs and cloud customers will allocate every dollar of capex to the areas that improve token throughput the most.
Network equipment and optical interconnects are on the same cost curve. UBS described CXL as a key interconnect for agentic AI infrastructure and raised price targets for Marvell Technology and Astera Labs; on the optical side, there are also signals such as shortages of high-end lasers, sold-out supply over the next two years, and POET needing roughly 10x capacity expansion. When storage, interconnects, and power are all tight, server procurement can easily face “a shortage in one link delaying full-system delivery.”
Cost pressure is more direct for smartphones and PCs. On-device AI requires higher memory capacity and bandwidth, while foldable phones are pushing high-end configurations higher, but consumers are more sensitive to price increases. Foldable smartphone ASP is expected to rise 18% YoY in 2026. A higher share of premium models will bring margin leverage, but it will also raise the risk of demand destruction. On the PC and NAS side, SSD price increases will pass through more quickly to end prices and channel inventory.
Goldman Sachs’ highlighted risk of “reducing memory usage” deserves to be placed front and center. Nvidia, Qualcomm, and major customers all have incentives to reduce reliance on HBM or high-priced storage. As long as new architectures can complete the same inference tasks with less memory, the pricing power of memory original manufacturers will be reassessed.
The storage pull from the EV and robotics chains is still not firm enough. The stronger evidence that can be confirmed this week is more concentrated in AI data centers, on-device AI, and the direction of the robotics industry, while evidence on EV storage capacity per vehicle or order changes is lacking. Physical AI, autonomous-driving logs, and robotics training data can be monitored for long-term storage demand, but they should not be written directly as short-term order elasticity.
Investment Ranking, Risks, and Falsification
The current investment ranking for memory should first look at certainty, then elasticity, and finally cash flow and second-order beneficiaries. Certainty belongs to HBM/high-end DRAM, elasticity belongs to NAND/eSSD, cash flow belongs to nearline HDD, and second-order benefits belong to equipment, testing, and materials. This ranking will change with the strength of evidence.
HBM/high-end DRAM remains ranked first. The reason is that the evidence is the firmest: price estimates, long-term contracts, customer lock-ins, long-term Korean investment, and HBM ASP assumptions all point to supply-side bargaining power. Even though U.S.-listed memory stocks pulled back last week, industrial validation for this theme is not over.
NAND/eSSD ranks second because elasticity is greater and counter-evidence can also appear faster. SanDisk’s price target and EPS estimate upgrades, eSSD share rising from 4% to 8%, and Vera Rubin’s single-server NAND demand of up to 1,152TB are all strong signals. But NAND’s pricing discipline has historically been more fragile. Once capacity expansion and share competition resume, profit elasticity will be diluted quickly.
HDD ranks third and is suitable for allocation based on a cash-flow framework. Seagate Technology and Western Digital are not the strongest beta this week, but nearline HDD can absorb demand from AI data lakes and long-term capacity needs. To buy them, investors need to track exabytes, BTO, and free cash flow, rather than just the four words “AI storage.”
Equipment, testing, and materials rank fourth because industry momentum is clear but elasticity lags. Samsung Electronics’ and SK Hynix’s capex ambitions are large, and the direction of HBM back-end and WoW stacking is clear, but it takes time for orders to convert into revenue. The equipment and materials chain is suitable for a higher weighting when original manufacturers’ capacity-expansion ambitions turn into orders.
The biggest macro risk this week is crowded positioning and rate disturbance. The rapid pullback in U.S.-listed memory names shows that high-expectation assets are sensitive to valuation discount rates. If the ROIC of AI capex is questioned again, or if price cuts by model companies such as OpenAI make investors worry that the payback cycle is lengthening, the memory chain will first reflect that risk through valuation compression.
Technical falsification is more fatal than macro falsification. If new model architectures significantly reduce KV cache usage, or if more efficient inference frameworks reduce memory access, the long-term TAM for AI memory will be revised down. This risk has not been confirmed in the short term, but it is the most important black swan for the three major memory manufacturers.
Customer behavior is the most practical falsification indicator. Whether Nvidia, Qualcomm, Apple, and cloud vendors continue to raise memory configurations, accept long-term agreements, and pass higher storage costs through to products and services is a more reliable validation signal than macro narratives. As soon as customers collectively start cutting capacity or deferring procurement, memory price increases will shift from positive catalyst to demand destruction.
Next Week’s Watchlist
The first item next week is SK Hynix’s ADR plan on July 10, 2026. If the transaction proceeds smoothly, global capital will gain a more direct way to express exposure to the HBM leader. The follow-up will be trading activity, pricing feedback, and whether foreign coverage expands.
Second, continue to track memory prices and long-term contract language. The strong DRAM/HBM thesis needs simultaneous validation from spot prices, contract prices, and long-term agreements. If only spot prices rise while long-term agreements are not firm, earnings visibility will be lower than market expectations.
Third, track SanDisk, Kioxia, and enterprise SSD share. The trading elasticity of NAND/eSSD comes from enterprise SSDs, not consumer SSD restocking. Whether eSSD revenue share can continue to rise is a more important validation signal than price target upgrades.
Fourth, track Nvidia LPDDR and SoCAMM allocation. The signal that 2027 LPDDR demand fulfillment is around 60% is very strong. Any subsequent changes in allocation, specifications, suppliers, or SoCAMM capacity will affect low-power memory pricing.
Fifth, track progress in TSMC and Winbond’s WoW cooperation. If DRAM wafer and logic wafer stacking enters a clearer validation or supply stage, Winbond, TSMC advanced packaging, and the local memory supply chain will continue to be re-rated.
Sixth, track signs of downstream configuration cuts. Once AI servers, network equipment, smartphones, and PCs start reducing memory capacity or SSD capacity, the marginal benefit of memory price increases will turn into demand destruction. This signal is more important than a single day’s stock-price move.
Seventh, track nearline HDD orders and cash flow. HDD lacked a new quantitative EB anchor this week. Going forward, Seagate Technology and Western Digital need to provide clearer signals on order visibility, BTO structure, and free cash flow.
Finally, the memory trade has moved from “who can raise prices the most” to “who can retain price increases in the income statement.” For HBM/high-end DRAM, watch customer lock-ins; for NAND/eSSD, watch share and pricing discipline; for HDD, watch cash flow; for equipment and materials, watch order conversion. As long as these four lines are tracked, the memory weekly report will not be pulled off course by short-term price moves.